Strategy vault / Mean reversion
Trend Reversal Tracking Stop Loss Strategy
This strategy uses trend reversal indicators combined with trend tracking stop loss mechanisms to track trends in trending markets and reduce losses in range-bound markets.
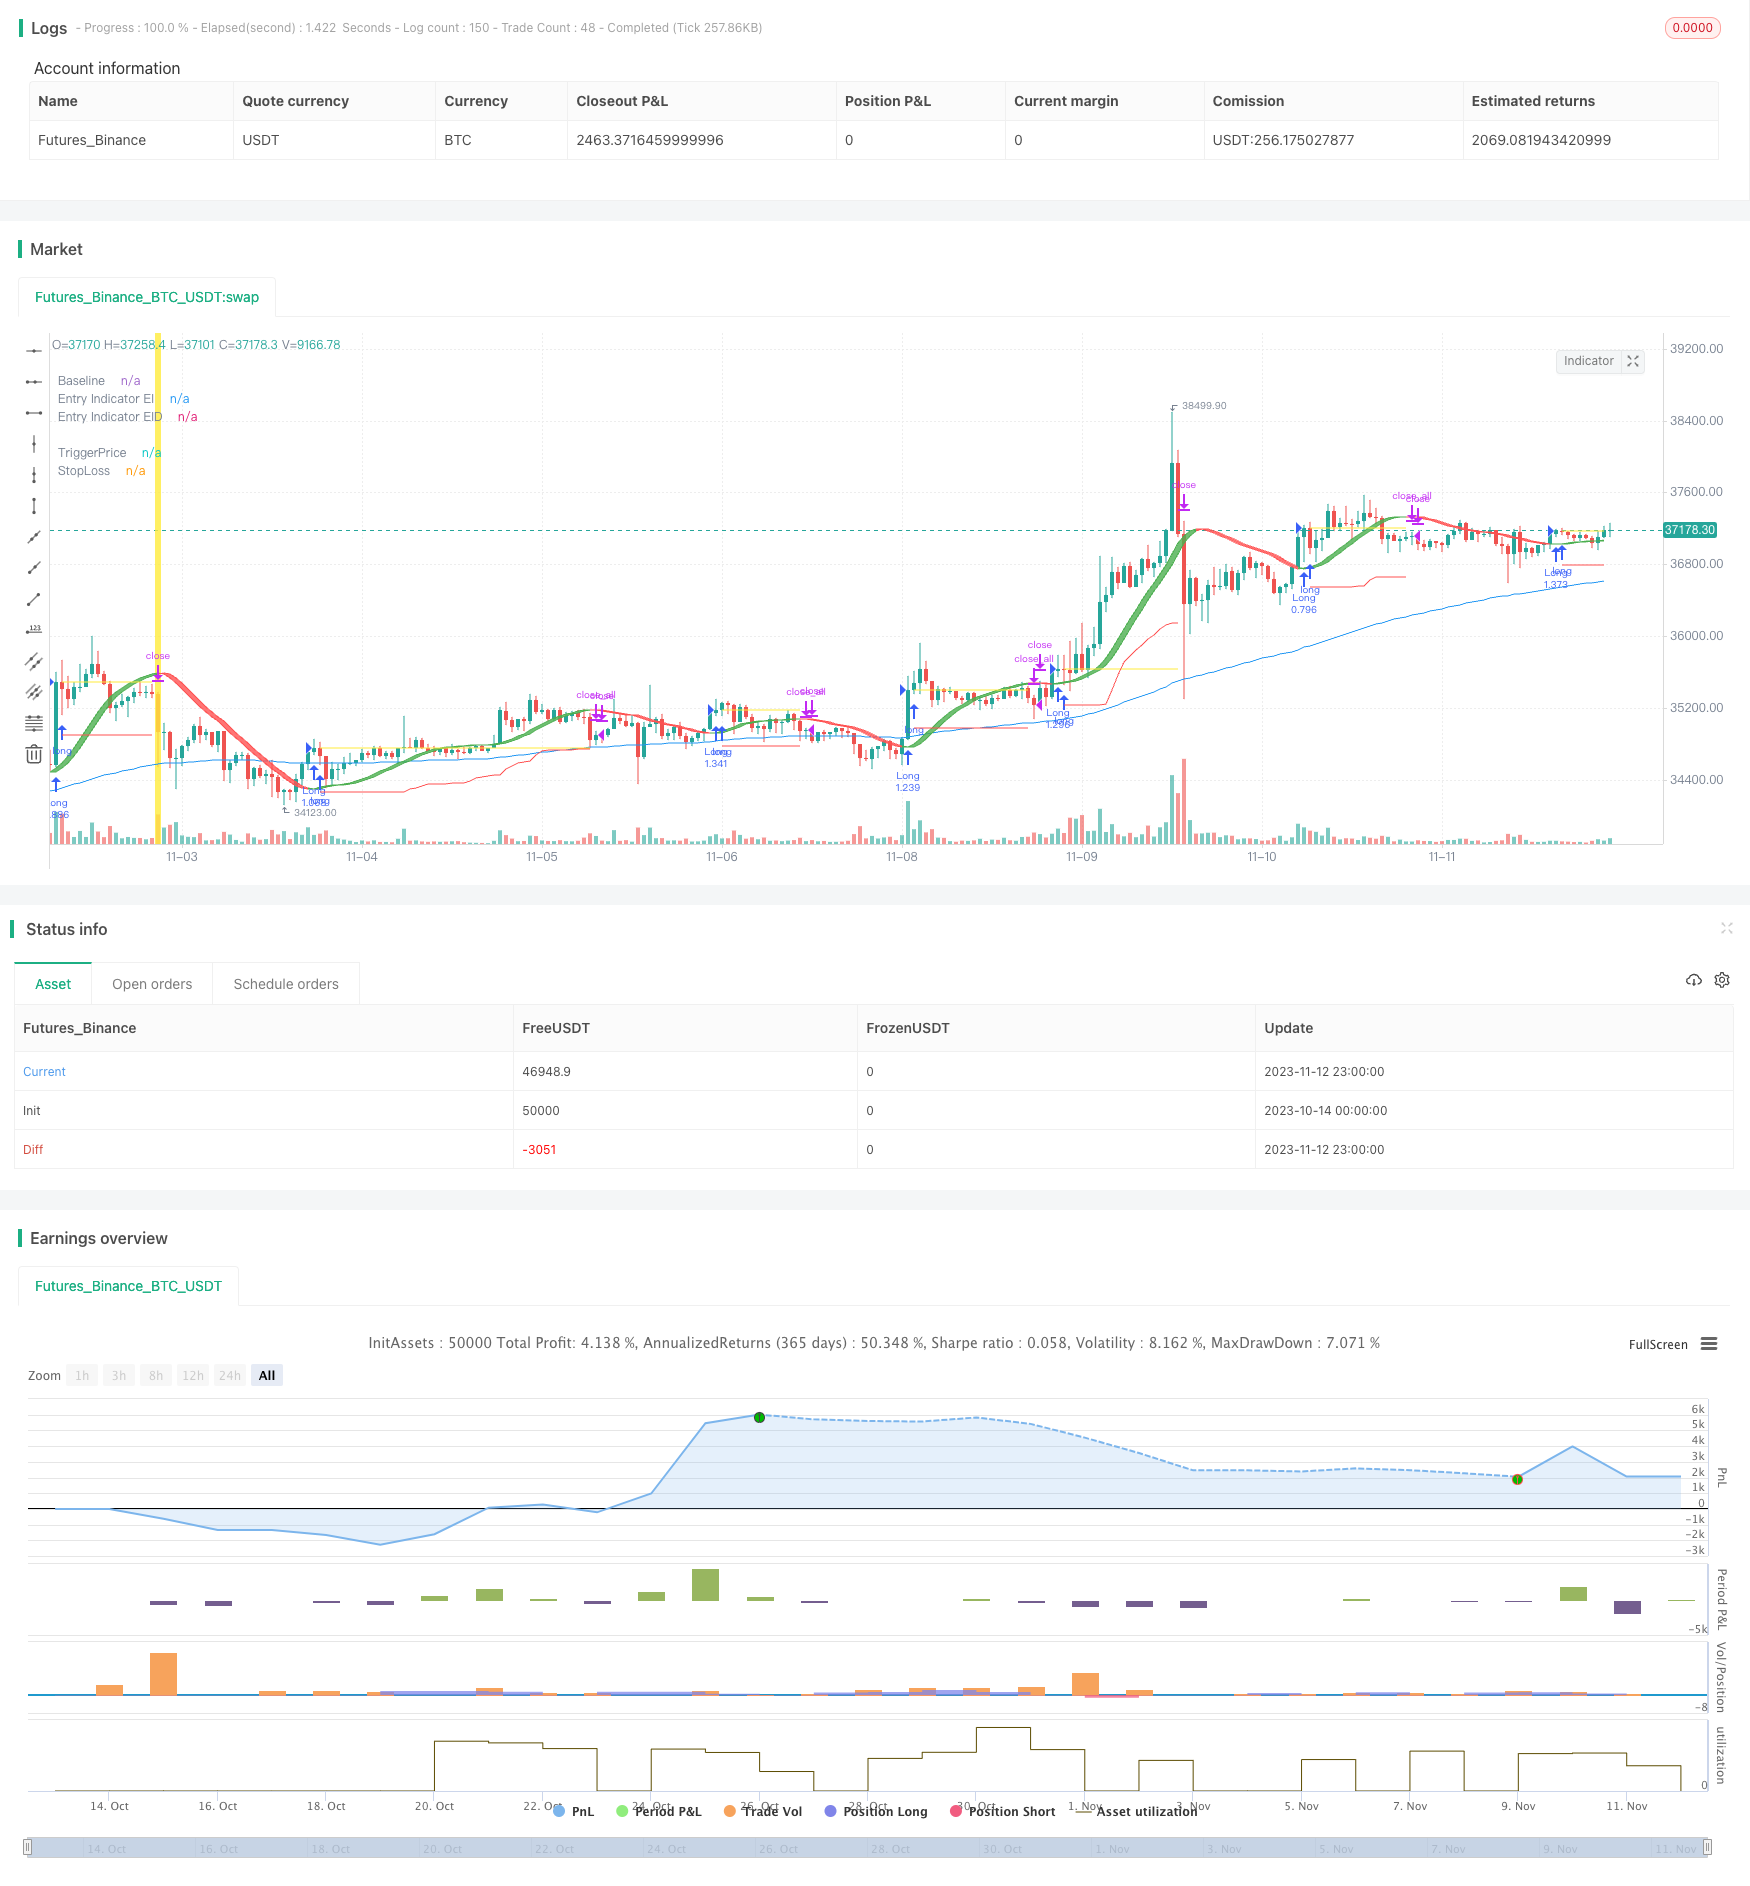
Overview
This strategy uses trend reversal indicators combined with trend tracking stop loss mechanisms to track trends in trending markets and reduce losses in range-bound markets.
Strategy Logic
The strategy uses Hull Moving Average as the main trend indicator. It goes long when price crosses above Hull MA and goes short when price crosses below Hull MA. Meanwhile, McGinley MA is used to confirm the trend.
When price reverses after opening position, validated by Hull MA crossover, the trend change logic will close the current position.
The strategy also utilizes a tracking stop loss mechanism based on ATR calculation. The stop loss price level adjust dynamically following price moves to realize trailing stop of profits.
Advantages
- Use Hull MA to detect trend reversal points sensitively
- Add McGinley MA for trend confirmation, filtering false breakouts
- Adopt dynamic trailing stop loss based on market volatility to control losses
- Respond timely to trend reversals when Hull MA is validated
- Easy to switch parameters for testing and optimization
Risks and Solutions
Stop loss may be triggered in ranging markets
- Expand stop loss buffer wisely
Tracking stop loss may lag behind fast market moves
- Use shorter smooth periods for stop loss to follow price faster
False breakouts may cause unnecessary losses
- Add more confirmations to avoid false signals
Inappropriate parameters may lead to poor performance
- Backtest on different market cycles to find optimal parameters
Optimization Directions
- Add more confirmations like candlestick patterns, Bollinger Bands, RSI etc. to improve signal quality
- Optimize parameters for different products and timeframes to find best parameter sets
- Try machine learning for adaptive parameter optimization
- Refine stop loss algorithms to reduce unnecessary stopping out
- Optimize position sizing and risk management
- Consider adding auto profit taking mechanisms
Conclusion
Overall this is a robust trend following strategy. Compared to fixed stop loss, the dynamic stop loss mechanism adjusts stop level based on market volatility, reducing the probability of being stopped out. The introduction of Hull MA and trend change logic also allows faster response to trend reversals. There are still risks like whipsaw and false breakout. Further optimizations on parameters, stop loss algorithms, position sizing etc. can improve strategy stability across different markets.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 0 | Mode: LongShort | OnlyLong | OnlyShort | Indicator Mode |
| v_input_2 | true | % Risk |
| v_input_3 | 2 | ATR Multiplier |
| v_input_4 | true | ====== Activate Baseline - Switch L/S ====== |
| v_input_5 | 0 | Baseline Type: McGinley | HMA | EHMA | THMA | SMA | EMA | DEMA | TEMA | WMA | VWMA | SMMA | RMA | LSMA | ALMA | Kijun | WWSA |
| v_input_6_close | 0 | BL source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_7 | 50 | BL length |
| v_input_8 | false | ===== Activate Confirmation indicator ===== |
| v_input_9 | 0 | C1 Entry indicator: SMA | HMA | EHMA | THMA | McGinley | EMA | DEMA | TEMA | WMA | VWMA | SMMA | RMA | LSMA | ALMA | Kijun | WWSA |
| v_input_10_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_11 | 5 | Length |
| v_input_12 | true | ====== ENTRY indicator ======= |
| v_input_13 | 0 | EI Entry indicator: HMA | McGinley | EHMA | THMA | SMA | EMA | DEMA | TEMA | WMA | VWMA | SMMA | RMA | LSMA | ALMA | Kijun | WWSA |
| v_input_14_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_15 | 46 | Length |
| v_input_16 | true | ===== Activate Trailing Stop ===== |
| v_input_17 | 0 | TS Traling Stop Type: EMA | HMA | EHMA | THMA | SMA | McGinley | DEMA | TEMA | WMA | VWMA | SMMA | RMA | LSMA | ALMA | Kijun | WWSA |
| v_input_18 | 5 | Smoothing Trail Long EMA |
| v_input_19 | 2 | Smoothing Trail Short EMA |
Source Pine Script
/*backtest
start: 2023-10-14 00:00:00
end: 2023-11-13 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// © Milleman
//@version=4
strategy("MilleMachine", overlay=true, default_qty_type = strategy.percent_of_equity, default_qty_value = 100, initial_capital=10000, commission_type=strategy.commission.percent, commission_value=0.06)


// Additional settings
Mode = input(title="Mode", defval="LongShort", options=["LongShort", "OnlyLong", "OnlyShort","Indicator Mode"])
UseTP = false                               //input(false, title="Use Take Profit?")
QuickSwitch = true                          //input(true, title="Quickswitch")
UseTC = true                                //input(true, title="Use Trendchange?")

// Risk management settings
//Spacer2 = input(false, title="======= Risk management settings =======")
Risk = input(1.0, title="% Risk",minval=0)/100
RRR = 2                                     //input(2,title="Risk Reward Ratio",step=0.1,minval=0,maxval=20)
SL_Mode = false                             // input(true, title="ON = Fixed SL / OFF = Dynamic SL (ATR)")
SL_Fix = 3                                  //input(3,title="StopLoss %",step=0.25, minval=0)/100
ATR = atr(14)                               //input(14,title="Periode ATR"))
Mul = input(2,title="ATR Multiplier",step=0.1)
xATR = ATR * Mul
SL = SL_Mode ? SL_Fix : (1 - close/(close+xATR))

// INDICATORS  //////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////
Ind(type, src, len) =>
    float result = 0
    if type=="McGinley"
        result := na(result[1]) ? ema(src, len) : result[1] + (src - result[1]) / (len * pow(src/result[1], 4))
    if type=="HMA"
        result := wma(2*wma(src, len/2)-wma(src, len), round(sqrt(len)))
    if type=="EHMA"
        result := ema(2*ema(src, len/2)-ema(src, len), round(sqrt(len)))
    if type=="THMA"
        lend = len/2
        result := wma(wma(src, lend/3)*3-wma(src, lend/2)-wma(src,lend), lend)
    if type=="SMA" // Simple
        result := sma(src, len)
    if type=="EMA" // Exponential
        result := ema(src, len)
    if type=="DEMA" // Double Exponential
        e = ema(src, len)
        result := 2 * e - ema(e, len)
    if type=="TEMA" // Triple Exponential
        e = ema(src, len)
        result := 3 * (e - ema(e, len)) + ema(ema(e, len), len)
    if type=="WMA" // Weighted
        result := wma(src, len)
    if type=="VWMA" // Volume Weighted
        result := vwma(src, len)
    if type=="SMMA" // Smoothed
        w = wma(src, len)
        result := (w[1] * (len - 1) + src) / len
    if type == "RMA"
        result := rma(src, len)
    if type=="LSMA" // Least Squares
        result := linreg(src, len, 0)
    if type=="ALMA" // Arnaud Legoux
        result := alma(src, len, 0.85, 6)
    if type=="Kijun" //Kijun-sen
        kijun = avg(lowest(len), highest(len))
        result :=kijun
    if type=="WWSA" // Welles Wilder Smoothed Moving Average
        result := nz(result[1]) + (close -nz(result[1]))/len
    result

// Baseline : Switch from Long to Short and vice versa
BL_Act = input(true, title="====== Activate Baseline - Switch L/S ======")
BL_type = input(title="Baseline Type", defval="McGinley", options=["McGinley","HMA","EHMA","THMA","SMA","EMA","DEMA","TEMA","WMA","VWMA","SMMA","RMA","LSMA","ALMA","Kijun","WWSA"])
BL_src = input(close, title="BL source")
BL_len = input(50, title="BL length", minval=1)
BL = Ind(BL_type,BL_src, BL_len)

// Confirmation indicator
C1_Act = input(false, title="===== Activate Confirmation indicator =====")
C1_type = input(title="C1 Entry indicator", defval="SMA", options=["McGinley","HMA","EHMA","THMA","SMA","EMA","DEMA","TEMA","WMA","VWMA","SMMA","RMA","LSMA","ALMA","Kijun","WWSA"])
C1_src = input(close, title="Source")
C1_len = input(5,title="Length", minval=1)
C1 = Ind(C1_type,C1_src,C1_len)

// Entry indicator : Hull Moving Average
Spacer5 = input(true, title="====== ENTRY indicator =======")
EI_type = input(title="EI Entry indicator", defval="HMA", options=["McGinley","HMA","EHMA","THMA","SMA","EMA","DEMA","TEMA","WMA","VWMA","SMMA","RMA","LSMA","ALMA","Kijun","WWSA"])
EI_src = input(close, title="Source")
EI_Len = input(46,title="Length", minval=1)
EI = Ind(EI_type,EI_src,EI_Len)

// Trail stop settings
TrailActivation = input(true, title="===== Activate Trailing Stop =====")
TS_type = input(title="TS Traling Stop Type", defval="EMA", options=["McGinley","HMA","EHMA","THMA","SMA","EMA","DEMA","TEMA","WMA","VWMA","SMMA","RMA","LSMA","ALMA","Kijun","WWSA"])
TrailSLScaling = 1 //input(100, title="SL Scaling", minval=0, step=5)/100
TrailingSourceLong = Ind(TS_type,low,input(5,"Smoothing Trail Long EMA", minval=1))
TrailingSourceShort = Ind(TS_type,high,input(2,"Smoothing Trail Short EMA", minval=1))

//VARIABLES MANAGEMENT
TriggerPrice = 0.0, TriggerPrice := TriggerPrice[1]
TriggerSL = 0.0, TriggerSL := TriggerSL[1]
SLPrice = 0.0, SLPrice := SLPrice[1], TPPrice = 0.0, TPPrice := TPPrice[1]
isLong = false, isLong := isLong[1], isShort = false, isShort := isShort[1]

//LOGIC
GoLong = crossover(EI,EI[1]) and (strategy.position_size == 0.0 and QuickSwitch) and (not BL_Act or BL/BL[1] > 1) and (not C1_Act or C1>C1[1]) and (Mode == "LongShort" or Mode == "OnlyLong")
GoShort = crossunder(EI,EI[1]) and (strategy.position_size == 0.0 and QuickSwitch) and (not BL_Act or BL/BL[1] < 1) and (not C1_Act or C1<C1[1]) and (Mode == "LongShort" or Mode == "OnlyShort")
ExitLong = isLong and crossunder(EI,EI[1]) and UseTC
ExitShort = isShort and crossover(EI,EI[1]) and UseTC

//FRAMEWORK
//Reset Long-Short memory
if isLong and strategy.position_size == 0.0
    isLong := false
if isShort and strategy.position_size == 0.0
    isShort := false
//Long
if GoLong
    isLong := true, TriggerPrice := close, TriggerSL := SL
    TPPrice := UseTP? TriggerPrice * (1 + (TriggerSL * RRR)) : na
    SLPrice := TriggerPrice * (1-TriggerSL)
    Entry_Contracts = strategy.equity * Risk / ((TriggerPrice-SLPrice)/TriggerPrice) / TriggerPrice
    strategy.entry("Long", strategy.long, comment=tostring(round((TriggerSL/TriggerPrice)*1000)), qty=Entry_Contracts)
    strategy.exit("TPSL","Long", limit=TPPrice, stop=SLPrice)
if isLong
    NewValSL = TrailingSourceLong * (1 - (SL*TrailSLScaling))
    if TrailActivation and NewValSL > SLPrice
        SLPrice := NewValSL
    strategy.exit("TPSL","Long", limit=TPPrice, stop=SLPrice)
if ExitLong
    strategy.close_all(comment="TrendChange")
    isLong := false

//Short
if GoShort
    isShort := true, TriggerPrice := close, TriggerSL := SL
    TPPrice := UseTP? TriggerPrice * (1 - (TriggerSL * RRR)) : na
    SLPrice := TriggerPrice * (1 + TriggerSL)
    Entry_Contracts = strategy.equity * Risk / ((SLPrice-TriggerPrice)/TriggerPrice) / TriggerPrice
    strategy.entry("Short", strategy.short, comment=tostring(round((TriggerSL/TriggerPrice)*1000)), qty=Entry_Contracts)
    strategy.exit("TPSL","Short", limit=TPPrice, stop=SLPrice)
if isShort
    NewValSL = TrailingSourceShort * (1 + (SL*TrailSLScaling))
    if TrailActivation and NewValSL < SLPrice
        SLPrice := NewValSL
    strategy.exit("TPSL","Short", limit=TPPrice, stop=SLPrice)
if ExitShort
    strategy.close_all(comment="TrendChange")
    isShort := false

//VISUALISATION
plot(BL_Act?BL:na, color=color.blue,title="Baseline")
plot(C1_Act?C1:na, color=color.yellow,title="confirmation Indicator")
EIColor = EI>EI[1] ? color.green : color.red
Fill_EI = plot(EI, color=EIColor, linewidth=1, transp=40, title="Entry Indicator EI")
Fill_EID = plot(EI[1], color=EIColor, linewidth=1, transp=40, title="Entry Indicator EID")
fill(Fill_EI,Fill_EID, title="EI_Fill", color=EIColor,transp=50)

plot(strategy.position_size != 0.0 and (isLong or isShort) ? TriggerPrice : na, title="TriggerPrice", color=color.yellow, style=plot.style_linebr)
plot(strategy.position_size != 0.0 and (isLong or isShort) ? TPPrice : na, title="TakeProfit", color=color.green, style=plot.style_linebr)
plot(strategy.position_size != 0.0 and (isLong or isShort) ? SLPrice : na, title="StopLoss", color=color.red, style=plot.style_linebr)
bgcolor(isLong[1] and cross(low,SLPrice) and low[1] > SLPrice and TriggerPrice>SLPrice ? color.yellow : na, transp=75, title="SL Long")
bgcolor(isShort[1] and cross(high,SLPrice) and high[1] < SLPrice and TriggerPrice<SLPrice ? color.yellow : na, transp=75, title="SL Short")Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-14. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Trend-Reversal-Tracking-Stop-Loss-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Reversal Trading Strategy with Bollinger Bands RSI ADX and ATRPine Script · Mean reversion · 1h
- CCTBBO Reversal Tracking StrategyPine Script · Mean reversion · 45m
- Bollinger Bands Trend Reversal StrategyPine Script · Mean reversion · 10m
- MACD RSI and EMA StrategyPine Script · Mean reversion · 1d
- Multi Indicator Trend Reversal Volatility Conditional Selective Options Selling StrategyPine Script · Mean reversion · 1h
- A Multi Period Trading Strategy Based on Moving AveragesPine Script · Mean reversion · 1h