Strategy vault / Trend following
Triple Bollinger Bands Touch Trend Following Quantitative Trading Strategy
This strategy is an improved version of the traditional Bollinger Bands trend-following system. It monitors price action for three consecutive touches of the Bollinger Bands to confirm trend reliability, resulting in…
Overview
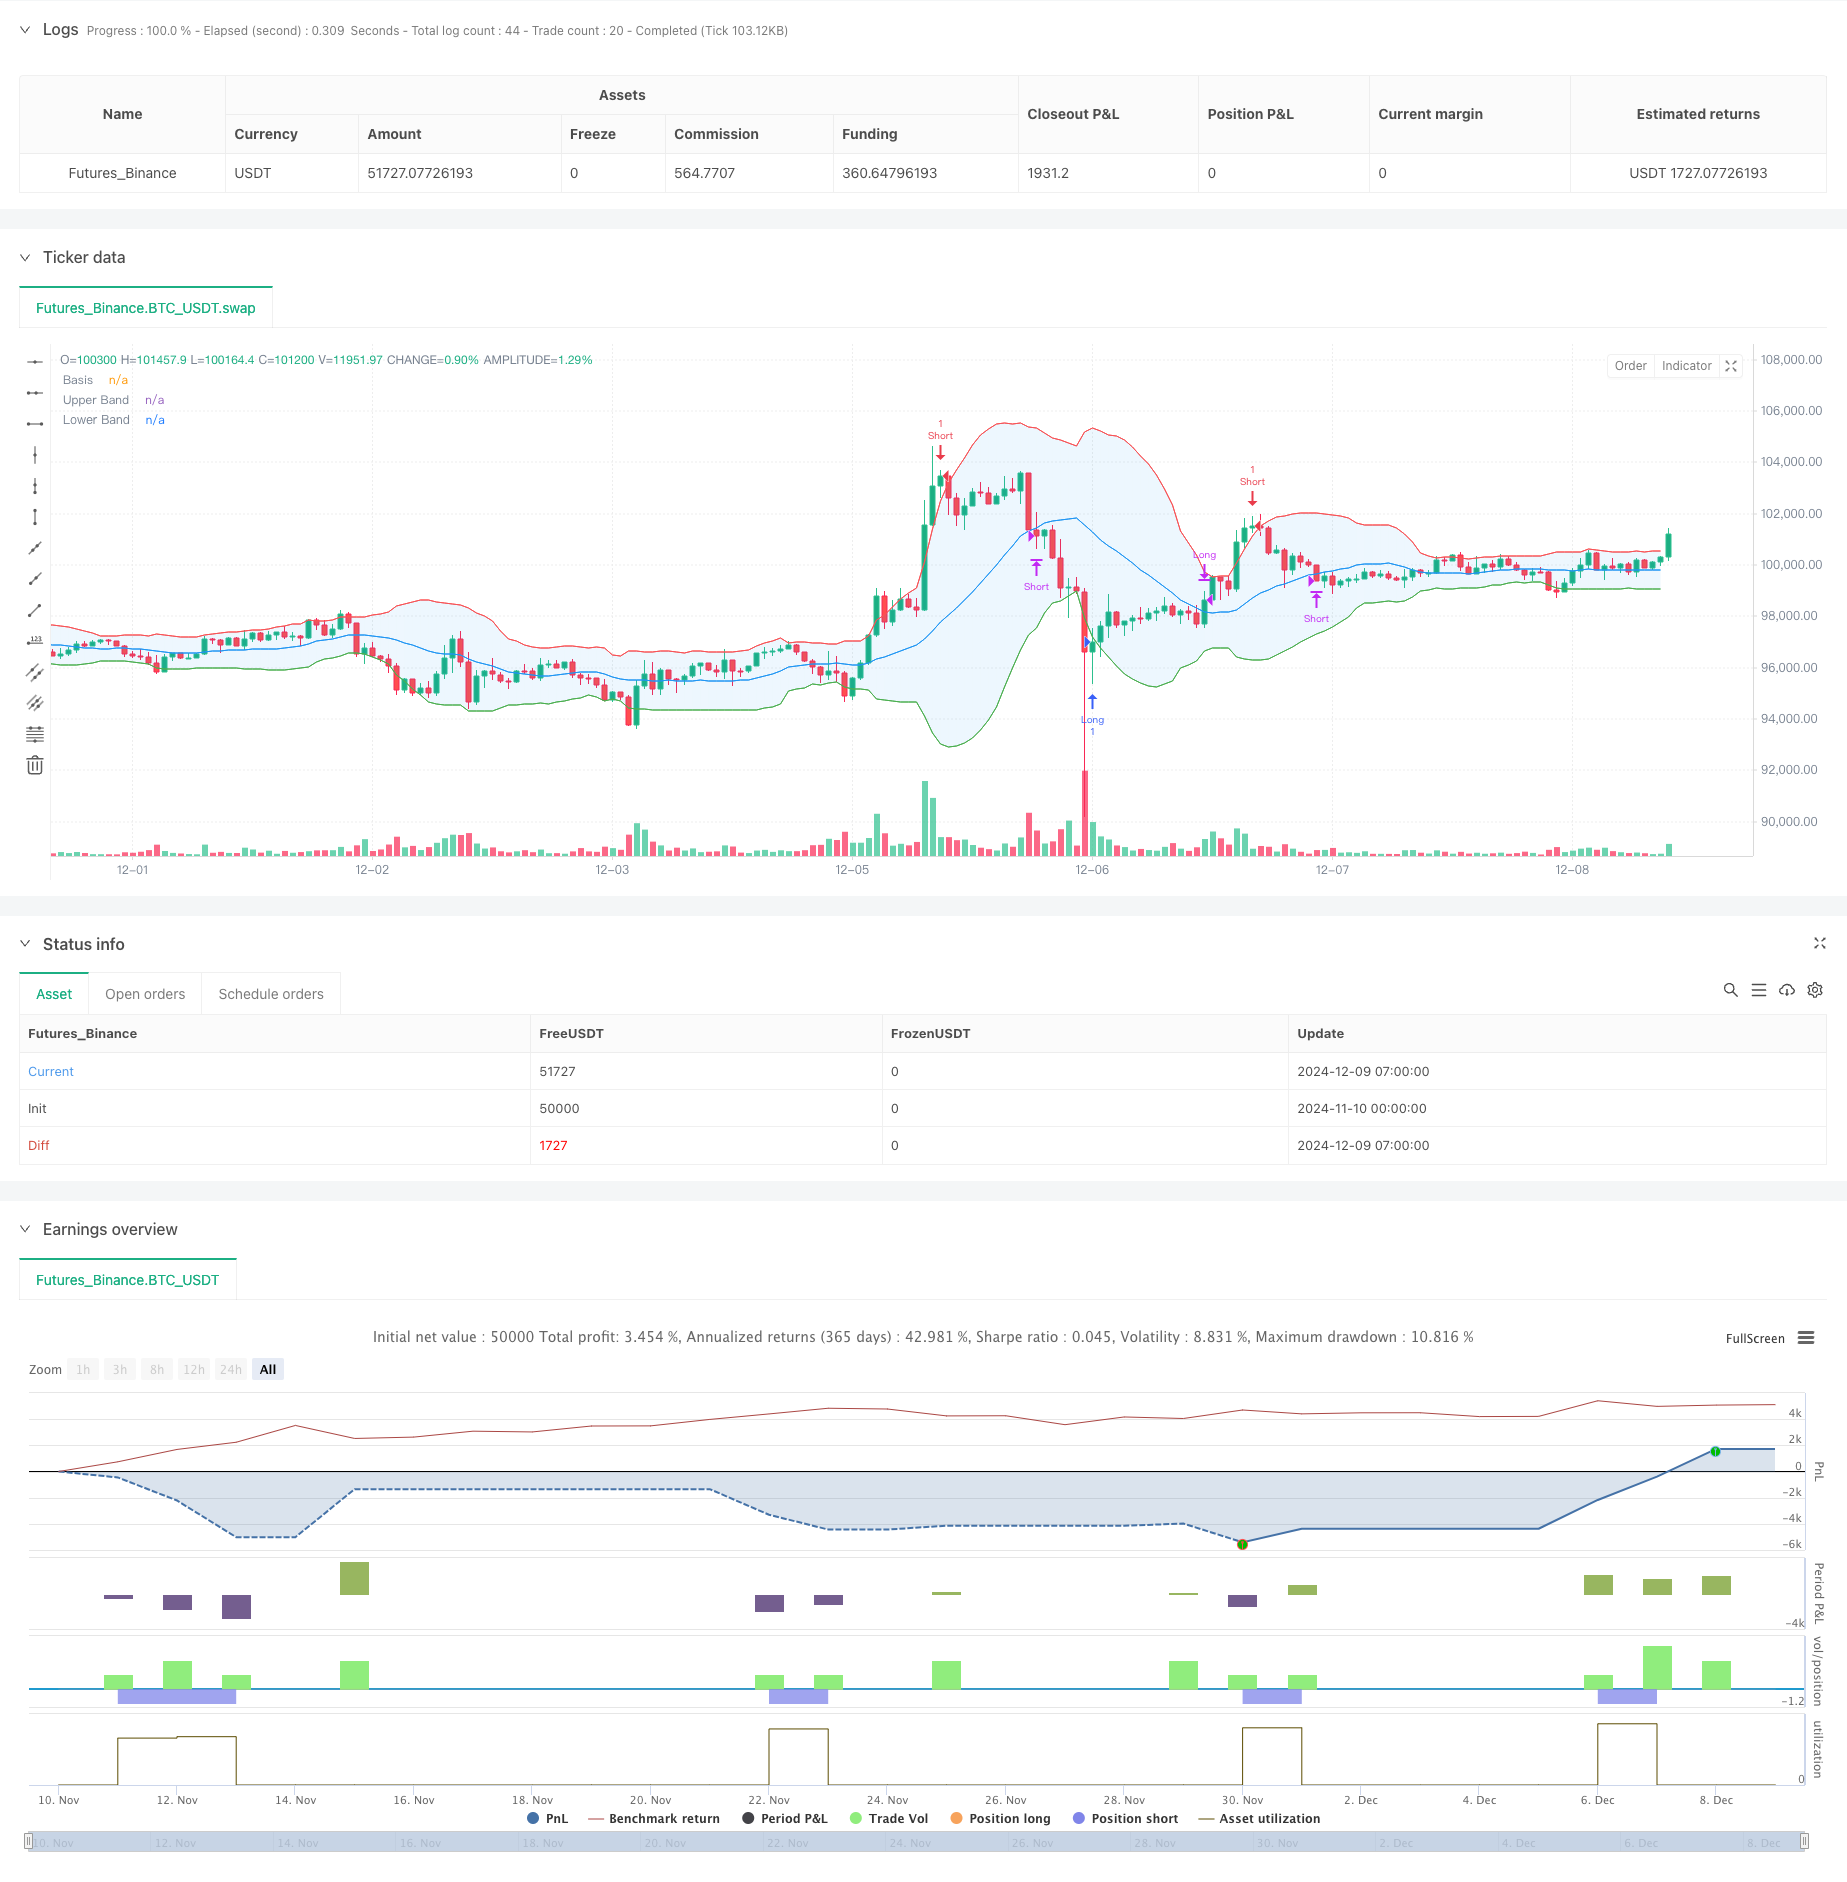
This strategy is an improved version of the traditional Bollinger Bands trend-following system. It monitors price action for three consecutive touches of the Bollinger Bands to confirm trend reliability, resulting in higher win rates. The strategy uses a 20-period moving average as the middle band and 2 standard deviations for the upper and lower bands. Through detailed analysis of price relationships with band boundaries, it achieves a trading system with unique advantages.
Strategy Principles
The core logic relies on a counting mechanism to identify sustained price touches of the Bollinger Band boundaries. The system generates a long signal when price breaks below the lower band three consecutive times, and a short signal when price breaks above the upper band three consecutive times. This mechanism effectively filters out false breakouts, improving trading reliability. The strategy uses the middle band (20-period moving average) as an exit signal, completing trades when price returns to the middle band. This design ensures both trend capture and timely profit-taking.
Strategy Advantages
- High Reliability: Requiring three consecutive touches of band boundaries to confirm trading signals significantly reduces the impact of false breakouts.
- Risk Control: Using the moving average as an exit point enables timely stop-loss when trends reverse.
- Strong Adaptability: Strategy parameters can be adjusted for different market conditions, offering good universality.
- Moderate Trading Frequency: Strict entry conditions prevent overtrading.
- Rational Money Management: Position sizing based on account equity percentage ensures controlled risk.
Strategy Risks
- Ranging Market Risk: May generate frequent false signals in sideways markets.
- Slippage Risk: Potential for significant slippage losses during volatile market conditions.
- Parameter Sensitivity: Strategy performance heavily depends on Bollinger Bands parameter settings.
- Trend Reversal Risk: May incur substantial losses during sudden trend reversals.
Strategy Optimization Directions
- Incorporate Volume Indicators: Combining volume analysis can improve signal reliability.
- Dynamic Parameter Adjustment: Adapt Bollinger Bands parameters based on market volatility.
- Add Trend Confirmation Indicators: Include additional technical indicators to confirm trend direction.
- Optimize Stop-Loss Mechanism: Design more flexible stop-loss approaches for different market environments.
- Enhance Position Management: Dynamically adjust position sizes based on signal strength.
Summary
This strategy improves upon traditional Bollinger Bands trading systems by implementing a highly reliable trend-following approach. Its unique triple-touch confirmation mechanism effectively increases win rates, while the moving average-based exit mechanism provides a rational profit-taking solution. Though inherent risks exist, the suggested optimization directions can further enhance strategy stability and profitability.
Source Pine Script
/*backtest
start: 2024-11-10 00:00:00
end: 2024-12-09 08:00:00
period: 1h
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=6
strategy("Bollinger Bands Strategy - 3 Crossings", overlay=true)

// Input Parameters
length = input.int(20, title="Bollinger Bands Length", minval=1)
src = input(close, title="Source")
mult = input.float(2.0, title="Multiplier", step=0.1)

// Calculate Bollinger Bands
basis = ta.sma(src, length)
dev = mult * ta.stdev(src, length)
upper = basis + dev
lower = basis - dev

// Plot Bollinger Bands
plotBasis = plot(basis, color=color.blue, title="Basis")
plotUpper = plot(upper, color=color.red, title="Upper Band")
plotLower = plot(lower, color=color.green, title="Lower Band")
fill(plot1=plotUpper, plot2=plotLower, color=color.new(color.blue, 90), title="Band Fill")

// Counter Variables
var int longCrossCount = 0
var int shortCrossCount = 0

// Detect Crossings
longCondition = close < lower  // Price closes below the lower band
shortCondition = close > upper  // Price closes above the upper band

if longCondition
    longCrossCount += 1  // Increment the counter for long
    shortCrossCount := 0  // Reset the short counter

if shortCondition
    shortCrossCount += 1  // Increment the counter for short
    longCrossCount := 0  // Reset the long counter

if not longCondition and not shortCondition
    longCrossCount := 0  // Reset if no crossing
    shortCrossCount := 0

// Entry and Exit Rules
if longCrossCount >= 3 and strategy.position_size <= 0
    strategy.entry("Long", strategy.long)
    longCrossCount := 0  // Reset the counter after entering

if shortCrossCount >= 3 and strategy.position_size >= 0
    strategy.entry("Short", strategy.short)
    shortCrossCount := 0  // Reset the counter after entering

// Exit Condition (When Price Returns to the Middle Band)
exitCondition = ta.crossover(src, basis) or ta.crossunder(src, basis)

if exitCondition and strategy.position_size > 0
    strategy.close("Long")
if exitCondition and strategy.position_size < 0
    strategy.close("Short")
Published by ChaoZhang on the FMZ strategy square · last modified 2024-12-11. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Triple-Bollinger-Bands-Touch-Trend-Following-Quantitative-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- BB Percentage Index Trend Fading StrategyPine Script · Trend following · 1h
- Bollinger Band Moving Average Crossover StrategyPine Script · Trend following · 1h
- Bollinger Band Trend ChaserPine Script · Trend following · 1d
- Bollinger Bands Double Standard Deviation Filtering 5 Minute Quantitative Trading StrategyPine Script · Trend following · 2h
- Bollinger Bands Precise Crossover Quantitative StrategyPine Script · Trend following · 1h