VWAP ATR Dynamic Price Action Trading System
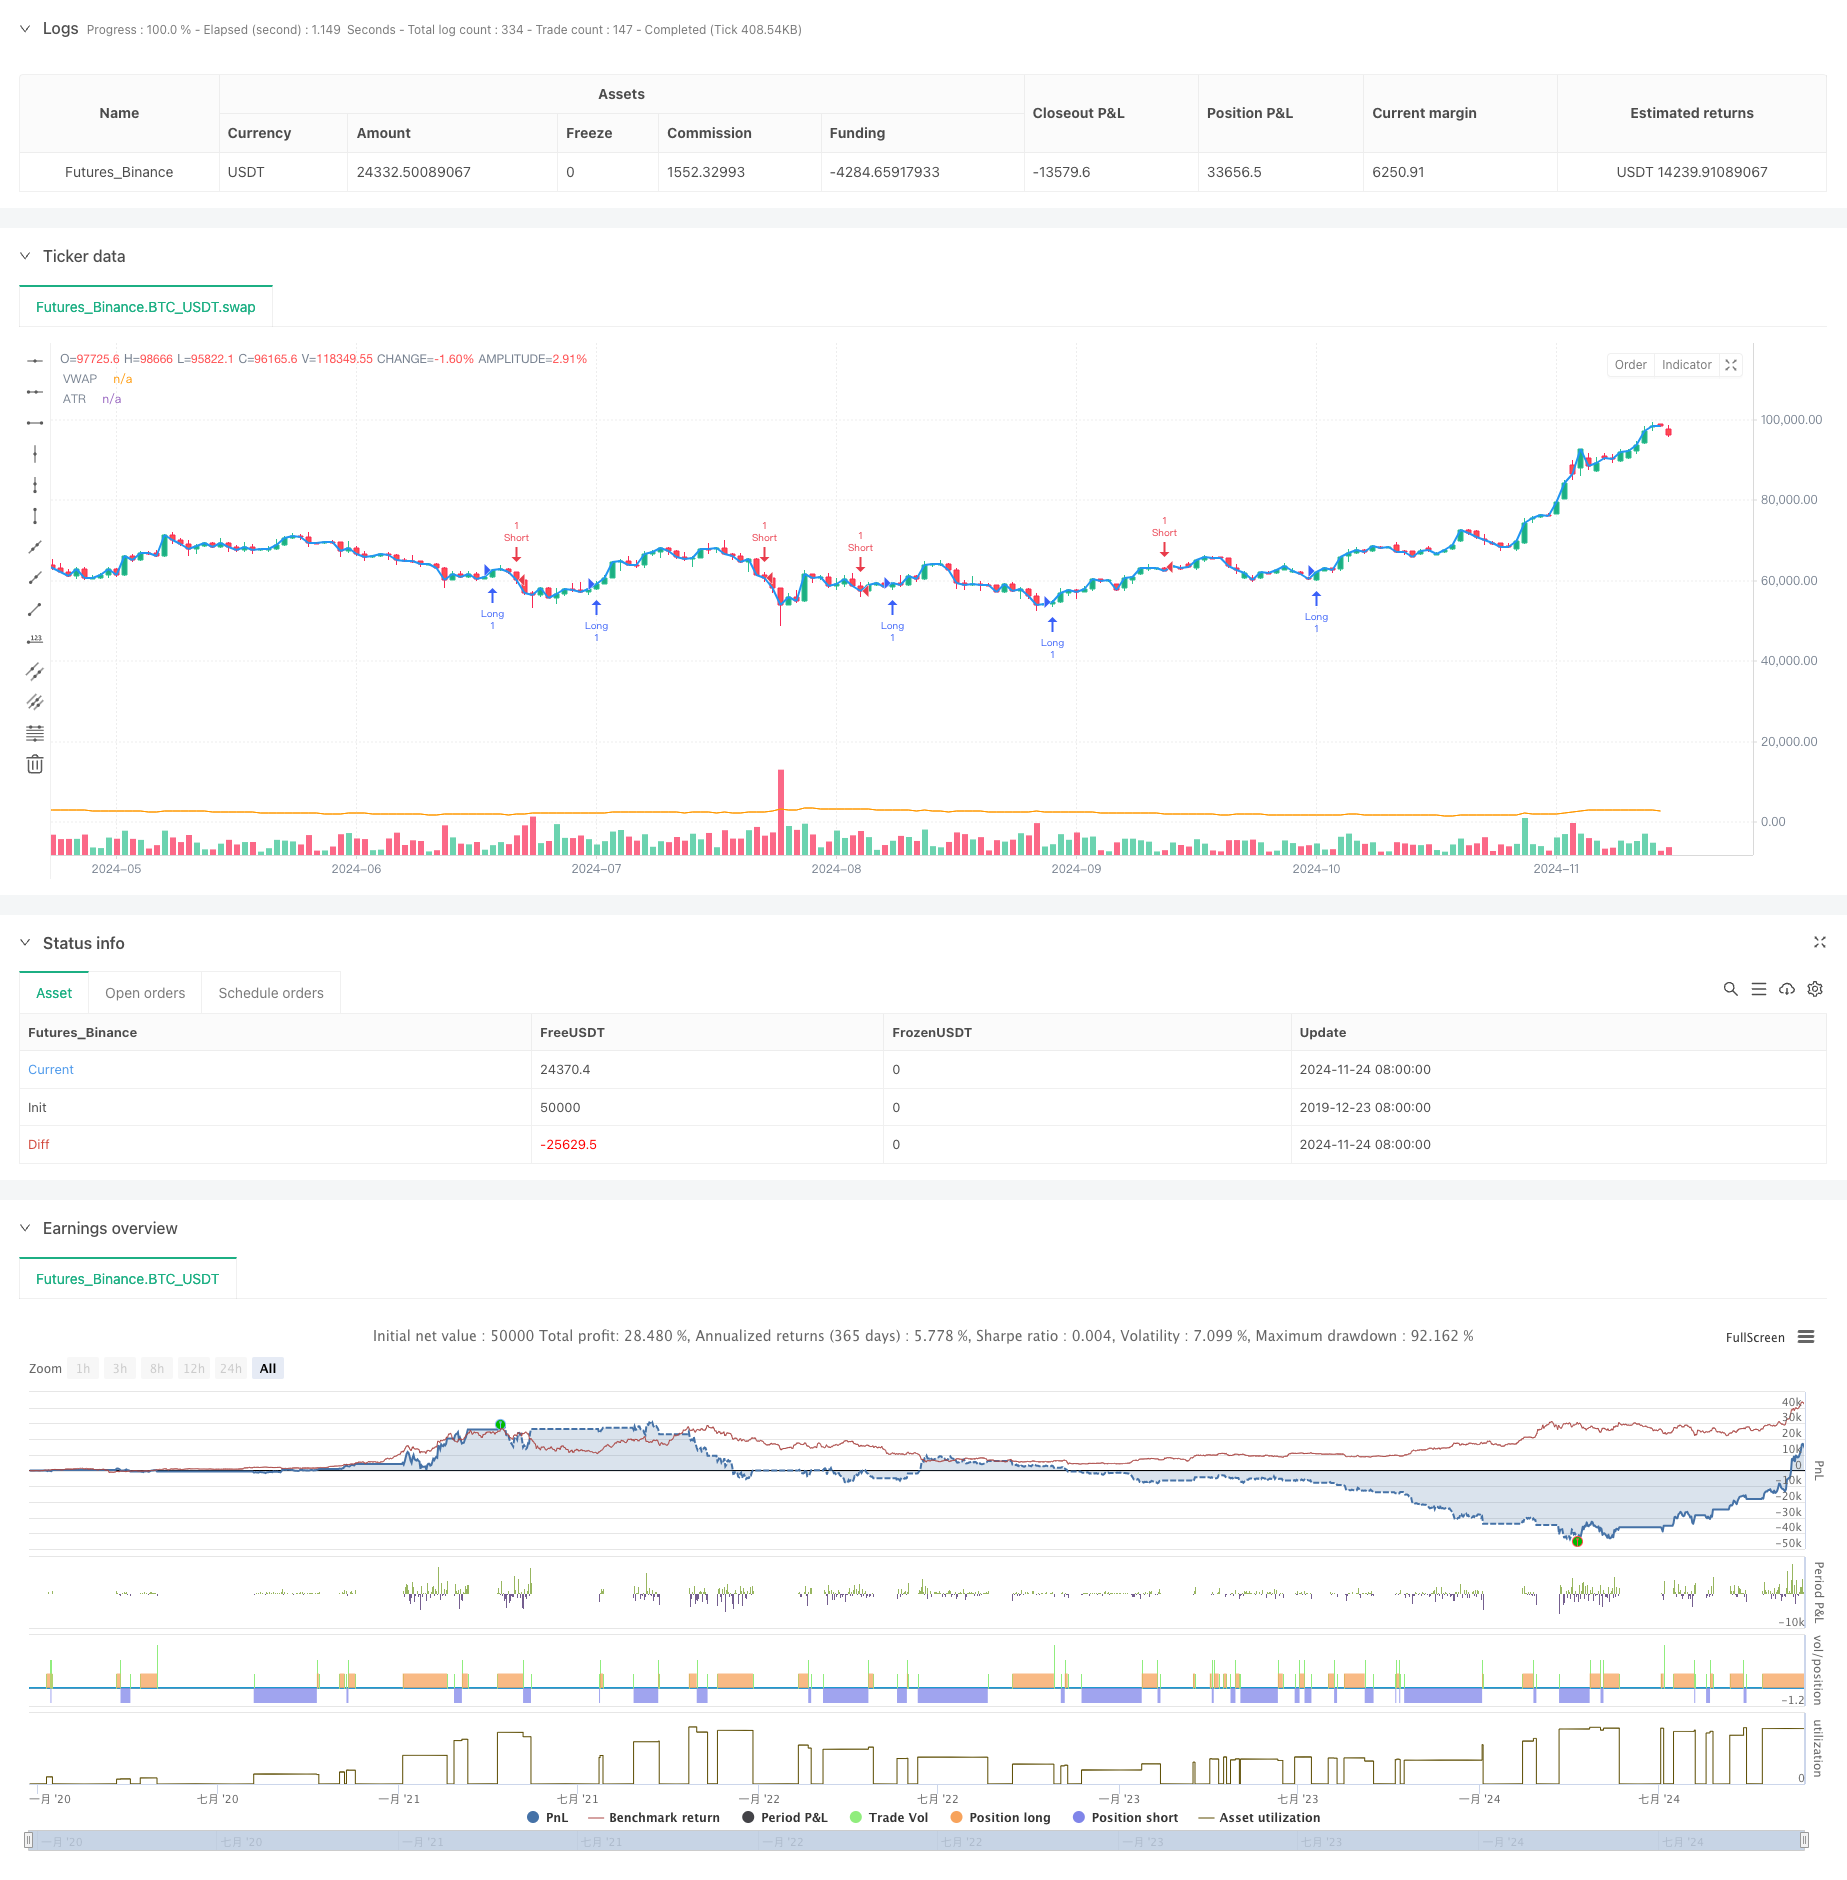
This is an intraday trading strategy that combines Volume Weighted Average Price (VWAP), Average True Range (ATR), and price action analysis. The strategy determines market trends by observing price crossovers with…
Overview
This is an intraday trading strategy that combines Volume Weighted Average Price (VWAP), Average True Range (ATR), and price action analysis. The strategy determines market trends by observing price crossovers with VWAP while using ATR to set dynamic stop-loss and profit targets. The core concept is to identify trading opportunities when price pulls back to VWAP, with risk management controlled by ATR.
Strategy Principles
The strategy is based on several core principles:
- Uses VWAP as a trend reference line, bullish above VWAP and bearish below
- Identifies entry points through price crossovers with VWAP
- Utilizes ATR for dynamic calculation of stop-loss and profit targets, providing flexible risk management
- Long entry condition: price crosses above VWAP from below
- Short entry condition: price crosses below VWAP from above
- Stop-loss set at 1x ATR, profit target at 1.5x ATR
Strategy Advantages
- Dynamic risk management: Adjusts stop-loss and profit targets using ATR, adapting to different market volatility conditions
- Trend following: Effectively captures market trends using VWAP as a reference
- Objective trading signals: Based on clear technical indicators, reducing subjective judgment
- Reasonable risk-reward ratio: Ensures good risk-reward through 1.5x ATR profit target
- High adaptability: Applicable to different markets and timeframes
Strategy Risks
- Choppy market risk: Frequent VWAP crossovers in ranging markets may generate false signals
- Slippage risk: May face significant slippage during rapid market movements
- Stop-loss range risk: 1x ATR stop-loss might be insufficient in highly volatile markets
- False breakout risk: Price-VWAP crossovers may result in false breakouts
Strategy Optimization
- Add volume filters: Implement volume confirmation mechanisms to improve signal reliability
- Optimize stop-loss settings: Dynamically adjust ATR multipliers based on market conditions
- Add trend filters: Introduce additional trend indicators to avoid frequent trading in ranging markets
- Improve entry timing: Add price pattern confirmation to enhance entry accuracy
- Implement time filters: Add trading session restrictions to avoid highly volatile market opens and closes
Summary
This is a quantitative trading strategy combining technical analysis and dynamic risk management. The combination of VWAP and ATR ensures objective trading signals while maintaining effective risk control. The strategy design aligns with modern quantitative trading requirements, offering good practicality and scalability. Through the suggested optimizations, there is room for further performance improvement.
Source Pine Script
/*backtest
start: 2019-12-23 08:00:00
end: 2024-11-25 08:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Price Action + VWAP + ATR Intraday Strategy", overlay=true)

// VWAP Calculation
vwapValue = ta.vwap(close)

// ATR Calculation (14-period)
atr = ta.atr(14)

// Price Action Setup for Bullish and Bearish Trades
bullishCondition = close > vwapValue and close[1] < vwapValue // Price above VWAP (Bullish bias) and Price action pullback to VWAP
bearishCondition = close < vwapValue and close[1] > vwapValue // Price below VWAP (Bearish bias) and Price action rally to VWAP

// Set stop loss and take profit based on ATR
atrMultiplier = 1.5
longStopLoss = low - atr
shortStopLoss = high + atr
longTakeProfit = close + (atr * atrMultiplier)
shortTakeProfit = close - (atr * atrMultiplier)

// Entry and Exit Rules

// Bullish Trade: Price pullback to VWAP and a bounce with ATR confirmation
if (bullishCondition and ta.crossover(close, vwapValue))
    strategy.entry("Long", strategy.long)
    strategy.exit("Take Profit/Stop Loss", from_entry="Long", limit=longTakeProfit, stop=longStopLoss)

// Bearish Trade: Price rally to VWAP and a rejection with ATR confirmation
if (bearishCondition and ta.crossunder(close, vwapValue))
    strategy.entry("Short", strategy.short)
    strategy.exit("Take Profit/Stop Loss", from_entry="Short", limit=shortTakeProfit, stop=shortStopLoss)

// Plot VWAP on the chart
plot(vwapValue, color=color.blue, linewidth=2, title="VWAP")

// Plot ATR on the chart for reference (Optional)
plot(atr, title="ATR", color=color.orange, linewidth=1)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-11-27. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/VWAP-ATR-Dynamic-Price-Action-Trading-System.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Multi Filter Trend Breakthrough Smart Moving Average Trading StrategyPine Script · Breakout · 1h
- Multi Timeframe VWAP and EMA Breakout Trading StrategyPine Script · Breakout · 2h
- Hybrid Trading Strategy Based on Volatility Breakout and Multiple Technical IndicatorsPine Script · Breakout · 1d
- VWAP MACD RSI Multi Factor Quantitative Trading StrategyPine Script · Breakout · 4h
- Advanced Multi Pattern Breakout Trading StrategyPine Script · Breakout · 1d
- Flexible Long Short Trading Strategy Based on Keltner ChannelsPine Script · Breakout · 1d