Strategy vault / Mean reversion
Wealth Creation Composite Strategy
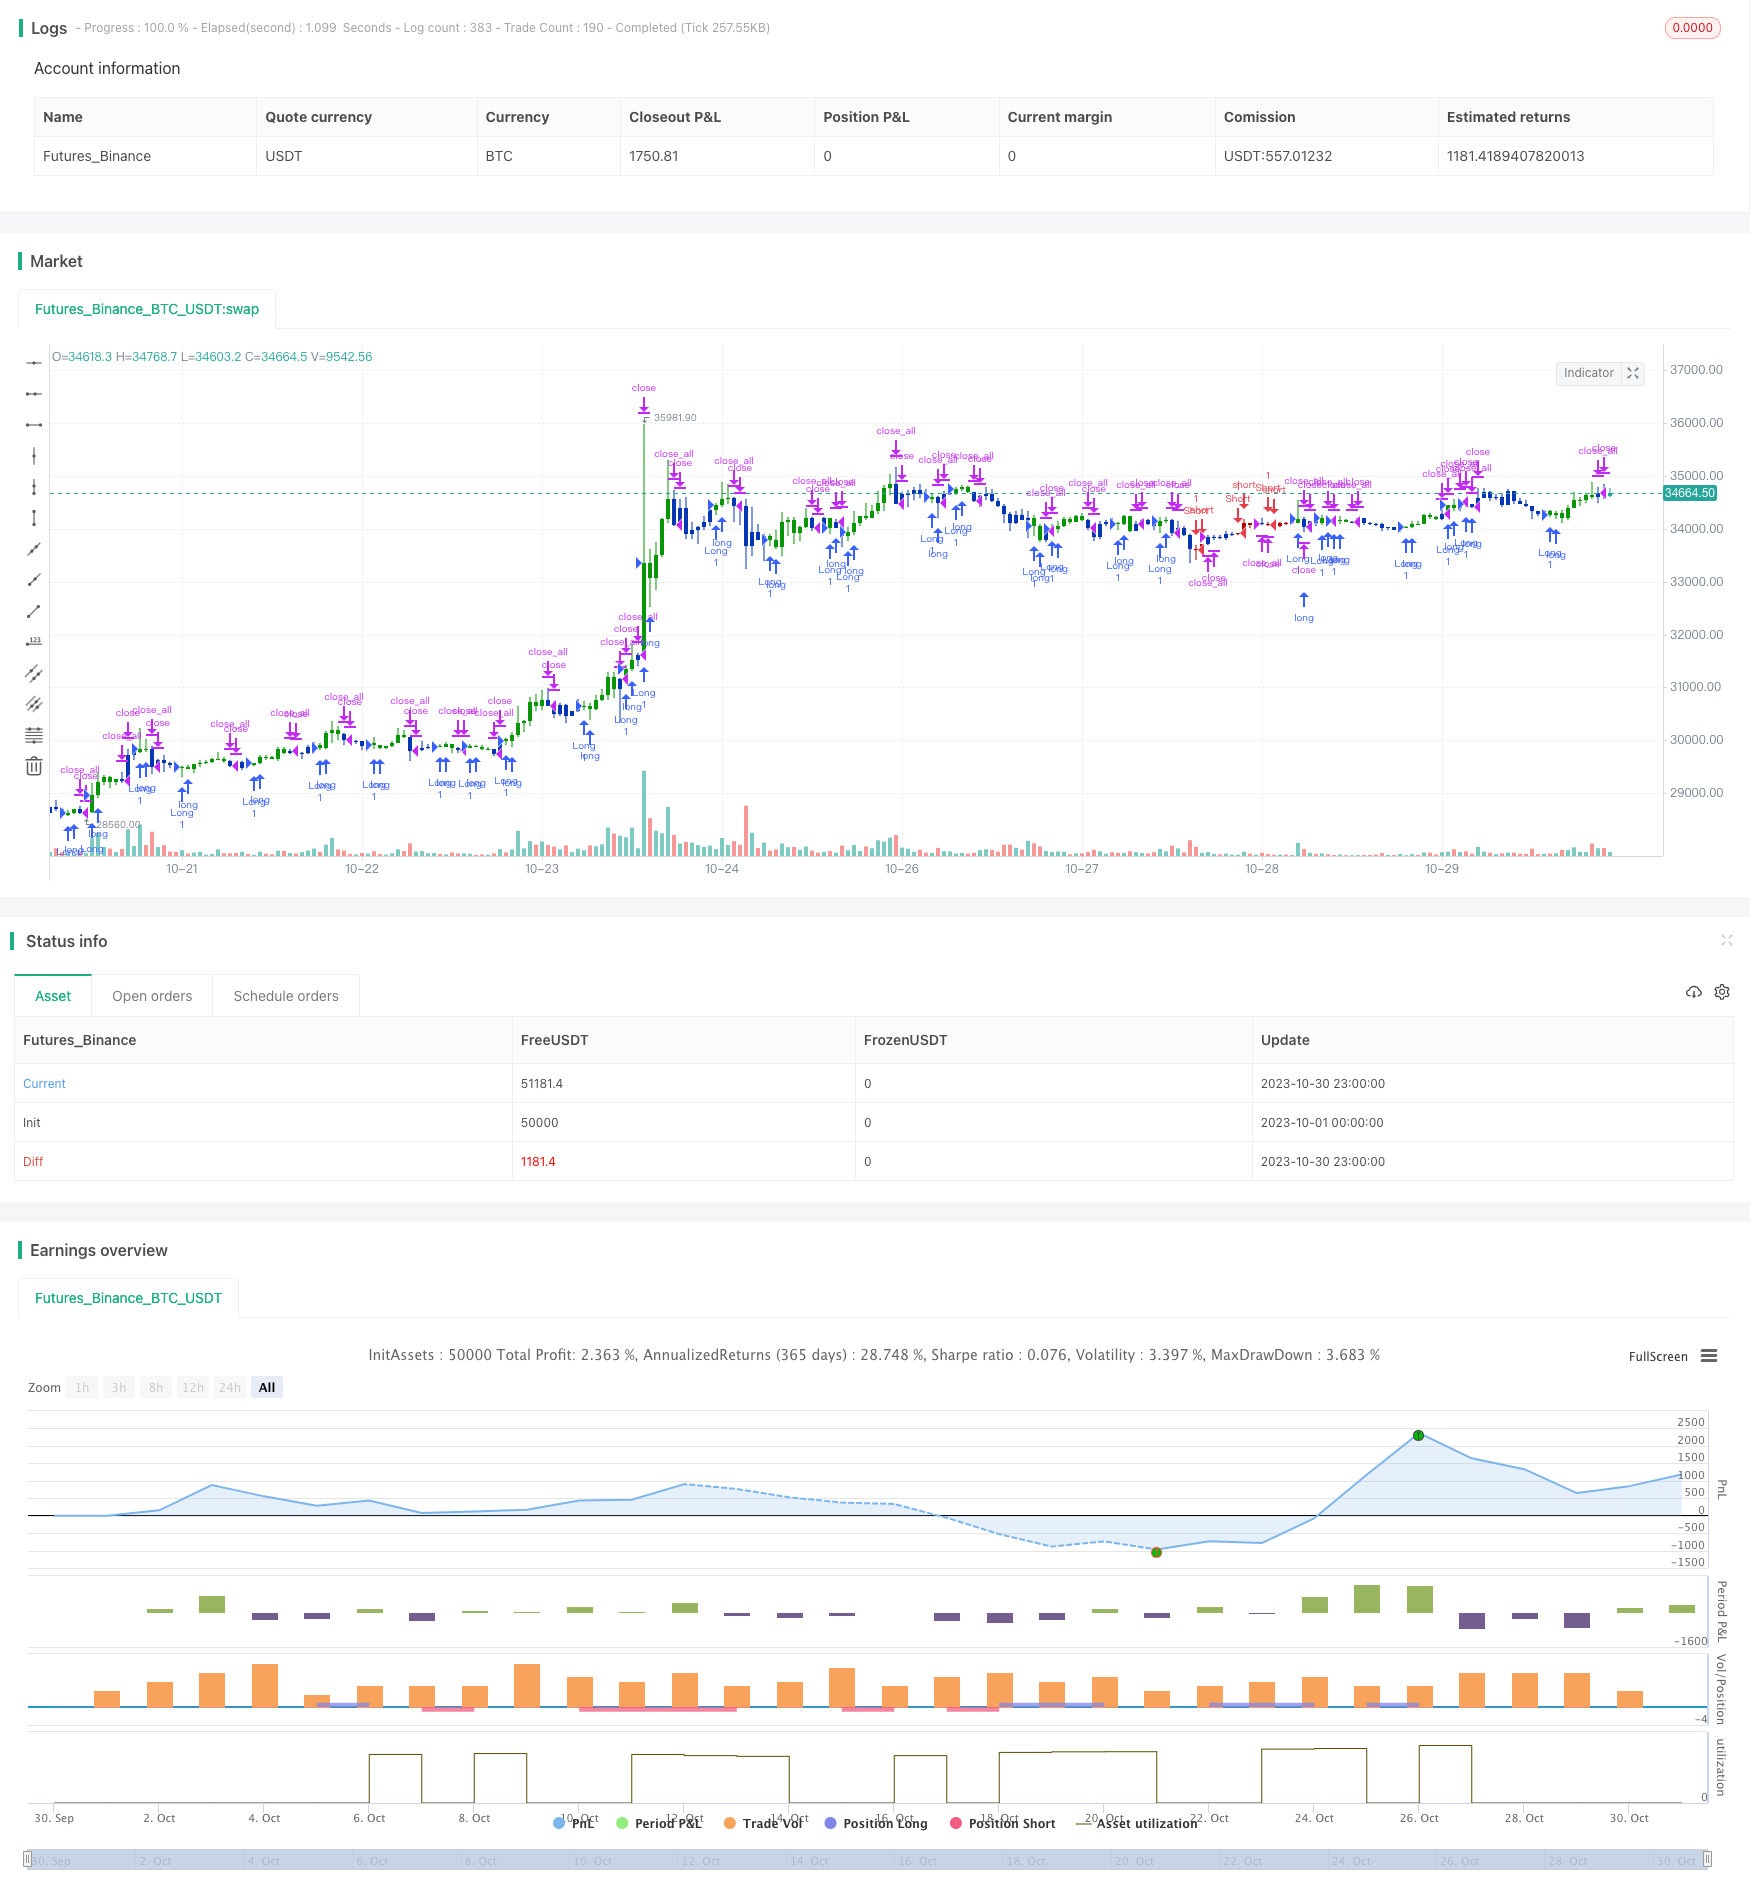
This strategy is a composite trading strategy that aims to profit in the medium to short term. It integrates the 123 Reversal strategy and Awesome Oscillator strategy to leverage the strengths of both and obtain more…
Overview
This strategy is a composite trading strategy that aims to profit in the medium to short term. It integrates the 123 Reversal strategy and Awesome Oscillator strategy to leverage the strengths of both and obtain more reliable trading signals.
Strategy Logic
The strategy consists of two parts:
123 Reversal Strategy
This part is adapted from the reversal strategy described on page 183 of the book "How I Tripled My Money in the Futures Market" by Ulf Jensen. It goes long when the close price is higher than the previous close for 2 consecutive days and the 9-day Slow Stochastic is below 50. It goes short when the close price is lower than the previous close for 2 consecutive days and the 9-day Fast Stochastic is above 50.
Awesome Oscillator Strategy
This part uses the Awesome Oscillator indicator, which compares the AO current value to the previous one. If the current AO value is higher than the previous, it indicates a good opportunity to go long and the histogram bar color is blue. If the current AO value is not higher than the previous, it indicates a good chance to go short and the bar color is red.
The combined signal is generated as follows: if the 123 Reversal and Awesome Oscillator strategies both give buy signals, adopt a long strategy; if both give sell signals, adopt a short strategy.
Advantage Analysis
The biggest advantage of this composite strategy is that it combines the strengths of two different types of strategies, improving the reliability and stability of trading signals.
Specifically, the 123 Reversal strategy is more applicable in the medium to short term and can capture reversal opportunities. The Awesome Oscillator strategy focuses more on short-term trends and is more sensitive. The two strategies complement each other, help filter out false signals, and capture better entry opportunities in different stages.
In addition, this strategy comprehensively utilizes K-line information and an oscillator indicator, taking into account both price action itself and the volume-price relationship for a more well-rounded approach.
Risk Analysis
The biggest risk of this strategy is that combining multiple strategies also compounds their individual risks.
The 123 Reversal strategy itself cannot completely avoid the risk of being stuck in a range-bound market. The Awesome Oscillator strategy is also sensitive to short-term market fluctuations. Incorrect signals from both strategies will be amplified.
In addition, parameter settings also affect strategy performance. Extensive testing and optimization is needed to find the optimum parameters.
To mitigate risks, properly size positions to limit downside on individual trades. Also set stop loss orders to prevent losing more.
Optimization Directions
The strategy can be further optimized in the following aspects:
Test and optimize parameters to find the optimal parameter combination.
Add other indicators or filters to further improve signal quality.
Optimize across different timeframes for a multi-timeframe approach.
Add dynamic stops to better control risks.
Consider actual transaction costs and define entry/exit criteria.
Consider the major trend direction to avoid countertrend trading.
Conclusion
This strategy combines the strengths of the 123 Reversal and Awesome Oscillator strategies, enhancing signal reliability while retaining flexibility and sensitivity to market changes. Further parameter optimization and strict risk control are needed for stable profits in live trading. Overall, this strategy has good potential for medium to short-term trading and is worth researching and applying.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | ---- 123 Reversal ---- |
| v_input_2 | 14 | Length |
| v_input_3 | true | KSmoothing |
| v_input_4 | 3 | DLength |
| v_input_5 | 50 | Level |
| v_input_6 | true | ---- Awesome Oscillator (AC) ---- |
| v_input_7 | 34 | Length Slow |
| v_input_8 | 5 | Length Fast |
| v_input_9 | false | Trade reverse |
Source Pine Script
/*backtest
start: 2023-10-01 00:00:00
end: 2023-10-31 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
////////////////////////////////////////////////////////////
//  Copyright by HPotter v1.0 09/08/2021
// This is combo strategies for get a cumulative signal.
//
// First strategy
// This System was created from the Book "How I Tripled My Money In The
// Futures Market" by Ulf Jensen, Page 183. This is reverse type of strategies.
// The strategy buys at market, if close price is higher than the previous close
// during 2 days and the meaning of 9-days Stochastic Slow Oscillator is lower than 50.
// The strategy sells at market, if close price is lower than the previous close price
// during 2 days and the meaning of 9-days Stochastic Fast Oscillator is higher than 50.
//
// Second strategy
//    This indicator plots the oscillator as a histogram where blue denotes
//    periods suited for buying and red . for selling. If the current value
//    of AO (Awesome Oscillator) is above previous, the period is considered
//    suited for buying and the period is marked blue. If the AO value is not
//    above previous, the period is considered suited for selling and the
//    indicator marks it as red.
//
// WARNING:
// - For purpose educate only
// - This script to change bars colors.
////////////////////////////////////////////////////////////
Reversal123(Length, KSmoothing, DLength, Level) =>
    vFast = sma(stoch(close, high, low, Length), KSmoothing)
    vSlow = sma(vFast, DLength)
    pos = 0.0
    pos := iff(close[2] < close[1] and close > close[1] and vFast < vSlow and vFast > Level, 1,
	         iff(close[2] > close[1] and close < close[1] and vFast > vSlow and vFast < Level, -1, nz(pos[1], 0)))
	pos


BWAC(nLengthSlow,nLengthFast) =>
    pos = 0.0
    xSMA1_hl2 = sma(hl2, nLengthFast)
    xSMA2_hl2 = sma(hl2, nLengthSlow)
    xSMA1_SMA2 = xSMA1_hl2 - xSMA2_hl2
    xSMA_hl2 = sma(xSMA1_SMA2, nLengthFast)
    nRes =  xSMA1_SMA2 - xSMA_hl2
    pos:= iff(nRes > nRes[1], 1,
             iff(nRes < nRes[1], -1, nz(pos[1], 0)))
    pos

strategy(title="Combo Backtest 123 Reversal & Awesome Oscillator (AC)", shorttitle="Combo", overlay = true)
line1 = input(true, "---- 123 Reversal ----")
Length = input(14, minval=1)
KSmoothing = input(1, minval=1)
DLength = input(3, minval=1)
Level = input(50, minval=1)
//-------------------------
line2 = input(true, "---- Awesome Oscillator (AC) ----")
nLengthSlow = input(34, minval=1, title="Length Slow")
nLengthFast = input(5, minval=1, title="Length Fast")
reverse = input(false, title="Trade reverse")
posReversal123 = Reversal123(Length, KSmoothing, DLength, Level)
posBWAC = BWAC(nLengthSlow,nLengthFast)
pos = iff(posReversal123 == 1 and posBWAC == 1 , 1,
	   iff(posReversal123 == -1 and posBWAC == -1, -1, 0))
possig = iff(reverse and pos == 1, -1,
          iff(reverse and pos == -1 , 1, pos))
if (possig == 1 )
    strategy.entry("Long", strategy.long)
if (possig == -1 )
    strategy.entry("Short", strategy.short)
if (possig == 0)
    strategy.close_all()
barcolor(possig == -1 ? #b50404: possig == 1 ? #079605 : #0536b3 )Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-01. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Wealth-Creation-Composite-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive Trading Strategy Combining Dynamic Trend Reversal and Stochastic IndicatorPine Script · Mean reversion · 1d
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Bollinger Bands Stochastic RSI Extreme Strategy BBSR Extreme StrategyPine Script · Mean reversion · 1h
- BuySell Strategy depends on AOStochRSIATRPine Script · Mean reversion · 30m
- Byron Serpent Cloud Quant StrategyPine Script · Mean reversion · 1h
- Dual Momentum Trend Reversal Strategy Based on RSI and Stochastic RSIPine Script · Mean reversion · 1h