Strategy vault / Trend following
Weighted Quantitative Moving Average Crossover Trading Strategy
This strategy is named Weighted Quantitative Moving Average Crossover Strategy . The basic idea is to design fast and slow lines based on price, trading volume and other indicators, and generate buy and sell signals…
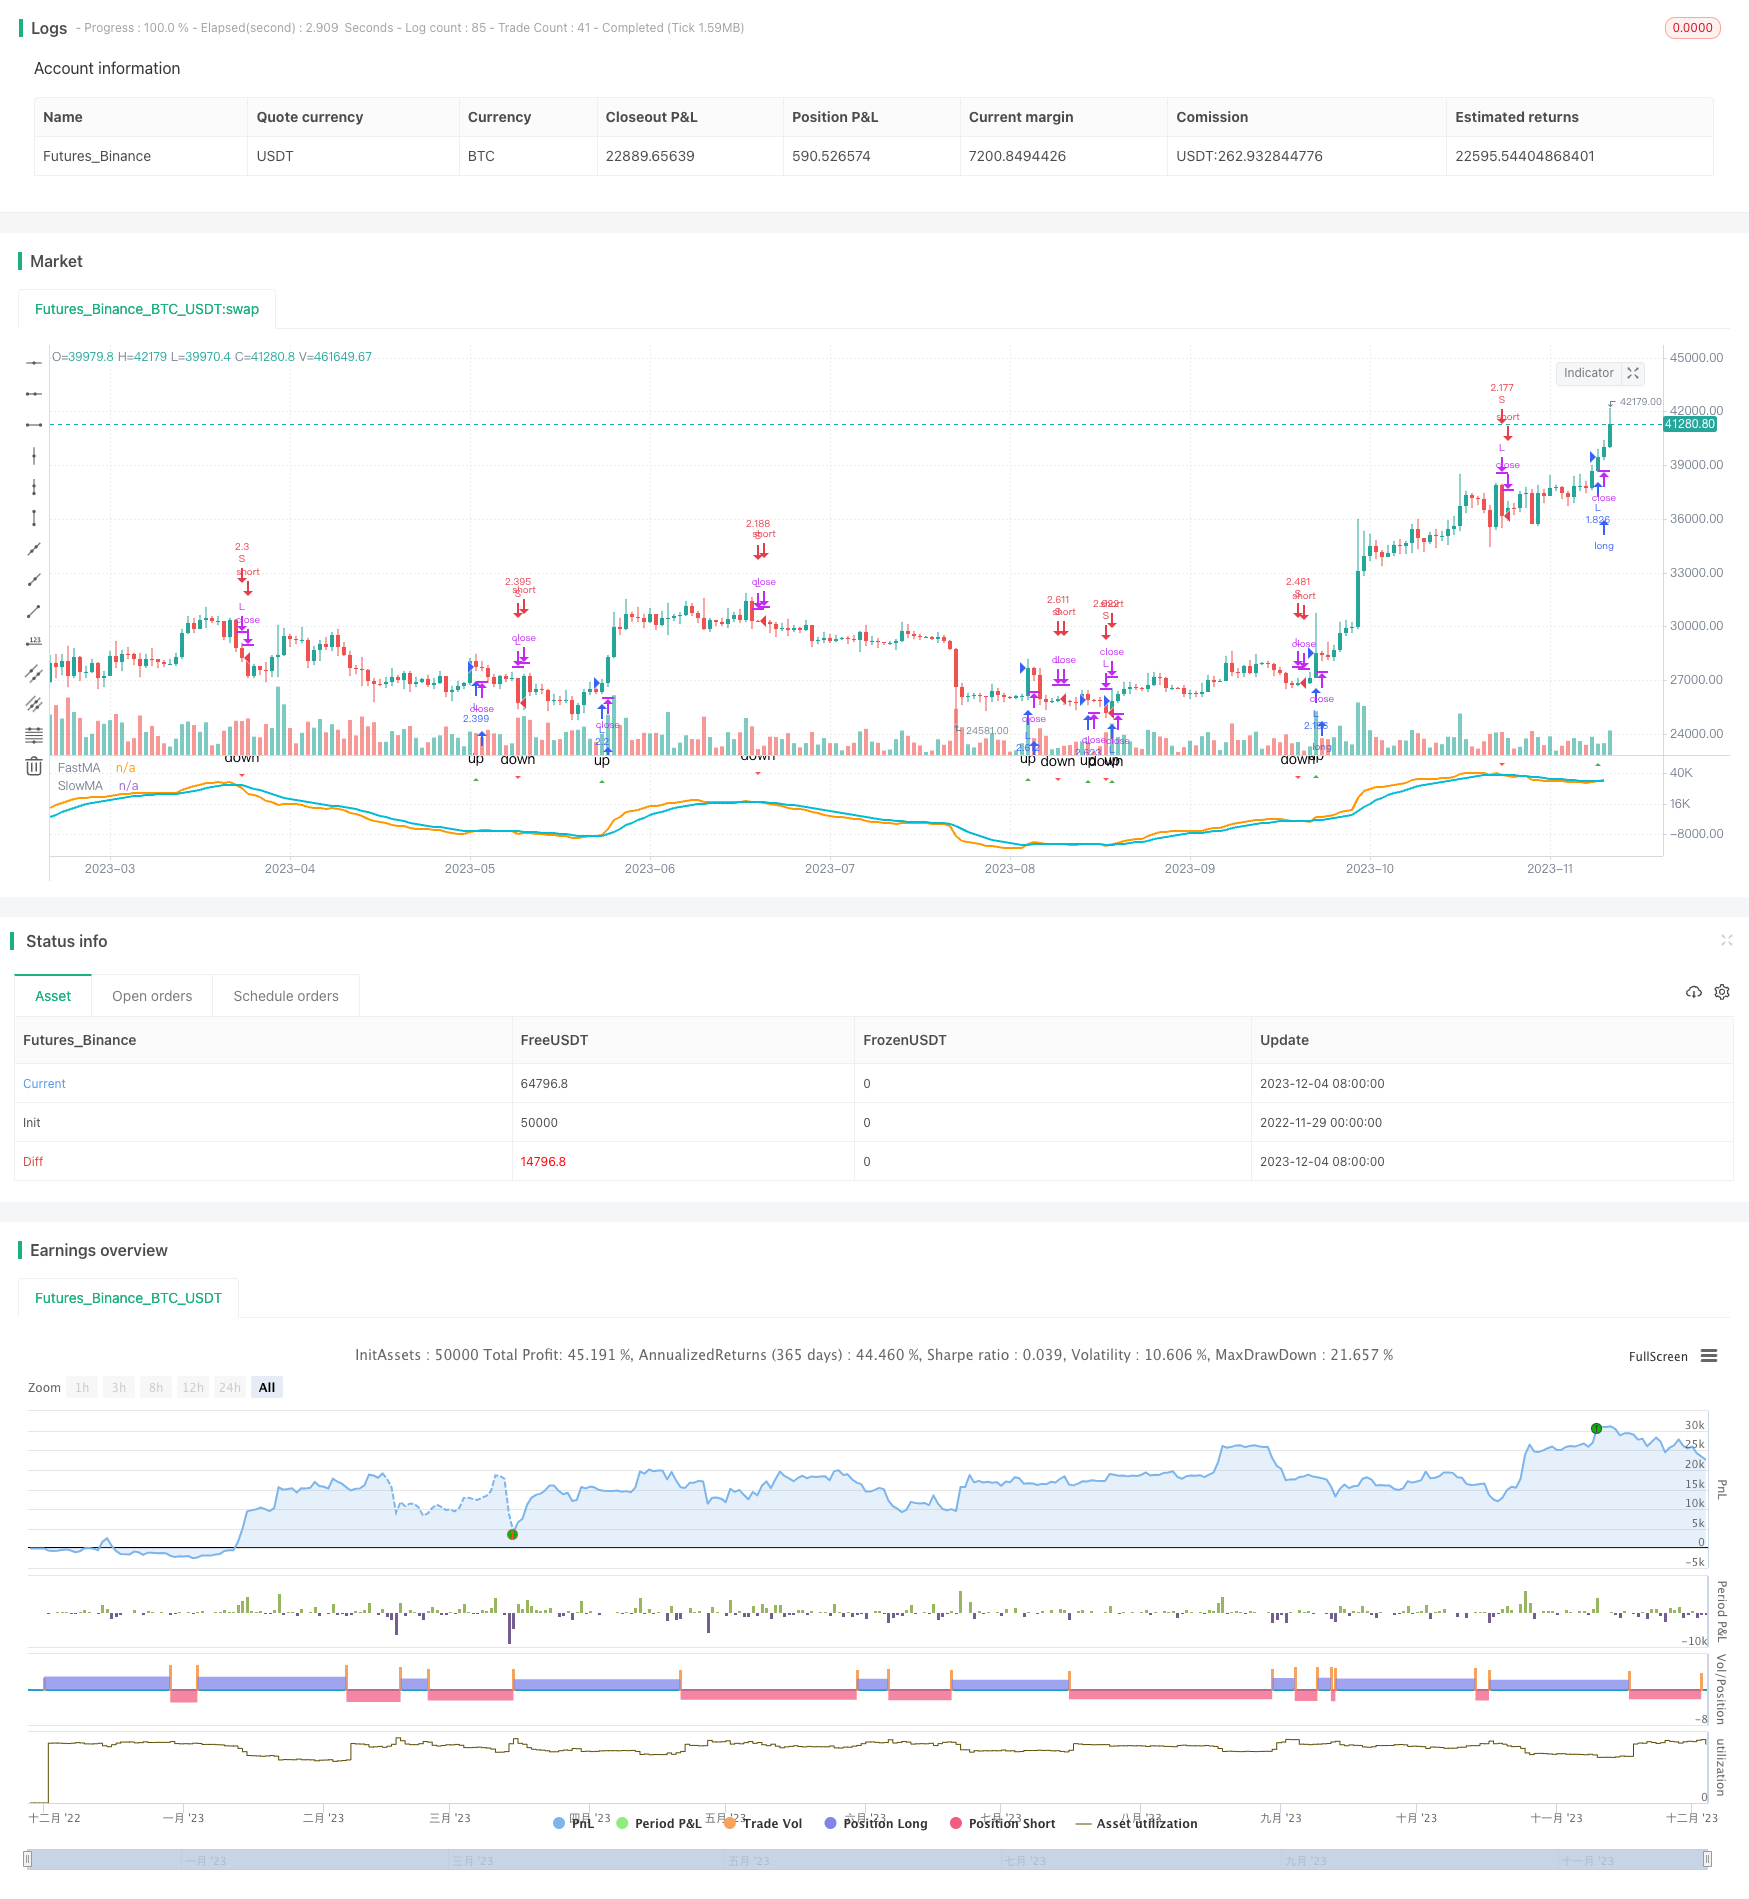
Overview
This strategy is named Weighted Quantitative Moving Average Crossover Strategy. The basic idea is to design fast and slow lines based on price, trading volume and other indicators, and generate buy and sell signals when golden cross and dead cross occur between them.
Strategy Logic
The core indicator of this strategy is Quantitative Moving Average (QMA). QMA measures the trend direction by calculating the weighted average price over a period of time. Different from regular moving average, the weights (weight = price * trading volume) of prices in QMA will decay over time. Thus, the latest prices have bigger weights which can respond to the market change more rapidly.
Specifically, this strategy builds fast QMA line with 25 days and slow QMA line with 29 days. It will generate buy signal when fast line crosses above slow line, and sell signal when fast line crosses below slow line.
Advantage Analysis
Compared with regular moving average, this strategy has the following advantages:
- Respond to the market more promptly, which enables it to capture short-term opportunities.
- Combine multiple dimensions including price and trading volume, which makes it more stable.
- Flexible parameter settings to adapt to different market environments.
Risk Analysis
This strategy also has some risks:
- High trading frequency of short-term operations, which may lead to increased transaction costs and slippages.
- Overfitting due to excessive parameter optimization.
- Indicator effect may be compromised when the trading volume is insufficient.
The above risks could be mitigated by appropriately adjusting the frequency, strictly walk forward analysis, and incorporating other indicators.
Improvement Directions
There is still room for further optimization of this strategy:
- Dynamically adjust the parameters of QMA to make it self-adaptive to market volatility.
- Filter trading opportunities with indicators like volatility and trading volume.
- Add stop loss strategies to control single loss.
Conclusion
In general, this is a stable short-term trading strategy. Compared with single price average, its indicator can better reflect the supply-demand relationship in the market. With proper parameter tuning and risk management, this strategy can operate steadily for the long run and gain sound profit.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 9 | From Month |
| v_input_2 | true | From Day |
| v_input_3 | 2018 | From Year |
| v_input_4 | true | To Month |
| v_input_5 | true | To Day |
| v_input_6 | 9999 | To Year |
| v_input_7 | 25 | FastMA |
| v_input_8 | 29 | SlowMA |
| v_input_9 | 9 | Smoothing_period |
Source Pine Script
/*backtest
start: 2022-11-29 00:00:00
end: 2023-12-05 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
strategy("Brad VWMACD Strategy 2233", overlay=false, max_bars_back=500,default_qty_type=strategy.percent_of_equity,commission_type=strategy.commission.percent, commission_value=0.18, default_qty_value=100)

// === INPUT BACKTEST RANGE ===
FromMonth = input(defval = 9, title = "From Month", minval = 1, maxval = 12)
FromDay   = input(defval = 1, title = "From Day", minval = 1, maxval = 31)
FromYear  = input(defval = 2018, title = "From Year", minval = 2017)
ToMonth   = input(defval = 1, title = "To Month", minval = 1, maxval = 12)
ToDay     = input(defval = 1, title = "To Day", minval = 1, maxval = 31)
ToYear    = input(defval = 9999, title = "To Year", minval = 2017)

// === FUNCTION EXAMPLE ===
start     = timestamp(FromYear, FromMonth, FromDay, 00, 00)  // backtest start window
finish    = timestamp(ToYear, ToMonth, ToDay, 23, 59)        // backtest finish window
window()  => time >= start and time <= finish ? true : false // create function "within window of time"

// === INPUT SMA ===
//fastMA    = input(defval = 16, type = integer, title = "FastMA", minval = 1 )
//slowMA    = input(defval = 23, type = integer, title = "SlowMA", minval = 1)

fastMA    = input(defval = 25, title = "FastMA", minval = 1 )
slowMA    = input(defval = 29,  title = "SlowMA", minval = 1)

Long_period = slowMA
Short_period = fastMA
Smoothing_period = input(9, minval=1)
xLongMAVolPrice = ema(volume * close, Long_period)
xLongMAVol = ema(volume, Long_period)
xResLong = (xLongMAVolPrice * Long_period) / (xLongMAVol * Long_period)
xShortMAVolPrice = ema(volume * close, Short_period)
xShortMAVol = ema(volume, Short_period)
xResShort = (xShortMAVolPrice * Short_period) / (xShortMAVol * Short_period)
xVMACD = xResShort - xResLong
xVMACDSignal = ema(xVMACD, Smoothing_period)
nRes = xVMACD - xVMACDSignal
//plot(nRes*20+slowMA, color=blue, style = line )
//plot(3000, color=red, style = line )


// === SERIES SETUP ===

buy  = crossover( xVMACD,xVMACDSignal)     // buy when fastMA crosses over slowMA
sell = crossunder( xVMACD,xVMACDSignal)  // sell when fastMA crosses under slowMA


// === SERIES SETUP ===

//buy  = crossover(vwma(close, fastMA),7+vwma(close, slowMA))     // buy when fastMA crosses over slowMA
//sell = crossunder(vwma(close, fastMA),vwma(close, slowMA)-7)    // sell when fastMA crosses under slowMA

// === EXECUTION ===
strategy.entry("L", strategy.long, when = window() and buy)  // buy long when "within window of time" AND crossover
strategy.close("L", when = window() and sell)                // sell long when "within window of time" AND crossunder

// === EXECUTION ===
strategy.entry("S", strategy.short, when = window() and sell)  // buy long when "within window of time" AND crossover
strategy.close("S", when = window() and buy)                // sell long when "within window of time" AND crossunder

plotshape(window() and buy, style=shape.triangleup, color=green, text="up")
plotshape(window() and sell, style=shape.triangledown, color=red, text="down")
plot(xVMACD*100, title = 'FastMA', color = orange, linewidth = 2, style = line)  // plot FastMA
plot(xVMACDSignal*100, title = 'SlowMA', color = aqua, linewidth = 2, style = line)    // plot SlowMA
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-06. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Weighted-Quantitative-Moving-Average-Crossover-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Bollinger Band Moving Average Crossover StrategyPine Script · Trend following · 1h
- Bollinger Bands and EMA Trend Following StrategyPine Script · Trend following · 1h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Candlestick Pattern Trend Filter StrategyPine Script · Trend following · 1d