Strategy vault / Mean reversion
Welcome to the BEARMARKET 30 MIN
Hello everyone, This is my first concept of bear market movmment nearfuture Bot is optimalised for --- BINANCE:BTCUSDT The core of this bot is using ATR trend to define trend, also uses rsi value to open new…
Hello everyone,
This is my first concept of bear market movmment nearfuture Bot is optimalised for --->>> BINANCE:BTCUSDT
The core of this bot is using ATR trend to define trend, also uses rsi value to open new swingshorts ( RSI-VWAP ) or find a perfect close place ( RSI OVERSOLD)
This bot is only short bot for 100% maximalize profit from every move down from Bitcoin I recommend using 1-3x leverage for this bot, becouse of the high amount of wrong trades or closes with minimal profit Sl is arount : 6% (Just for best perforrming in all backtesting time period)
So, short codintion is open by :
Both ADX and S_ATR only if rsi is not oversold a) ADX Is one of the most powerful and accurate trend indicators. ADX measures how strong a trend is, and can give valuable information on whether there is a potential trading opportunity. b) The average true range (ATR) is a technical analysis indicator, introduced by market technician J. Welles Wilder Jr. in his book New Concepts in Technical Trading Systems, that measures market volatility by decomposing the entire range of an asset price for that period
RSI VWAP -VWAP is calculated by adding up the dollars traded for every transaction (price multiplied by the number of shares traded) and then dividing by the total shares traded. rsi vwwap open new position only if there is no bullish signal from Cloud , Adx , ATR indicators
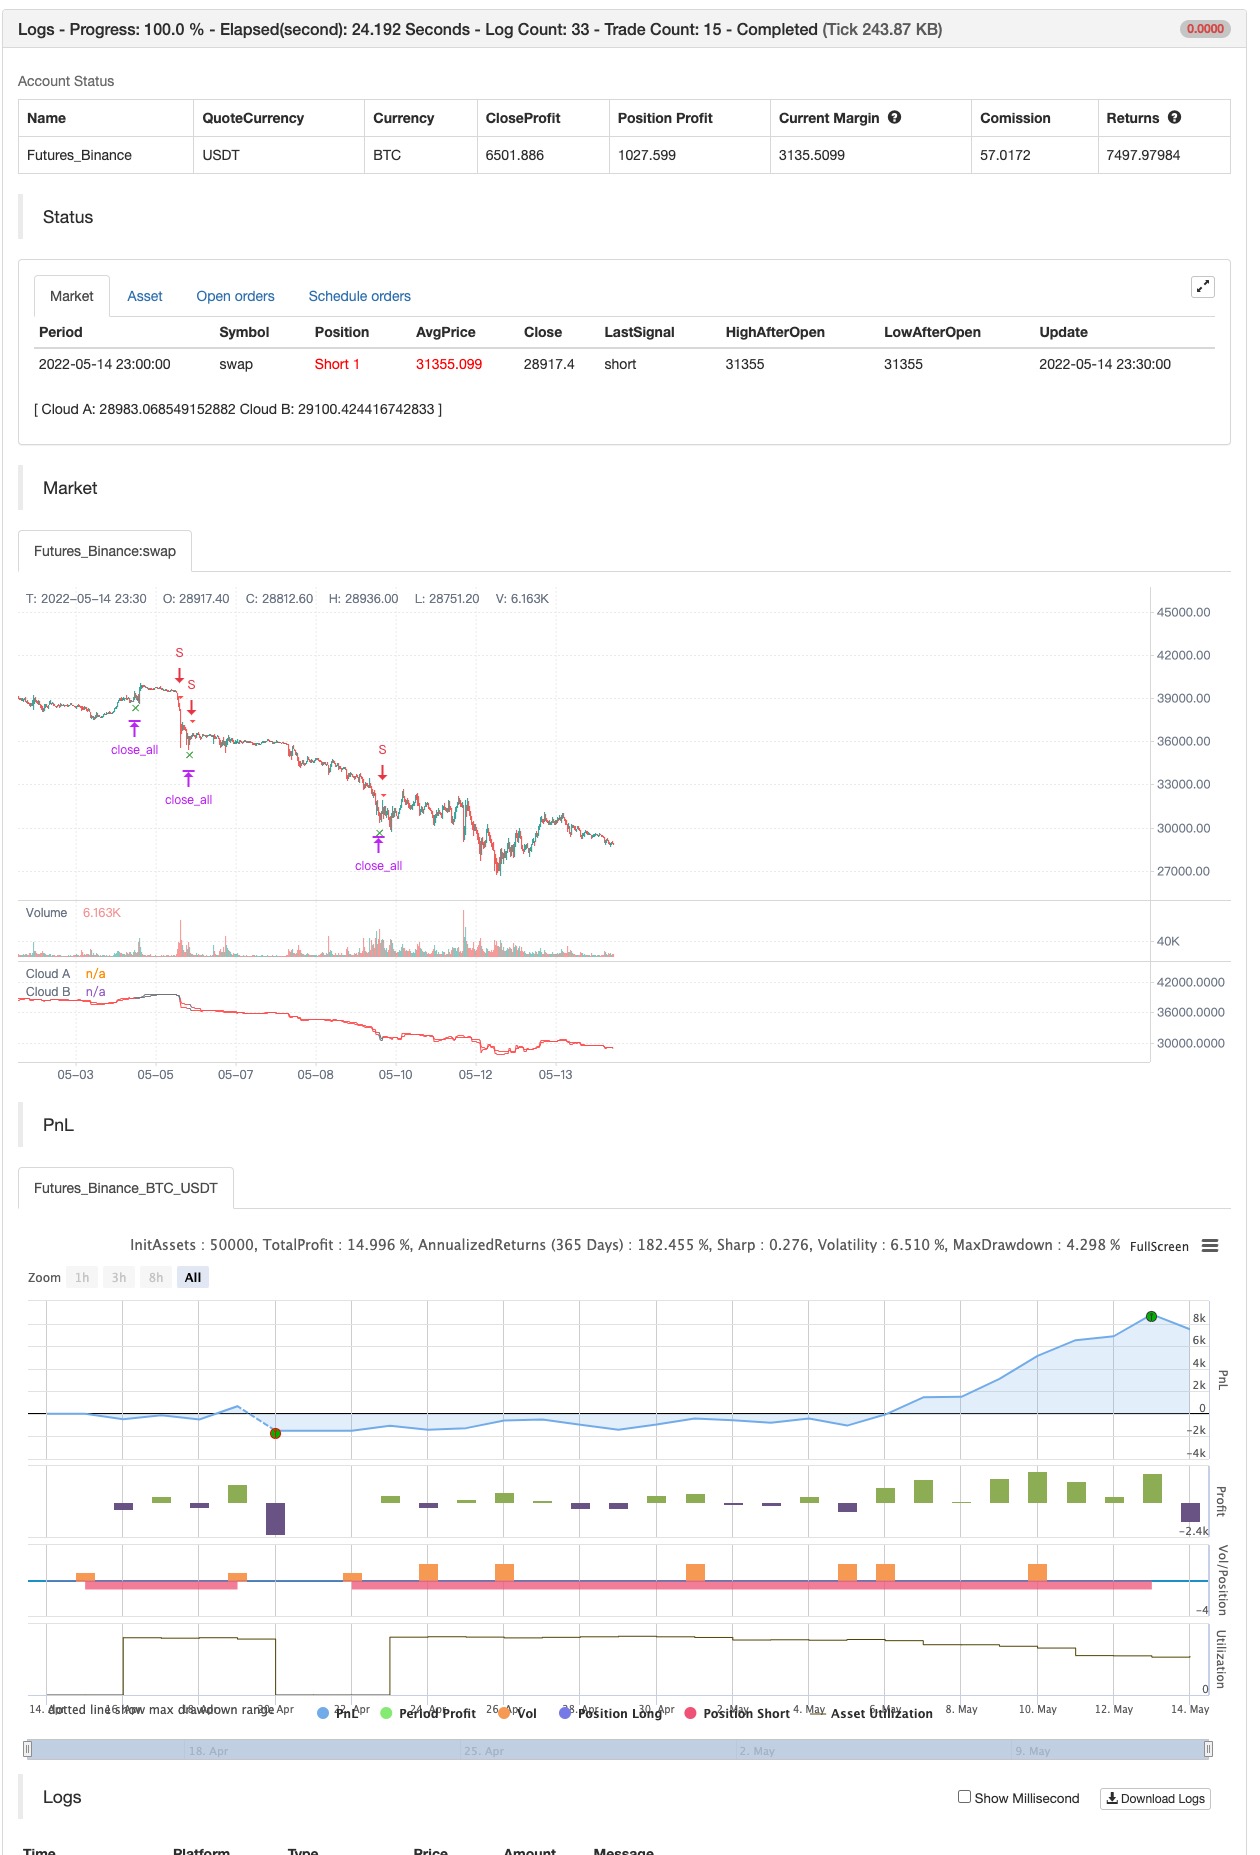
backtest
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 2 | PP period |
| v_input_2 | 10 | ATR Factor |
| v_input_3 | 14 | ATR Period |
| v_input_4 | 2 | Cloud Length |
| v_input_10 | 22 | Rsi vwap lenght |
| v_input_11 | 6 | stop loss |
| v_input_12 | 100 | qty percent |
| v_input_5 | 0 | (?ADX_options)ADX_options OPTION: CLASSIC | MASANAKAMURA |
| v_input_6 | 17 | ADX_options LENGTH |
| v_input_7 | 14 | ADX_options THRESHOLD |
| v_input_8 | 51 | (?Relative Strenght Indeks)RSI lenght |
| v_input_9_high | 0 | RSI Source: high | close | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
Source Pine Script
/*backtest
start: 2022-04-15 00:00:00
end: 2022-05-14 23:59:00
period: 30m
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/
// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © wielkieef
//@version=4
src = close
//strategy("Welcome to the BEARMARKET [30MIN]", overlay=true, initial_capital = 10000, pyramiding = 1, currency = "USD", calc_on_order_fills = false, calc_on_every_tick = false, default_qty_type = strategy.fixed, default_qty_value = 1, commission_value = 0.04)
//Inputs -----------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------
prd = input(2, title="PP period")
Factor = input(10, title = "ATR Factor")
Pd = input(14, title = "ATR Period")
len = input(2, title="Cloud Length")
ADX_options = input("CLASSIC", title="ADX OPTION", options = ["CLASSIC", "MASANAKAMURA"], group = "ADX")
ADX_len = input(17, title="ADX LENGTH", type = input.integer, minval = 1, group = "ADX")
th = input(14, title="ADX THRESHOLD", type = input.float, minval = 0, step = 0.5, group = "ADX")
len_3 = input(51, title="RSI lenght", group = "Relative Strenght Indeks")
src_3 = input(high, title="RSI Source", group = "Relative Strenght Indeks")
RSI_VWAP_length = input(22, title="Rsi vwap lenght")
//INDICATORS -----------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------
//Cloud -----------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------
PI = 2 * asin(1)
hilbertTransform(src) =>
0.0962 * src + 0.5769 * nz(src[2]) - 0.5769 * nz(src[4]) - 0.0962 * nz(src[6])
computeComponent(src, mesaPeriodMult) =>
hilbertTransform(src) * mesaPeriodMult
computeAlpha(src, fastLimit, slowLimit) =>
mesaPeriod = 0.0
mesaPeriodMult = 0.075 * nz(mesaPeriod[1]) + 0.54
smooth = 0.0
smooth := (4 * src + 3 * nz(src[1]) + 2 * nz(src[2]) + nz(src[3])) / 10
detrender = 0.0
detrender := computeComponent(smooth, mesaPeriodMult)
I1 = nz(detrender[3])
Q1 = computeComponent(detrender, mesaPeriodMult)
jI = computeComponent(I1, mesaPeriodMult)
jQ = computeComponent(Q1, mesaPeriodMult)
I2 = 0.0
Q2 = 0.0
I2 := I1 - jQ
Q2 := Q1 + jI
I2 := 0.2 * I2 + 0.8 * nz(I2[1])
Q2 := 0.2 * Q2 + 0.8 * nz(Q2[1])
Re = I2 * nz(I2[1]) + Q2 * nz(Q2[1])
Im = I2 * nz(Q2[1]) - Q2 * nz(I2[1])
Re := 0.2 * Re + 0.8 * nz(Re[1])
Im := 0.2 * Im + 0.8 * nz(Im[1])
if Re != 0 and Im != 0
mesaPeriod := 2 * PI / atan(Im / Re)
if mesaPeriod > 1.5 * nz(mesaPeriod[1])
mesaPeriod := 1.5 * nz(mesaPeriod[1])
if mesaPeriod < 0.67 * nz(mesaPeriod[1])
mesaPeriod := 0.67 * nz(mesaPeriod[1])
if mesaPeriod < 6
mesaPeriod := 6
if mesaPeriod > 50
mesaPeriod := 50
mesaPeriod := 0.2 * mesaPeriod + 0.8 * nz(mesaPeriod[1])
phase = 0.0
if I1 != 0
phase := (180 / PI) * atan(Q1 / I1)
deltaPhase = nz(phase[1]) - phase
if deltaPhase < 1
deltaPhase := 1
alpha = fastLimit / deltaPhase
if alpha < slowLimit
alpha := slowLimit
[alpha,alpha/2.0]
er = abs(change(src,len)) / sum(abs(change(src)),len)
[a,b] = computeAlpha(src, er, er*0.1)
mama = 0.0
mama := a * src + (1 - a) * nz(mama[1])
fama = 0.0
fama := b * mama + (1 - b) * nz(fama[1])
alpha = pow((er * (b - a)) + a, 2)
kama = 0.0
kama := alpha * src + (1 - alpha) * nz(kama[1])
L_cloud = kama > kama[1]
S_cloud = kama < kama[1]
CLOUD_COLOR = L_cloud ? color.lime : S_cloud ? color.red : na
// ATR -------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------
float ph = pivothigh(prd, prd)
float pl = pivotlow(prd, prd)
var float center = na
float lastpp = ph ? ph : pl ? pl : na
if lastpp
if na(center)
center := lastpp
else
center := (center * 2 + lastpp) / 3
Up = center - (Factor * atr(Pd))
Dn = center + (Factor * atr(Pd))
float TUp = na
float TDown = na
Trend = 0
TUp := close[1] > TUp[1] ? max(Up, TUp[1]) : Up
TDown := close[1] < TDown[1] ? min(Dn, TDown[1]) : Dn
Trend := close > TDown[1] ? 1: close < TUp[1]? -1: nz(Trend[1], 1)
Trailingsl = Trend == 1 ? TUp : TDown
bsignal = Trend == 1 and Trend[1] == -1
ssignal = Trend == -1 and Trend[1] == 1
L_ATR = Trend == 1
S_ATR = Trend == -1
//RSI------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------
up_3 = rma(max(change(src_3), 0), len_3)
down_3 = rma(-min(change(src_3), 0), len_3)
rsi_3 = down_3 == 0 ? 100 : up_3 == 0 ? 0 : 100 - (100 / (1 + up_3 / down_3))
Ob_rsi = (rsi_3 >= 70)
Os_rsi = (rsi_3 <= 30)
RSI_VWAP = rsi(vwap(close), RSI_VWAP_length)
RSI_VWAP_overSold = 13
RSI_VWAP_overBought = 68
L_VAP = (crossover(RSI_VWAP, RSI_VWAP_overSold))
S_VAP = (crossunder(RSI_VWAP, RSI_VWAP_overBought))
//ADX-------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------
calcADX(_len) =>
up = change(high)
down = -change(low)
plusDM = na(up) ? na : (up > down and up > 0 ? up : 0)
minusDM = na(down) ? na : (down > up and down > 0 ? down : 0)
truerange = rma(tr, _len)
_plus = fixnan(100 * rma(plusDM, _len) / truerange)
_minus = fixnan(100 * rma(minusDM, _len) / truerange)
sum = _plus + _minus
_adx = 100 * rma(abs(_plus - _minus) / (sum == 0 ? 1 : sum), _len)
[_plus,_minus,_adx]
calcADX_Masanakamura(_len) =>
SmoothedTrueRange = 0.0
SmoothedDirectionalMovementPlus = 0.0
SmoothedDirectionalMovementMinus = 0.0
TrueRange = max(max(high - low, abs(high - nz(close[1]))), abs(low - nz(close[1])))
DirectionalMovementPlus = high - nz(high[1]) > nz(low[1]) - low ? max(high - nz(high[1]), 0) : 0
DirectionalMovementMinus = nz(low[1]) - low > high - nz(high[1]) ? max(nz(low[1]) - low, 0) : 0
SmoothedTrueRange := nz(SmoothedTrueRange[1]) - (nz(SmoothedTrueRange[1]) /_len) + TrueRange
SmoothedDirectionalMovementPlus := nz(SmoothedDirectionalMovementPlus[1]) - (nz(SmoothedDirectionalMovementPlus[1]) / _len) + DirectionalMovementPlus
SmoothedDirectionalMovementMinus := nz(SmoothedDirectionalMovementMinus[1]) - (nz(SmoothedDirectionalMovementMinus[1]) / _len) + DirectionalMovementMinus
DIP = SmoothedDirectionalMovementPlus / SmoothedTrueRange * 100
DIM = SmoothedDirectionalMovementMinus / SmoothedTrueRange * 100
DX = abs(DIP-DIM) / (DIP+DIM)*100
adx = sma(DX, _len)
[DIP,DIM,adx]
[DIPlusC,DIMinusC,ADXC] = calcADX(ADX_len)
[DIPlusM,DIMinusM,ADXM] = calcADX_Masanakamura(ADX_len)
DIPlus = ADX_options == "CLASSIC" ? DIPlusC : DIPlusM
DIMinus = ADX_options == "CLASSIC" ? DIMinusC : DIMinusM
ADX = ADX_options == "CLASSIC" ? ADXC : ADXM
L_adx = DIPlus > DIMinus and ADX > th
S_adx = DIPlus < DIMinus and ADX > th
// Strategy logic ------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------
var bool longCond = na, var bool shortCond = na
var int CondIni_long = 0, var int CondIni_short = 0
var bool _Final_longCondition = na, var bool _Final_shortCondition = na
var float last_open_longCondition = na, var float last_open_shortCondition = na
var int last_longCondition = na, var int last_shortCondition = na
var int last_Final_longCondition = na, var int last_Final_shortCondition = na
var int nLongs = na, var int nShorts = na
Short_condition = S_ATR and S_adx and not Os_rsi or S_VAP and not Os_rsi and L_cloud and L_ATR and L_adx
Short_close = L_ATR or Os_rsi or L_VAP
longCond := Short_close
shortCond := Short_condition
CondIni_long := longCond[1] ? 1 : shortCond[1] ? -1 : nz(CondIni_long[1] )
CondIni_short := longCond[1] ? 1 : shortCond[1] ? -1 : nz(CondIni_short[1] )
longCondition = (longCond[1] and nz(CondIni_long[1]) == -1 )
shortCondition = (shortCond[1] and nz(CondIni_short[1]) == 1 )
var float sum_long = 0.0, var float sum_short = 0.0
var float Position_Price = 0.0
var bool Final_long_BB = na, var bool Final_short_BB = na
var int last_long_BB = na, var int last_short_BB = na
last_open_longCondition := longCondition or Final_long_BB[1] ? close[1] : nz(last_open_longCondition[1] )
last_open_shortCondition := shortCondition or Final_short_BB[1] ? close[1] : nz(last_open_shortCondition[1] )
last_longCondition := longCondition or Final_long_BB[1] ? time : nz(last_longCondition[1] )
last_shortCondition := shortCondition or Final_short_BB[1] ? time : nz(last_shortCondition[1] )
in_longCondition = last_longCondition > last_shortCondition
in_shortCondition = last_shortCondition > last_longCondition
last_Final_longCondition := longCondition ? time : nz(last_Final_longCondition[1] )
last_Final_shortCondition := shortCondition ? time : nz(last_Final_shortCondition[1] )
nLongs := nz(nLongs[1] )
nShorts := nz(nShorts[1] )
if longCondition or Final_long_BB
nLongs := nLongs + 1
nShorts := 0
sum_long := nz(last_open_longCondition) + nz(sum_long[1])
sum_short := 0.0
if shortCondition or Final_short_BB
nLongs := 0
nShorts := nShorts + 1
sum_short := nz(last_open_shortCondition)+ nz(sum_short[1])
sum_long := 0.0
Position_Price := nz(Position_Price[1])
Position_Price := longCondition or Final_long_BB ? sum_long/nLongs : shortCondition or Final_short_BB ? sum_short/nShorts : na
colors = (in_longCondition ? color.gray : in_shortCondition ? color.red : color.orange)
//barcolor (color = colors)
mama_p = plot(mama, title="Cloud A", color=colors )
fama_p = plot(fama, title="Cloud B", color=colors )
fill (mama_p,fama_p, color=colors )
plotshape(longCondition, title="Long", style=shape.xcross, location=location.belowbar, color=color.green, size=size.small , transp = 0 )
plotshape(shortCondition, title="Short", style=shape.triangledown, location=location.abovebar, color=color.red, size=size.small , transp = 0 )
if Short_condition
strategy.entry("S", strategy.short)
per(pcnt) =>
strategy.position_size != 0 ? round(pcnt / 100 * strategy.position_avg_price / syminfo.mintick) : float(na)
stoploss=input(title=" stop loss", defval=6, minval=0.01)
los = per(stoploss)
q=input(title=" qty percent", defval=100, minval=1)
strategy.exit("SL", qty_percent = q,loss = los)
strategy.close_all(when = Short_close)
//By wielkieefPublished by ChaoZhang on the FMZ strategy square · last modified 2022-05-16. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Welcome-to-the-BEARMARKET-30MIN.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Advanced Momentum EMA Trend Following with RSI Overbought Oversold Trading StrategyPine Script · Mean reversion · 1d
- TMA LegacyPine Script · Mean reversion · 2h
- Multi Indicator Reversal Point Capture Trading StrategyPine Script · Mean reversion · 1d
- Oma and Apollo Dual Rail Trading StrategyPine Script · Mean reversion · 5m
- Reversal Trading Strategy with Bollinger Bands RSI ADX and ATRPine Script · Mean reversion · 1h
- Trend Reversal Momentum Indicators Crossover Tracking StrategyPine Script · Mean reversion · 1h