Strategy vault / Trend following
Adaptive Range Trading System Based on Dual RSI Indicators
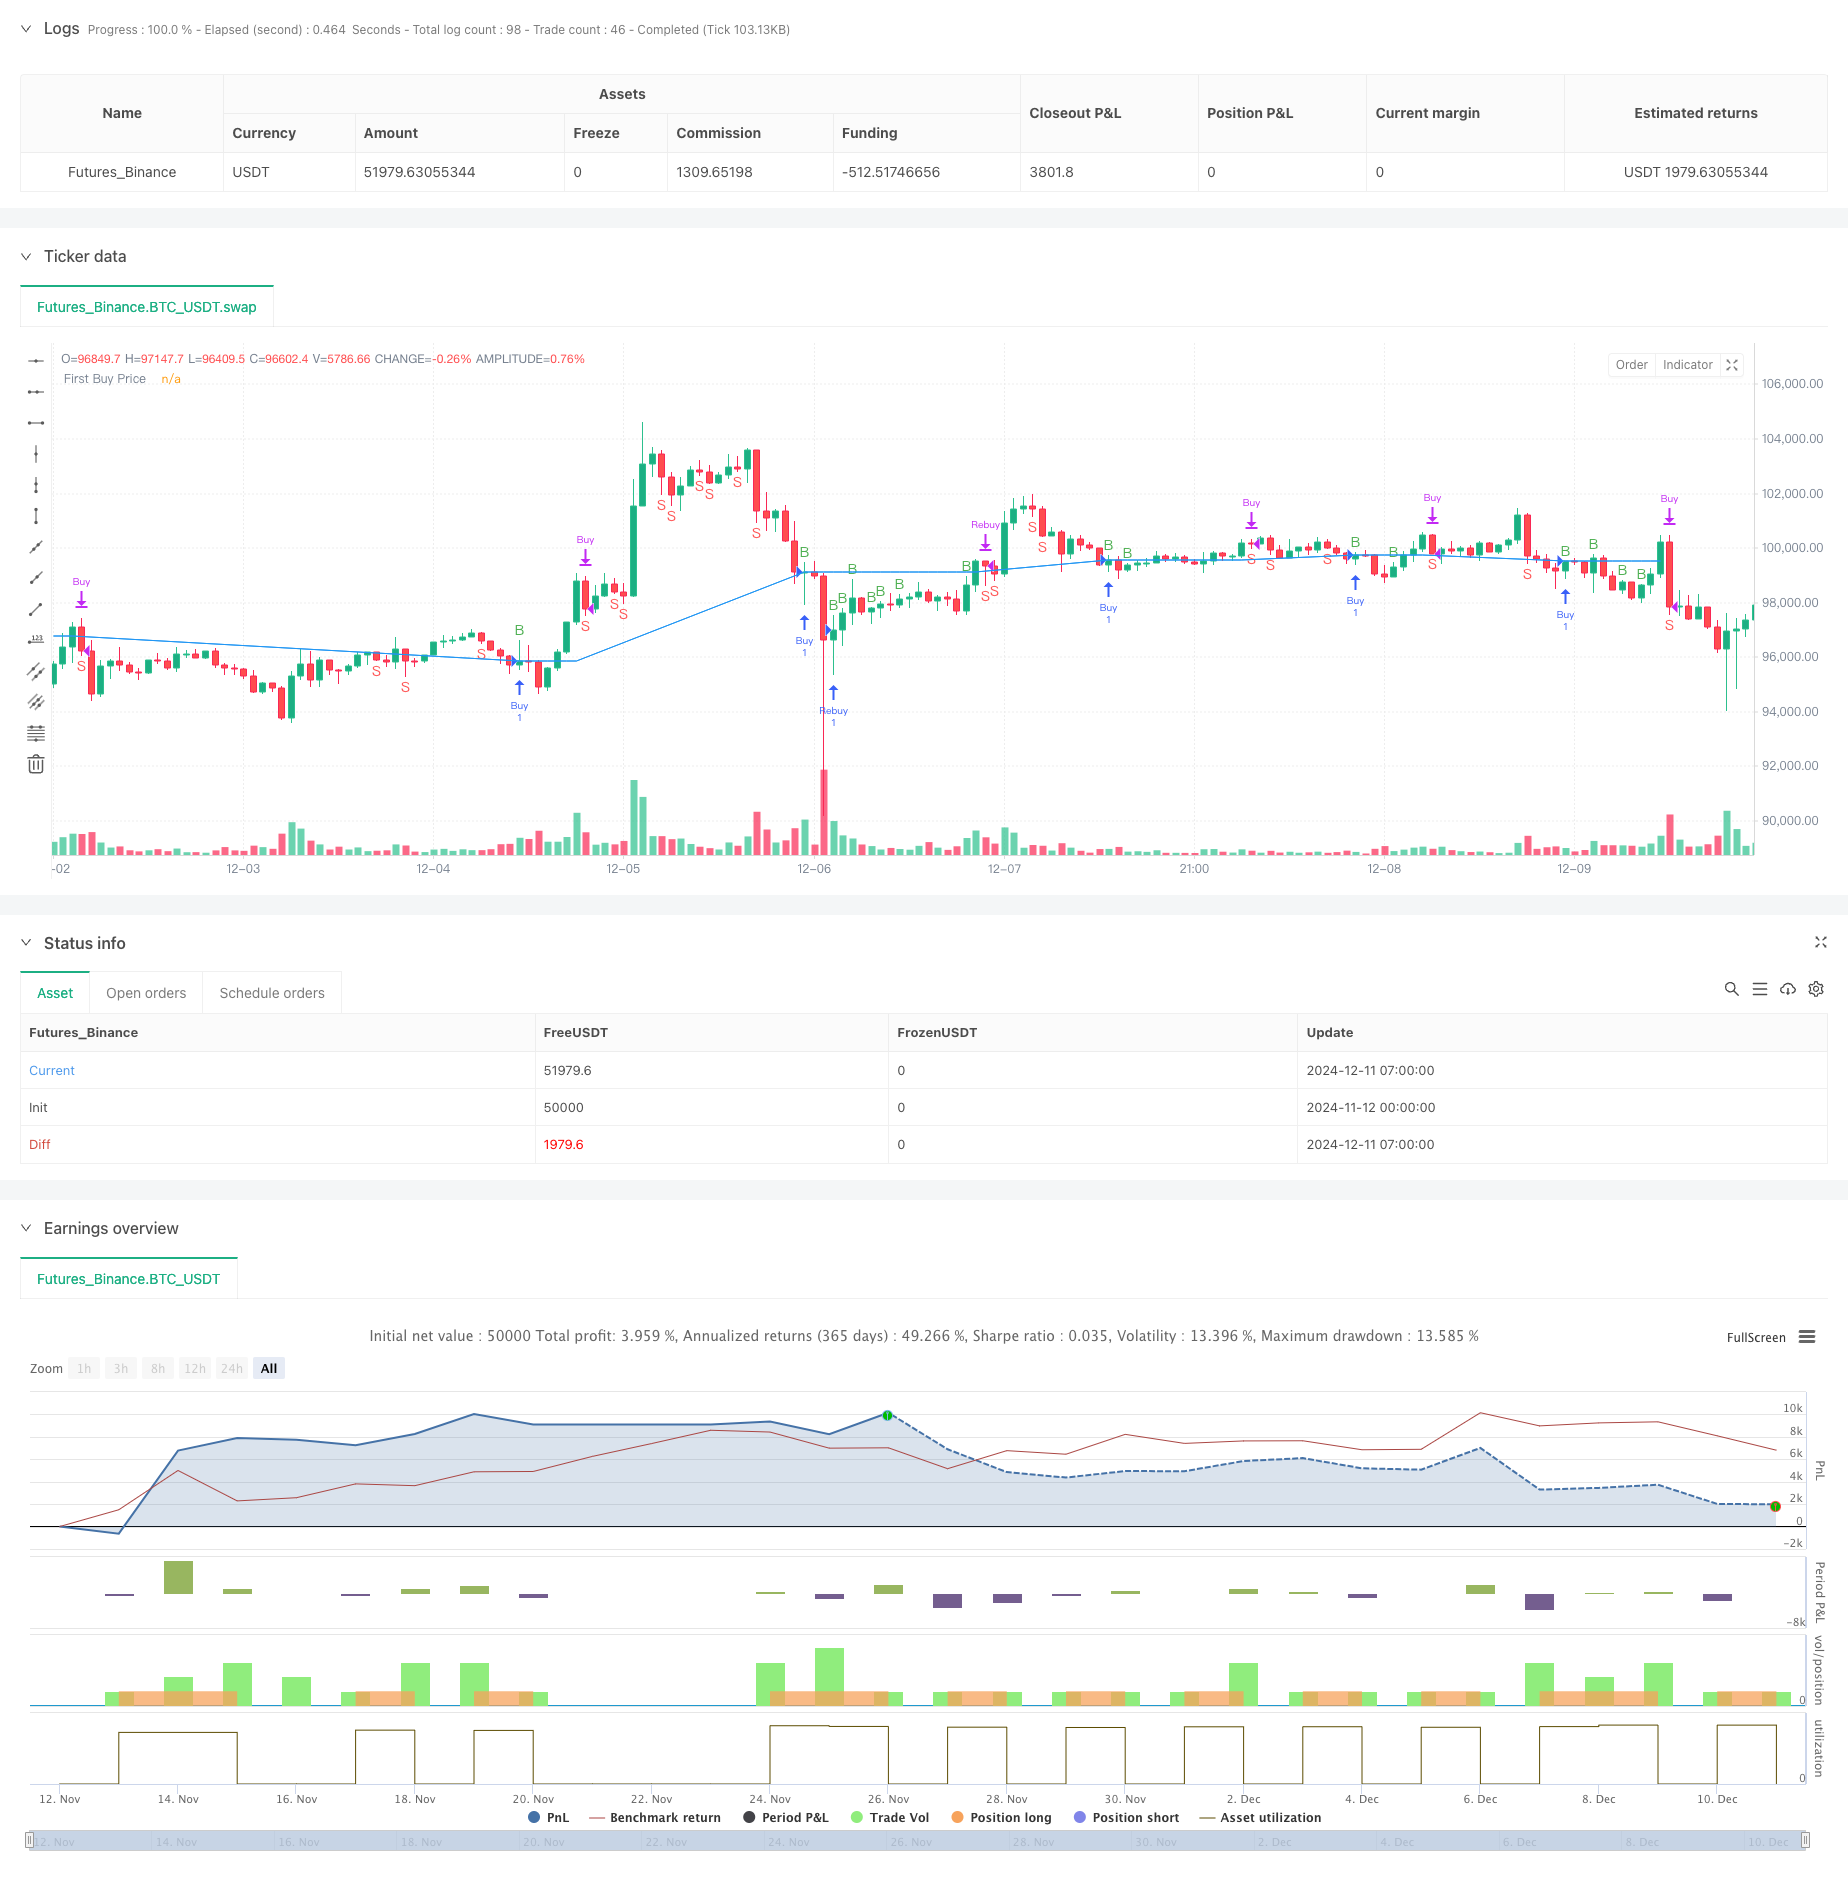
This strategy is an adaptive trading system based on dual RSI (Relative Strength Index) indicators. It combines RSI indicators from different timeframes to identify market trends and trading opportunities while…
Overview
This strategy is an adaptive trading system based on dual RSI (Relative Strength Index) indicators. It combines RSI indicators from different timeframes to identify market trends and trading opportunities while optimizing trading performance through money management and risk control mechanisms. The core strength of the strategy lies in the synergy between multi-period RSIs to enhance profitability while maintaining trading safety.
Strategy Principles
The strategy uses a 7-period RSI indicator as the primary trading signal, combined with a daily RSI as a trend filter. A long position is initiated when the short-period RSI breaks above 40 and the daily RSI is above 55. If the price drops below the initial entry price during a position, the system automatically adds to the position to lower the average cost. Positions are closed when RSI breaks below from above 60. A 5% stop-loss is implemented for risk control. The strategy also includes a money management module that automatically calculates position sizes based on total capital and preset risk ratios.
Strategy Advantages
- Multi-period RSI combination improves signal reliability
- Adaptive position averaging mechanism effectively reduces holding costs
- Comprehensive money management system adjusts positions based on risk preference
- Fixed stop-loss protection strictly controls risk per trade
- Considers trading costs for more realistic trading conditions
Strategy Risks
- RSI indicators may generate false signals in volatile markets
- Position averaging mechanism may lead to significant losses in continuous downtrends
- Fixed percentage stop-loss may be too conservative in high volatility periods
- Trading costs can significantly impact returns during frequent trading
- Strategy execution requires sufficient liquidity
Optimization Directions
- Incorporate volatility indicators (like ATR) for dynamic stop-loss adjustment
- Add trend strength filters to reduce false signals in ranging markets
- Optimize position averaging logic with dynamic adjustments based on market volatility
- Include RSI confirmations from additional timeframes
- Develop adaptive position sizing system
Summary
This is a complete trading system combining technical analysis and risk management. It generates trading signals through multi-period RSI coordination while controlling risk through money management and stop-loss mechanisms. The strategy is suitable for trending markets but requires parameter optimization based on actual market conditions. The system's good extensibility leaves room for further optimization.
Source Pine Script
/*backtest
start: 2024-11-12 00:00:00
end: 2024-12-11 08:00:00
period: 1h
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Dual RSI with Rebuy Logic + Capital, Commission, and Stop Loss", overlay=true)

// Parameter
rsi_length = input.int(7, title="RSI Length")
daily_rsi_length = input.int(7, title="Daily RSI Length")
capital = input.float(10000, title="Initial Capital", minval=0)  // Kapital
risk_per_trade = input.float(0.01, title="Risk per Trade (%)", minval=0.01, maxval=1.0)  // Risikogröße in Prozent
commission = input.float(0.1, title="Commission (%)", minval=0, maxval=100)  // Kommission in Prozent
stop_loss_pct = input.float(5, title="Stop Loss (%)", minval=0.1, maxval=100)  // Stop-Loss in Prozent

// Ordergröße berechnen
risk_amount = capital * risk_per_trade
order_size = risk_amount / close  // Größe der Order basierend auf Risikogröße und Preis

// Daily RSI
day_rsi = request.security(syminfo.tickerid, "D", ta.rsi(close, daily_rsi_length), lookahead=barmerge.lookahead_on)

// RSI auf aktuellem Timeframe
rsi = ta.rsi(close, rsi_length)

// Kauf- und Verkaufsbedingungen
buy_condition = rsi[1] < 40 and rsi > rsi[1] and day_rsi > 55
sell_condition = rsi[1] > 60 and rsi < rsi[1]

// Variablen, um den Preis des ersten Kaufs zu speichern
var float first_buy_price = na
var bool is_position_open = false

// Kauf-Logik
if buy_condition
    if not is_position_open
        // Initiales Kaufsignal
        strategy.entry("Buy", strategy.long, qty=1)
        first_buy_price := close
        is_position_open := true
    else if close < first_buy_price
        // Rebuy-Signal, nur wenn Preis niedriger als erster Kaufpreis
        strategy.entry("Rebuy", strategy.long, qty=1)

// Verkaufs-Logik
if sell_condition and is_position_open
    strategy.close("Buy")
    strategy.close("Rebuy")
    first_buy_price := na  // Zurücksetzen des Kaufpreises
    is_position_open := false

// Stop-Loss-Bedingung
if is_position_open
    // Stop-Loss-Preis berechnen (5% unter dem Einstiegspreis)
    stop_loss_price = first_buy_price * (1 - stop_loss_pct / 100)

    // Stop-Loss für "Buy" und "Rebuy" festlegen
    strategy.exit("Stop Loss Buy", from_entry="Buy", stop=stop_loss_price)
    strategy.exit("Stop Loss Rebuy", from_entry="Rebuy", stop=stop_loss_price)

// Performance-Metriken berechnen (mit Kommission)
gross_profit = strategy.netprofit / capital * 100
commission_cost = commission / 100 * strategy.closedtrades
net_profit = gross_profit - commission_cost

// Debug-Plots
plot(first_buy_price, title="First Buy Price", color=color.blue, linewidth=1)
plotchar(buy_condition, title="Buy Condition", char='B', location=location.abovebar, color=color.green)
plotchar(sell_condition, title="Sell Condition", char='S', location=location.belowbar, color=color.red)

// Debugging für Performance
Published by ChaoZhang on the FMZ strategy square · last modified 2024-12-13. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Adaptive-Range-Trading-System-Based-on-Dual-RSI-Indicators.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive ATR and RSI Trend Following Strategy with Trailing Stop LossPine Script · Trend following · 1h
- Advanced Supertrend Indicator Trading Mechanism Optimization StrategyPine Script · Trend following · 1d
- BB Percentage Index Trend Fading StrategyPine Script · Trend following · 1h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dual Indicator Dynamic Trend Trading Strategy Multi dimensional Technical Analysis System Based on RSI and MACDPine Script · Trend following