Advanced Dual Moving Average Momentum Trend Following Trading System
This strategy is a momentum trend following system based on dual moving averages, combining crossover signals from fast and slow moving averages with a filter line to optimize entry timing, achieving stable trading…
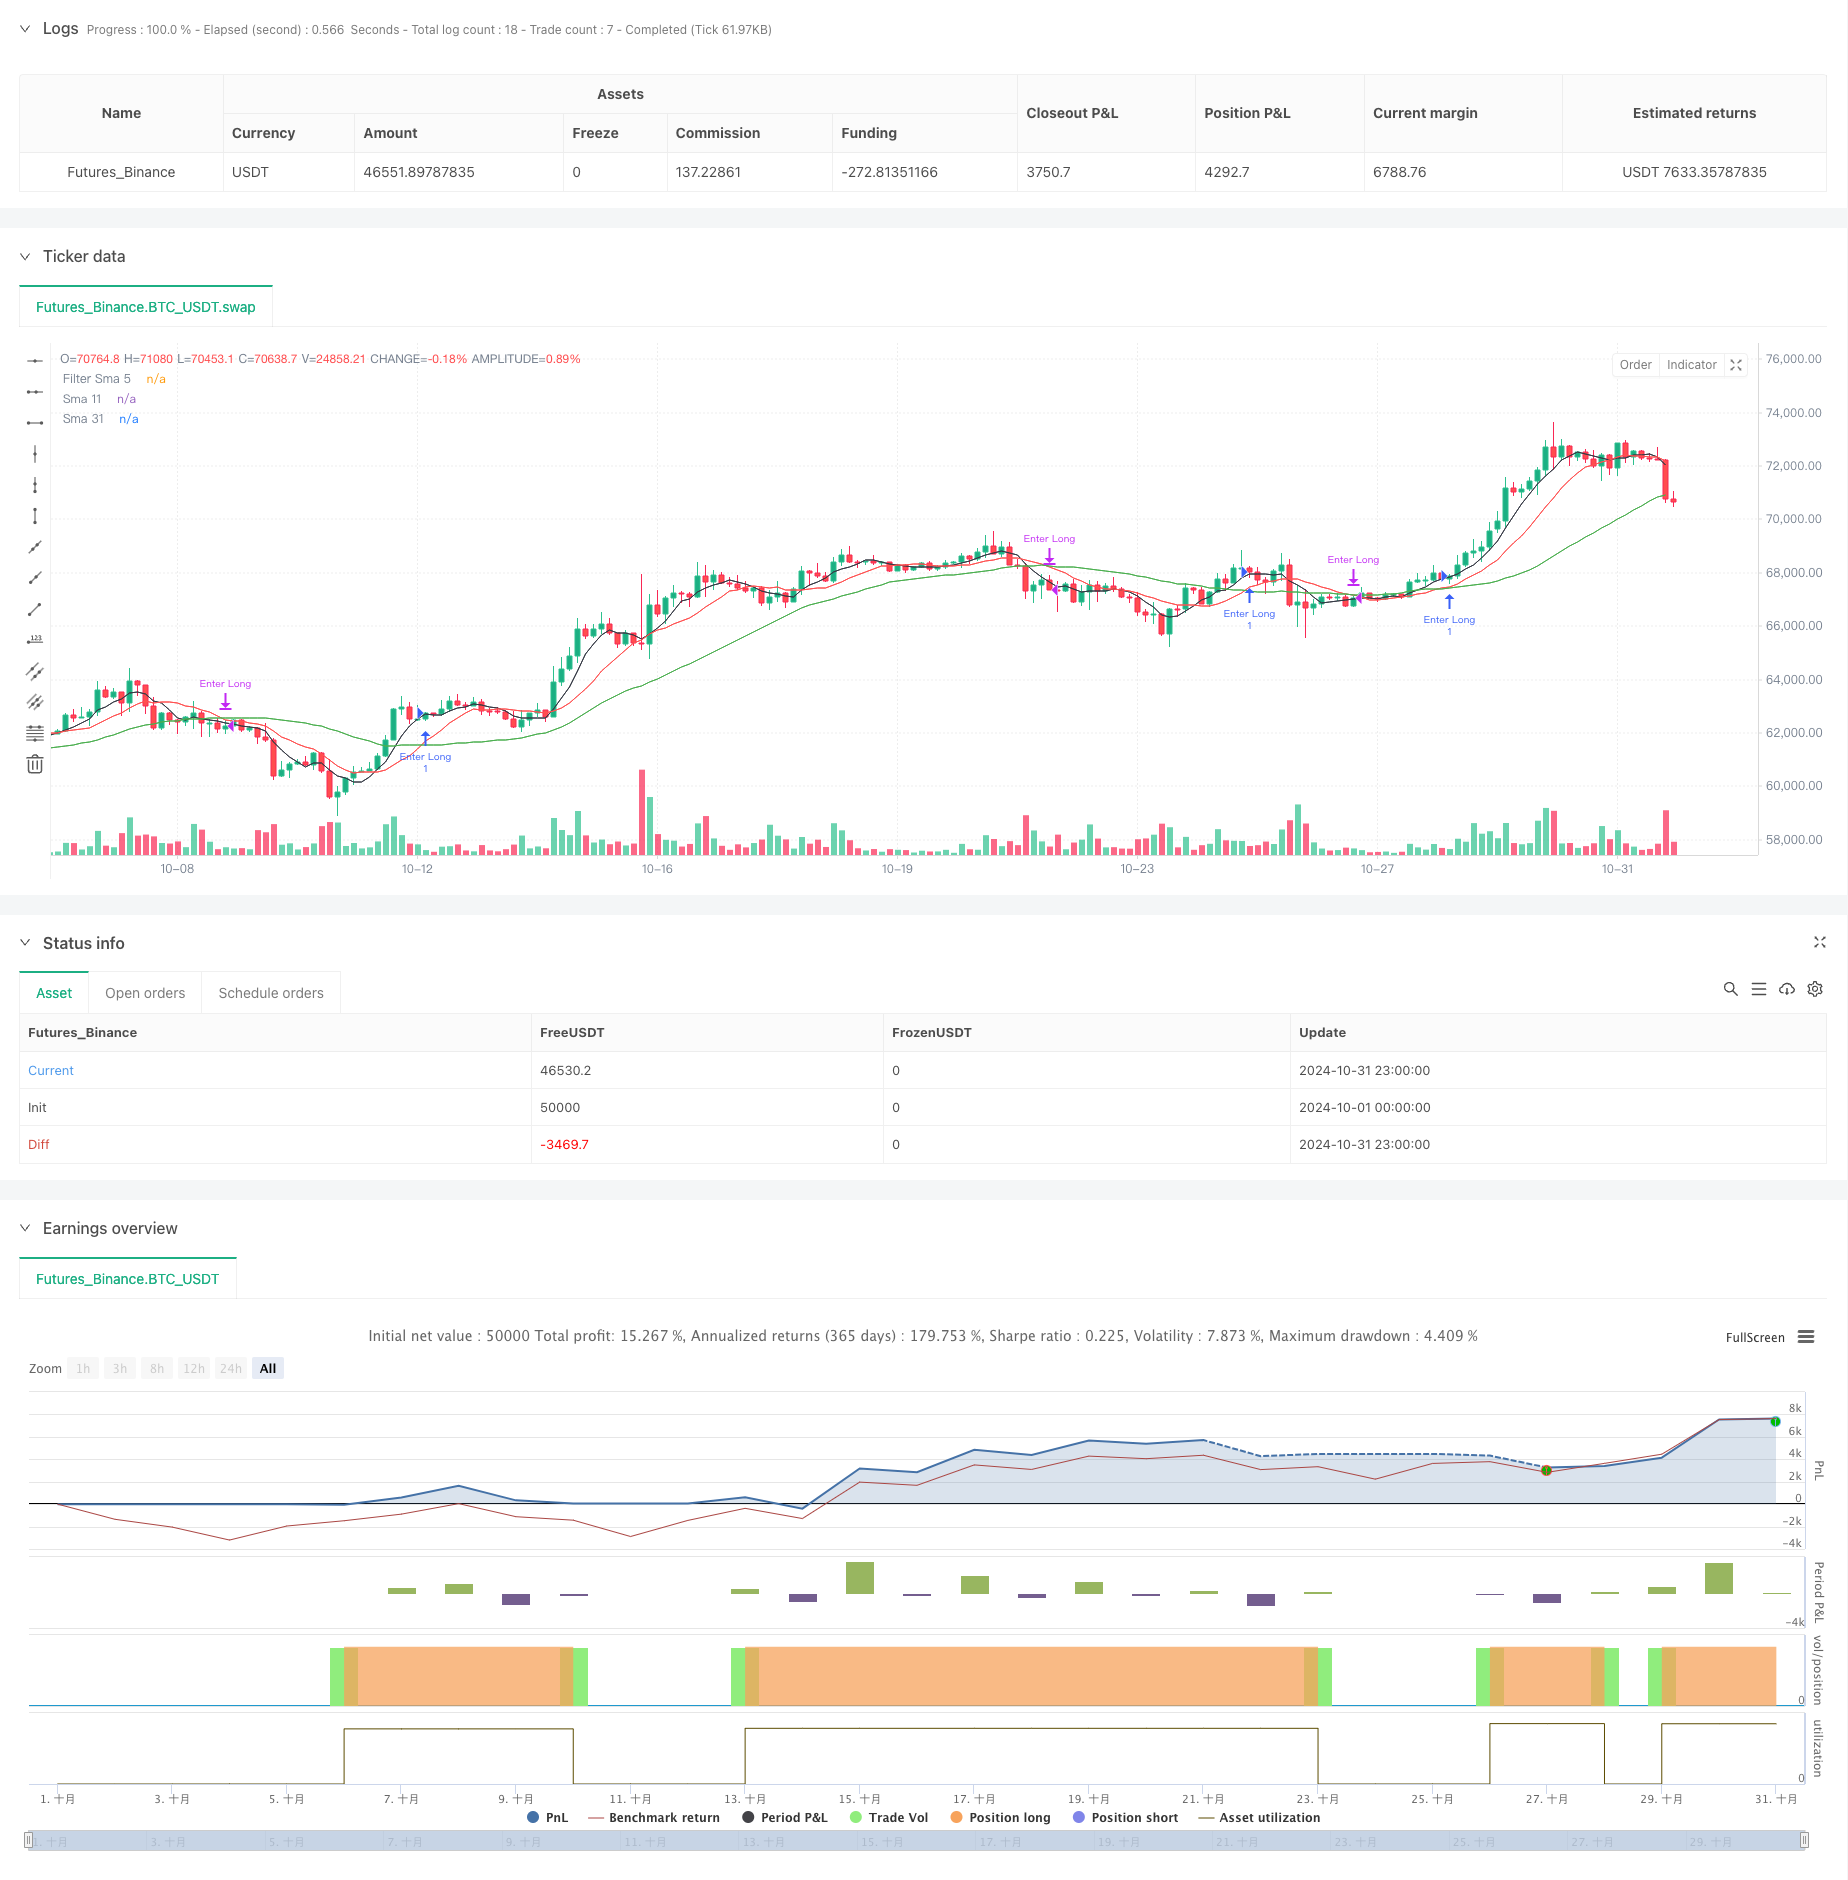
This strategy is a momentum trend following system based on dual moving averages, combining crossover signals from fast and slow moving averages with a filter line to optimize entry timing, achieving stable trading results through proper money management and risk control.
Strategy Principles
The strategy employs 11-period and 31-period Simple Moving Averages (SMA) as the main signal system, with a 5-period moving average as a filter. Long entry signals are generated when the fast line (SMA11) crosses above the slow line (SMA31) and price is above the filter average. Positions are closed when the fast line crosses below the slow line. The strategy implements risk management through fixed position sizing.
Strategy Advantages
- Simple and clear signal system, easy to understand and execute
- Multiple moving average confirmation reduces false signals
- Fixed position sizing ensures controllable risk
- Effective trend following capabilities
- Clear entry and exit logic reduces decision hesitation
- Adaptable to different market conditions
Strategy Risks
- Frequent trading may occur in ranging markets
- Inherent lag in moving average systems
- Fixed position sizing may not optimize capital efficiency
- Market volatility changes not considered
- Lack of stop-loss mechanism may lead to significant drawdowns
Strategy Optimization Directions
- Introduce adaptive moving average periods based on market volatility
- Add volatility filters to adjust position sizing in high volatility environments
- Design dynamic money management system to improve capital efficiency
- Implement stop-loss and take-profit mechanisms to control single trade risk
- Consider adding trend strength indicators to optimize entry timing
- Include trading time filters to avoid unfavorable trading periods
Summary
The strategy builds a relatively robust trend following system through multiple moving averages. While it has some inherent limitations, stability and profitability can be further enhanced through appropriate optimization and improvements. Traders are advised to adjust parameters based on specific market conditions when implementing the strategy in live trading.
Source Pine Script
/*backtest
start: 2024-10-01 00:00:00
end: 2024-10-31 23:59:59
period: 3h
basePeriod: 3h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5

strategy('Nifty 30m SMA Crossover Long', overlay=true)

start = timestamp(2020, 1, 1, 0, 0)
end = timestamp(2024, 12, 31, 0, 0)

SlowSma = ta.sma(close, 31)
FastSma = ta.sma(close, 11)
FilterSma = ta.sma(close, 5)

plot(SlowSma, title='Sma 31', color=color.new(color.green, 0))
plot(FastSma, title='Sma 11', color=color.new(color.red, 0))
plot(FilterSma, title='Filter Sma 5', color=color.new(color.black, 0))

// strategy
LongEntry = FastSma > SlowSma and close > FilterSma
LongExit = FastSma < SlowSma

MyQty = 10000000 / close

// // Plot signals to chart
// plotshape(not LongExit and strategy.position_size > 0 and bIndicator, title='Hold', location=location.abovebar, color=color.new(color.blue, 0), style=shape.square, text='Hold', textcolor=color.new(color.blue, 0))
// plotshape(LongExit and bIndicator and strategy.position_size > 0, title='Exit', location=location.belowbar, color=color.new(color.red, 0), style=shape.triangledown, text='Sell', textcolor=color.new(color.red, 0))
// plotshape(LongEntry and strategy.position_size == 0 and bIndicator, '', shape.arrowup, location.abovebar, color.new(color.green, 0), text='Buy', textcolor=color.new(color.green, 0))
// plotshape(not LongEntry and strategy.position_size == 0 and bIndicator, '', shape.circle, location.belowbar, color.new(color.yellow, 0), text='Wait', textcolor=color.new(color.black, 0))


if time >= start and time < end
    strategy.entry('Enter Long', strategy.long, qty=1, when=LongEntry)
    strategy.close('Enter Long', when=LongExit)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-11-27. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Advanced-Dual-Moving-Average-Momentum-Trend-Following-Trading-System.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX Momentum Trend StrategyPine Script · Momentum · 10m
- Adaptive Trend Following Strategy Based on Momentum OscillatorPine Script · Momentum · 1d
- Bollinger Bands Momentum Trend Following Quantitative StrategyPine Script · Momentum · 1d
- Confirmed SMA Crossover Momentum StrategyPine Script · Momentum · 1d
- Cross Momentum Trend Following Strategy SMA RSI Cross Momentum SystemPine Script · Momentum · 1h
- Dual Moving Average Momentum Trading Strategy Time Optimized Trend Following SystemPine Script · Momentum · 2m