Strategy vault / Trend following
Alpha Trend Strategy with Trailing Stop Loss
The Alpha Trend Strategy with Trailing Stop Loss is an enhanced version of the Alpha Trend Strategy by incorporating a trailing stop loss mechanism, which can control risks more effectively and improve overall returns.
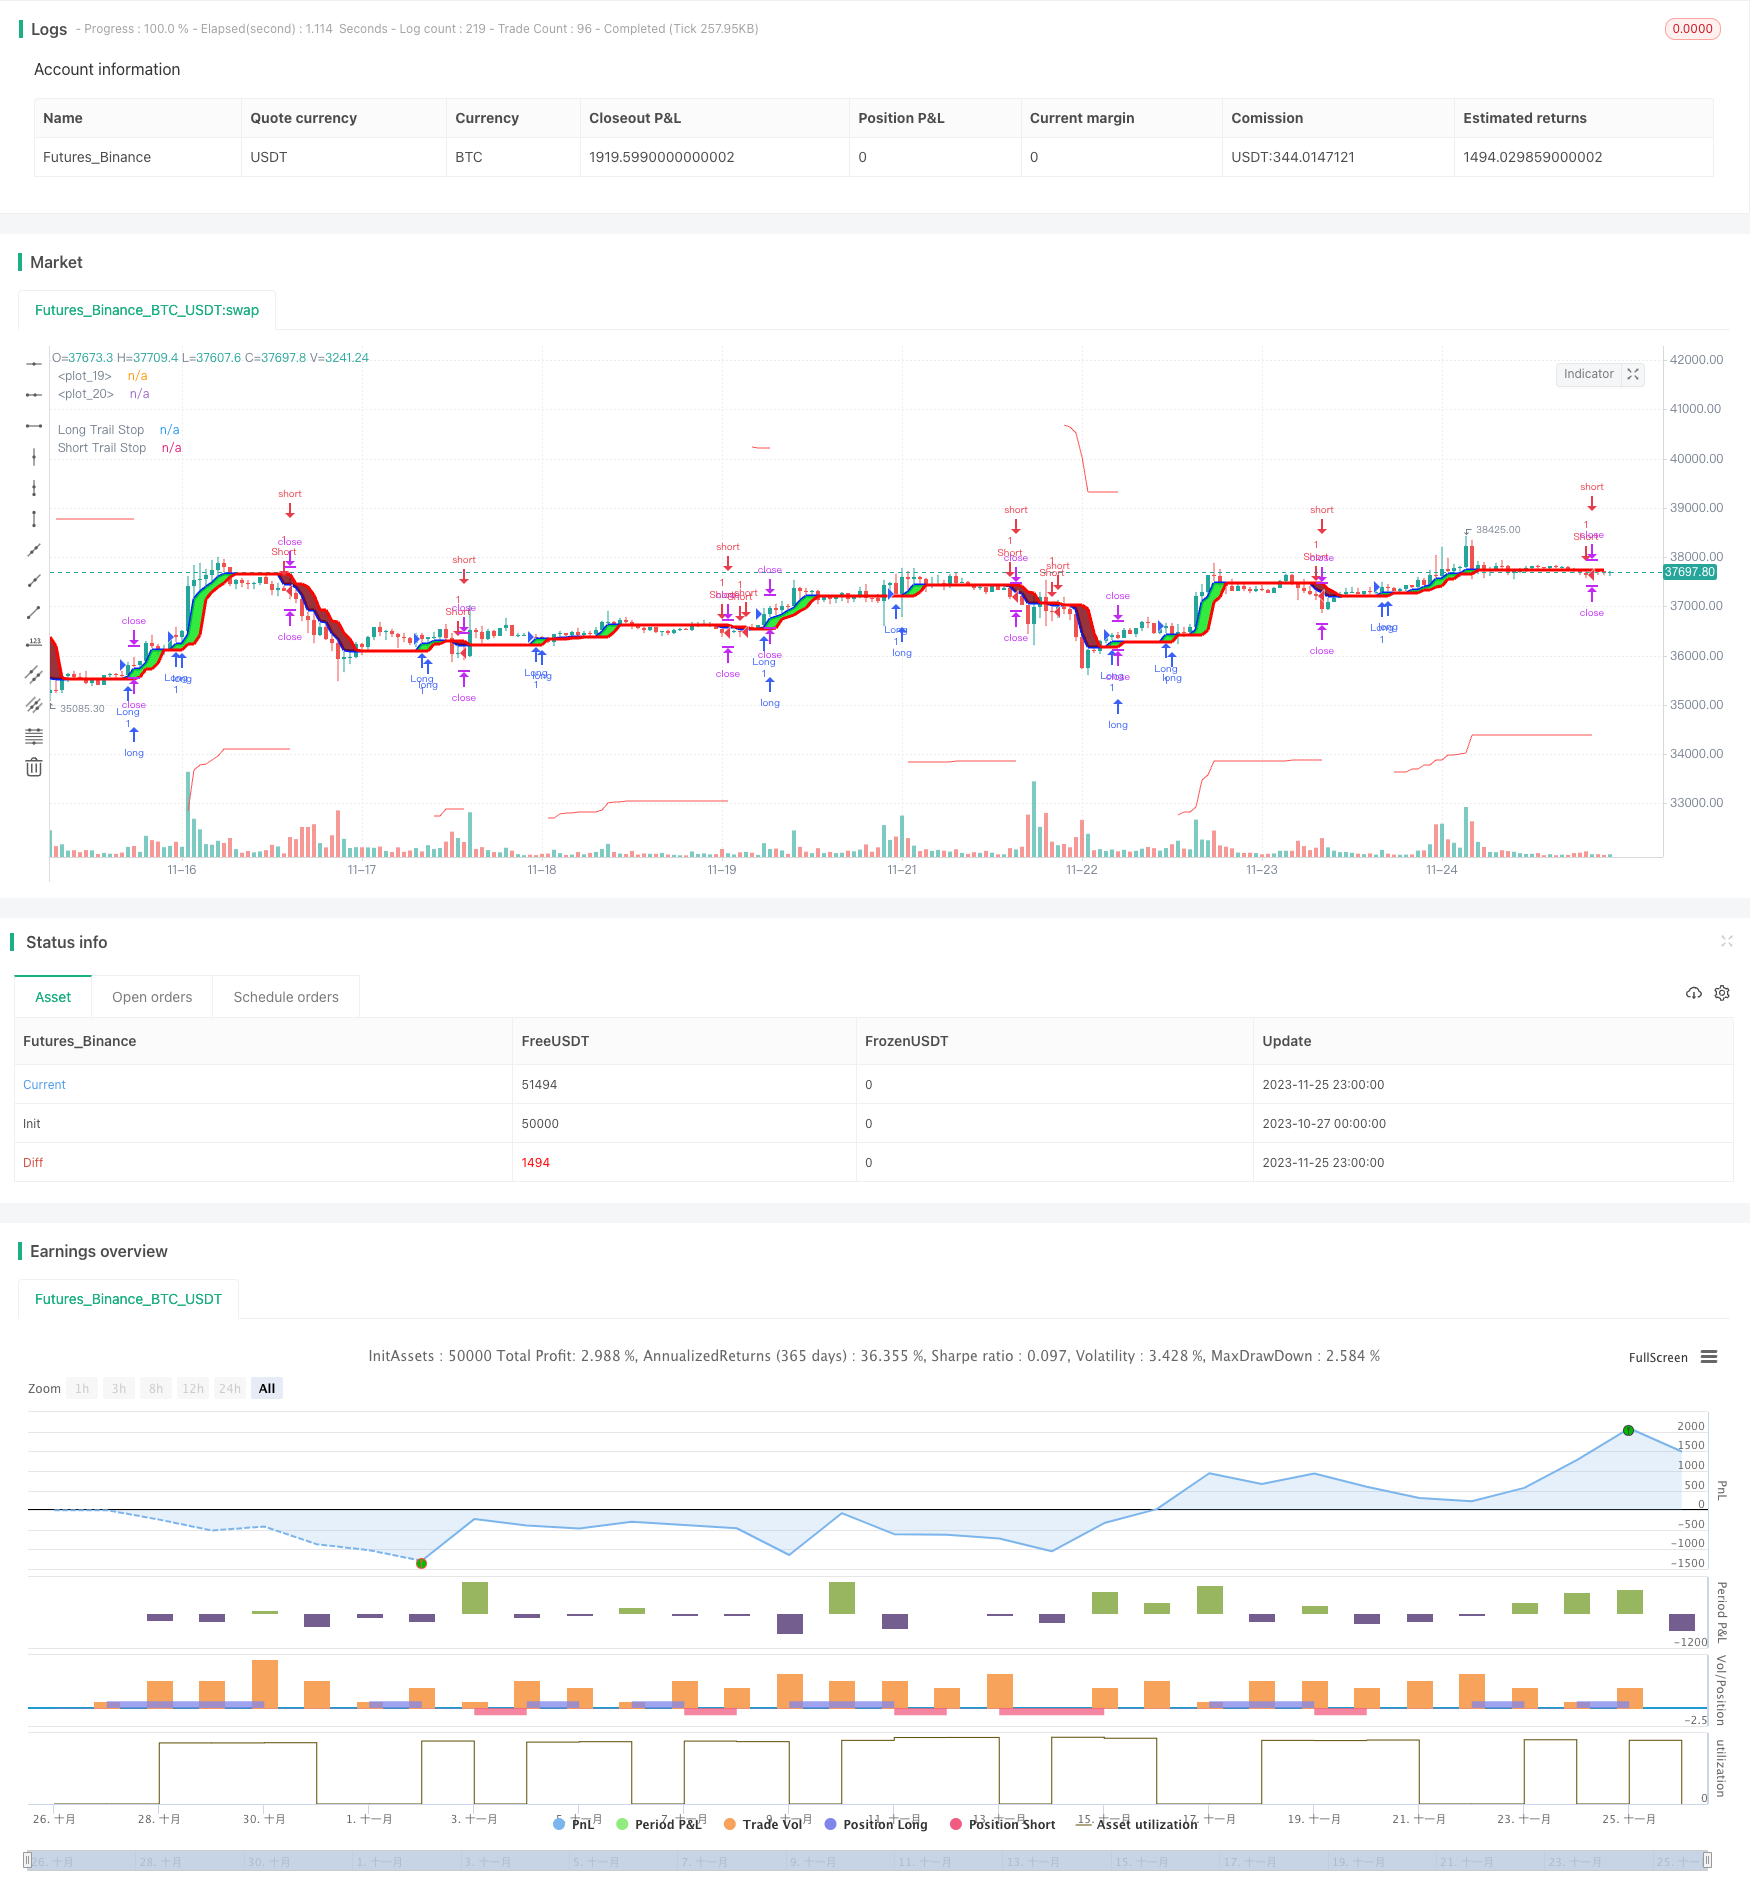
Overview
The Alpha Trend Strategy with Trailing Stop Loss is an enhanced version of the Alpha Trend Strategy by incorporating a trailing stop loss mechanism, which can control risks more effectively and improve overall returns.
Strategy Logic
The strategy first uses the Alpha indicator to determine price trends. When the Alpha indicator goes up, it is a bullish signal. When the Alpha indicator goes down, it is a bearish signal. The strategy generates buy and sell signals based on the golden cross and dead cross of the Alpha indicator.
Meanwhile, a trailing stop loss mechanism is enabled. The trailing stop loss level defaults to 10% of the closing price of the day. When holding long positions, if the price falls below the stop loss level, the strategy will exit the position to stop loss. Similarly for short positions. This helps better lock in profits and reduce risks.
Advantage Analysis
The Alpha trend has stronger capabilities of determining price trends than simple moving averages and other indicators.
By enabling trailing stop loss, single-trade loss can be effectively controlled, lowering risks.
This strategy has strong risk control abilities. Even in unfavorable market conditions, losses can still be minimized.
With fewer reference inputs, this strategy is efficient to calculate, suitable for high frequency trading.
Risk Analysis
In sideways range-bound markets, the strategy may generate many unnecessary trading signals, increasing trading costs and slippage losses.
When enabling trailing stop loss, the stop loss percentage needs to set appropriately. An excessively high or low percentage will both be unfavorable for the strategy's profitability.
In violently fluctuating prices, the probability of stop loss being triggered will significantly rise, increasing the risk of being locked in positions.
When optimizing the stop loss parameters, various factors including the underlying's characteristics and trading frequency should be considered, not just pursuing maximum returns.
The above risks could be alleviated by adjusting the Alpha indicator parameters, setting DYNAMIC stop loss, shortening trading cycle lengths, etc.
Optimization Directions
Different indicator parameters can be tested to find more suitable Alpha indicator parameter combinations.
Attempt to set stop loss percentages dynamically based on ATR to better adapt to market fluctuations.
Combine with other indicators such as MACD, KD to filter out some false signals.
Parameters can be automatically optimized based on live trading and backtesting results, using machine learning techniques to improve the intelligence of parameter selection.
Conclusion
The Alpha Trend Strategy with Trailing Stop Loss combines trend determination and risk control. It can effectively identify price trends and lock in profits to reduce risks. Compared to simple trend tracking strategies, this strategy can obtain higher steady returns. With various aspects of optimization, it has the potential to achieve even better performance.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_float_1 | true | Multiplier |
| v_input_1 | 14 | Common Period |
| v_input_2_close | 0 | src: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_3 | false | Show Signals? |
| v_input_4 | false | Change calculation (no volume data)? |
| v_input_bool_1 | true | Enable Trailing Stop (%) |
| v_input_float_2 | 10 | Trailing (%) |
Source Pine Script
/*backtest
start: 2023-10-27 00:00:00
end: 2023-11-26 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// author © KivancOzbilgic
// developer © KivancOzbilgic
//@version=5

strategy("AlphaTrend Strategy", shorttitle='ATst', overlay=true, format=format.price, precision=2, margin_long=100, margin_short=100)
coeff = input.float(1, 'Multiplier', step=0.1)
AP = input(14, 'Common Period')
ATR = ta.sma(ta.tr, AP)
src = input(close)
showsignalsk = input(title='Show Signals?', defval=false)
novolumedata = input(title='Change calculation (no volume data)?', defval=false)
upT = low - ATR * coeff
downT = high + ATR * coeff
AlphaTrend = 0.0
AlphaTrend := (novolumedata ? ta.rsi(src, AP) >= 50 : ta.mfi(hlc3, AP) >= 50) ? upT < nz(AlphaTrend[1]) ? nz(AlphaTrend[1]) : upT : downT > nz(AlphaTrend[1]) ? nz(AlphaTrend[1]) : downT

color1 = AlphaTrend > AlphaTrend[1] ? #00E60F : AlphaTrend < AlphaTrend[1] ? #80000B : AlphaTrend[1] > AlphaTrend[3] ? #00E60F : #80000B
k1 = plot(AlphaTrend, color=color.new(#0022FC, 0), linewidth=3)
k2 = plot(AlphaTrend[2], color=color.new(#FC0400, 0), linewidth=3)

fill(k1, k2, color=color1)

buySignalk = ta.crossover(AlphaTrend, AlphaTrend[2])
sellSignalk = ta.crossunder(AlphaTrend, AlphaTrend[2])


K1 = ta.barssince(buySignalk)
K2 = ta.barssince(sellSignalk)
O1 = ta.barssince(buySignalk[1])
O2 = ta.barssince(sellSignalk[1])

plotshape(buySignalk and showsignalsk and O1 > K2 ? AlphaTrend[2] * 0.9999 : na, title='BUY', text='BUY', location=location.absolute, style=shape.labelup, size=size.tiny, color=color.new(#0022FC, 0), textcolor=color.new(color.white, 0))

plotshape(sellSignalk and showsignalsk and O2 > K1 ? AlphaTrend[2] * 1.0001 : na, title='SELL', text='SELL', location=location.absolute, style=shape.labeldown, size=size.tiny, color=color.new(color.maroon, 0), textcolor=color.new(color.white, 0))


// //ENTER SOME SETUP TRADES FOR TSL EXAMPLE
// longCondition = ta.crossover(ta.sma(close, 10), ta.sma(close, 20))
// if longCondition
//     strategy.entry('My Long Entry Id', strategy.long)

// shortCondition = ta.crossunder(ta.sma(close, 10), ta.sma(close, 20))
// if shortCondition
//     strategy.entry('My Short Entry Id', strategy.short)


longCondition = buySignalk
if (longCondition)
    strategy.entry("Long", strategy.long)

shortCondition = sellSignalk
if (shortCondition)
    strategy.entry("Short", strategy.short)


enableTrailing = input.bool(title='Enable Trailing Stop (%)',defval = true)
//TRAILING STOP CODE
trailStop = input.float(title='Trailing (%)', minval=0.0, step=0.1, defval=10) * 0.01


longStopPrice = 0.0
shortStopPrice = 0.0
longStopPrice := if strategy.position_size > 0
    stopValue = close * (1 - trailStop)
    math.max(stopValue, longStopPrice[1])
else
    0
shortStopPrice := if strategy.position_size < 0
    stopValue = close * (1 + trailStop)
    math.min(stopValue, shortStopPrice[1])
else
    999999

//PLOT TSL LINES
plot(series=strategy.position_size > 0 ? longStopPrice : na, color=color.new(color.red, 0), style=plot.style_linebr, linewidth=1, title='Long Trail Stop', offset=1, title='Long Trail Stop')
plot(series=strategy.position_size < 0 ? shortStopPrice : na, color=color.new(color.red, 0), style=plot.style_linebr, linewidth=1, title='Short Trail Stop', offset=1, title='Short Trail Stop')


if enableTrailing
    //EXIT TRADE @ TSL
    if strategy.position_size > 0
        strategy.exit(id='Close Long', stop=longStopPrice)
    if strategy.position_size < 0
        strategy.exit(id='Close Short', stop=shortStopPrice)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-27. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Alpha-Trend-Strategy-with-Trailing-Stop-Loss.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dynamic Dual EMA Crossover Strategy with Adaptive Profit Loss ControlPine Script · Trend following · 1d
- EMA and RSI Trend Trading StrategyPine Script · Trend following · 1d
- Fixed Range Volume Profile And Anchored VWAP Trend Identification Strategy With Dynamic Stop LossPine Script · Trend following · 1h
- Multi Dimensional Short Term Trend Predictor Technical Analysis and Volatility Adaptive Trading StrategyPine Script · Trend following · 1h