Average True Range Breakout Strategy with Golden Ratio
This is a breakout strategy that utilizes the ATR indicator to generate trading signals. The strategy employs a moving average system to produce entry signals and an amplified ATR channel based on the golden ratio to…
Overview
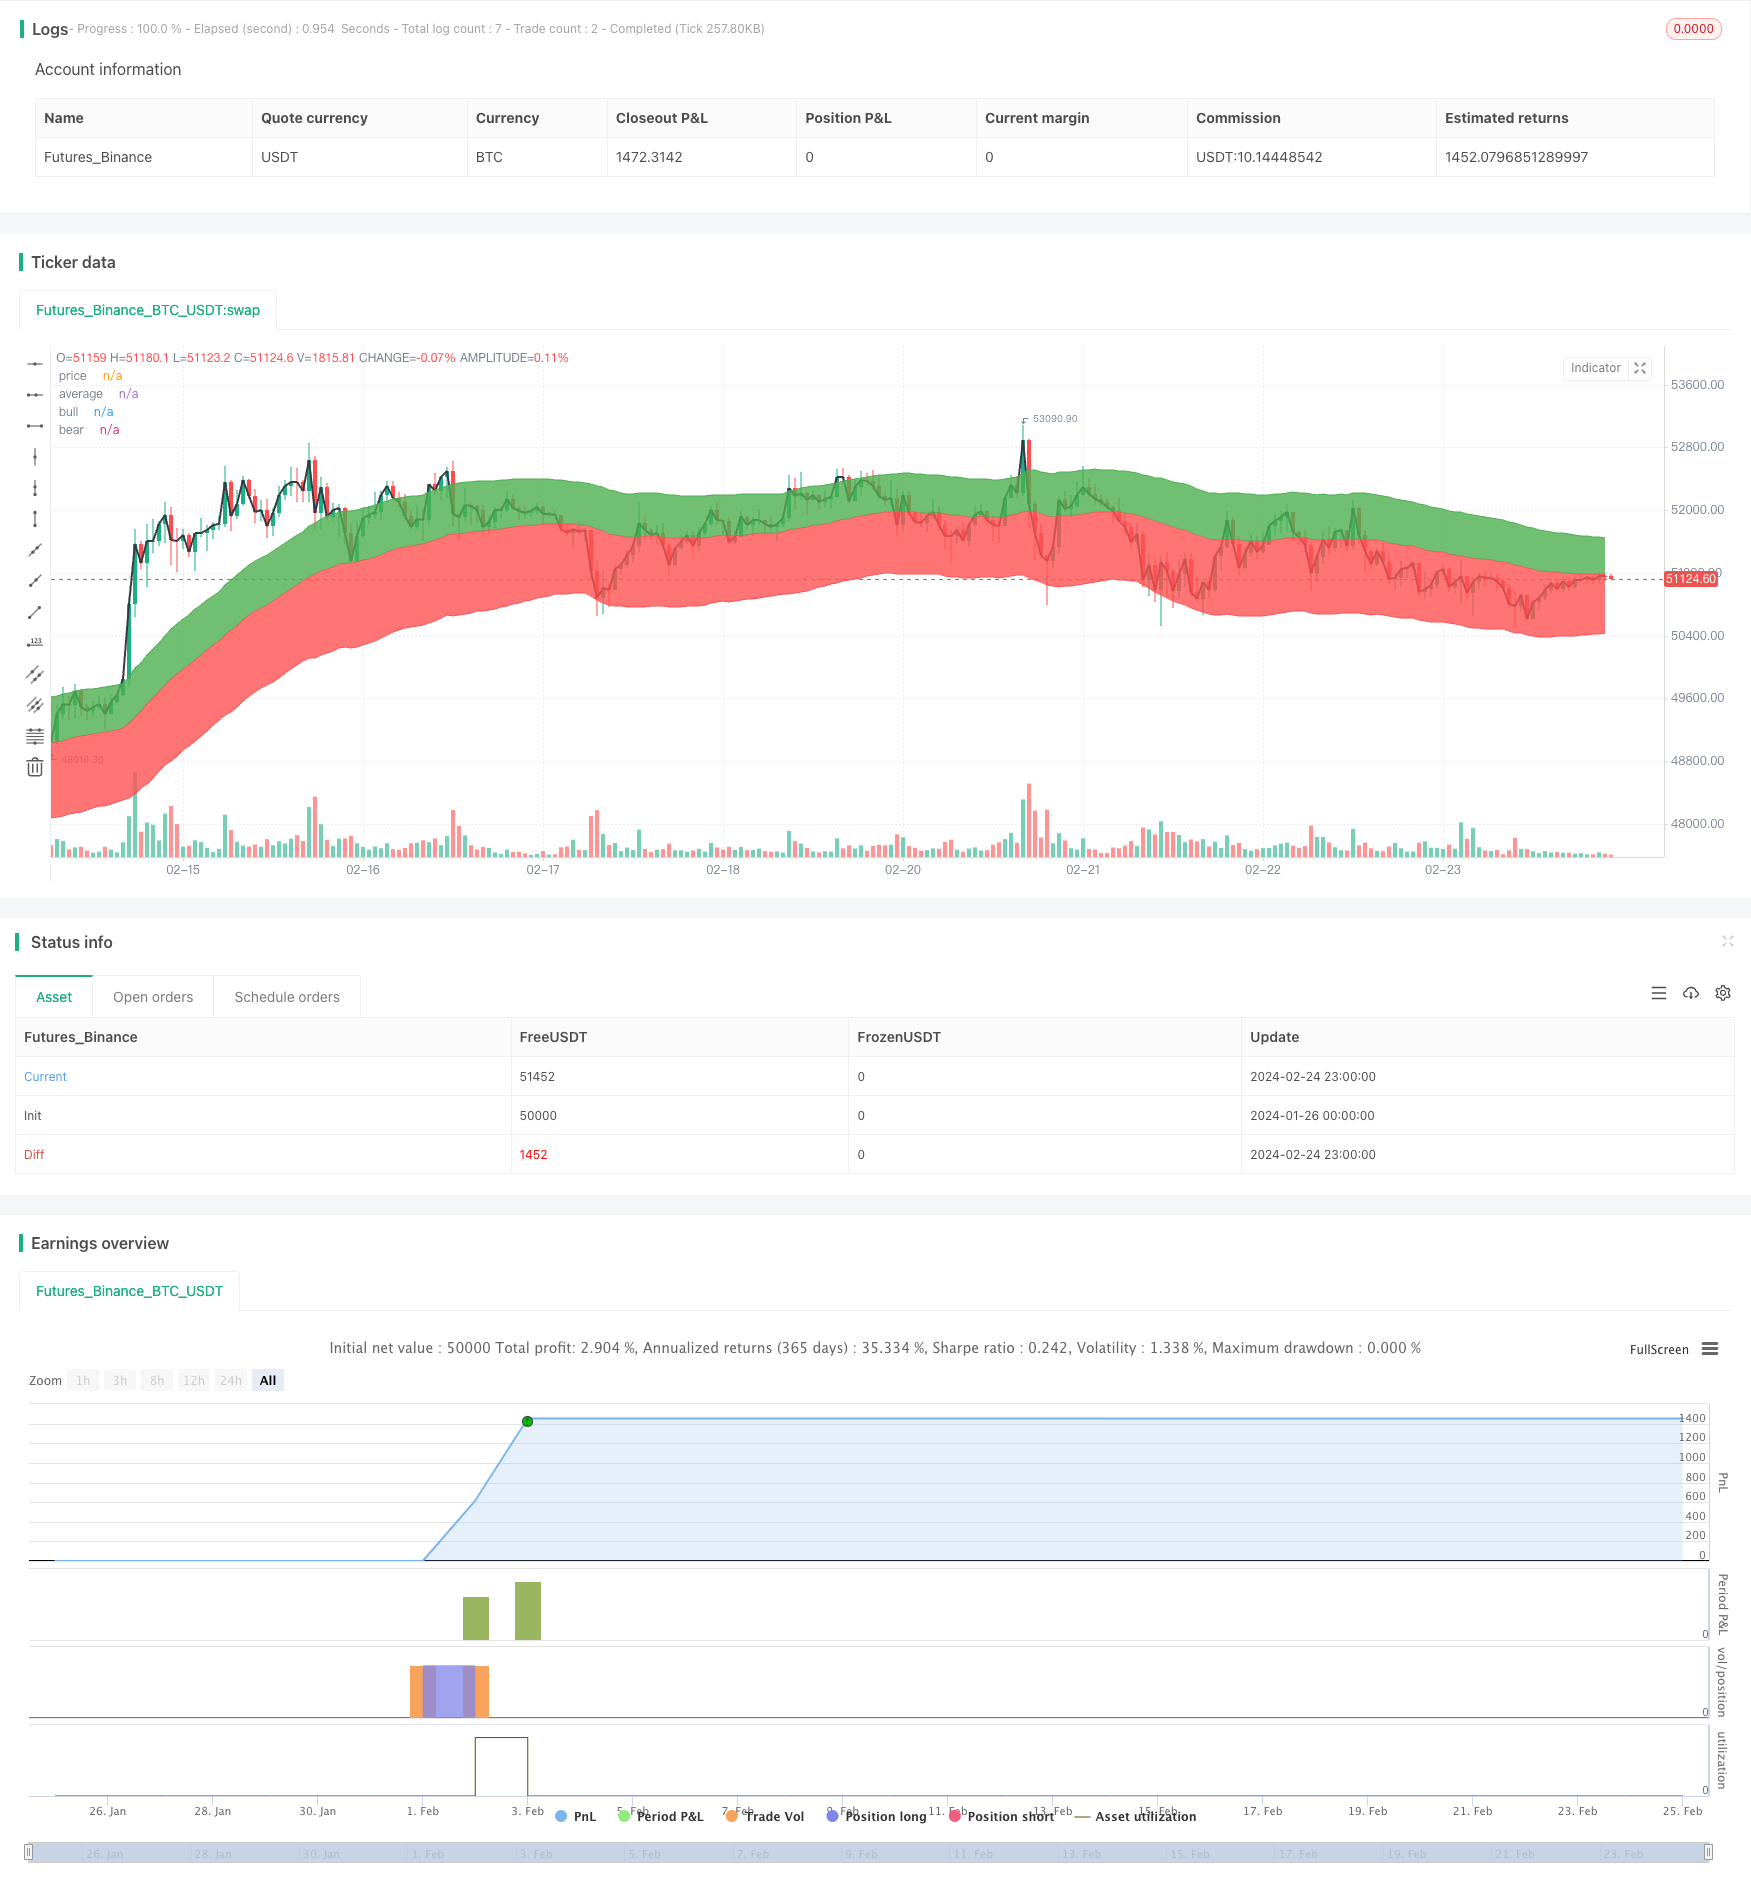
This is a breakout strategy that utilizes the ATR indicator to generate trading signals. The strategy employs a moving average system to produce entry signals and an amplified ATR channel based on the golden ratio to construct long and short positions. It could gain significantly in trends and obtain small but steady profits in range-bound markets.
Principles
The code calculates the ATR over a period of closing prices, amplifies it by 1.618 as the upper band and 2.618 as the lower band. Combined with the EMA, it forms a Bollinger channel breakout system. Go long when price breaks out the lower band upwards and go short when breaking the upper band downwards to follow trends.
Advantages
- The ATR indicator effectively captures market volatility and constructs adaptive trading bands, avoiding overfitting caused by static parameters.
- The amplified ATR bands by the golden ratio expand profit potential without increasing trading frequency.
- The moving average system filters out short-term noises and cooperates with the ATR channel to identify mid-to-long term trends.
Risks
- The ATR indicator may lag during extreme market conditions.
- Improper magnification multiples would lead to excessively high trading frequency.
- Switching signals from long-period moving averages have lags.
Optimization
- The ATR can incorporate the VIX or adjust magnification.
- Employ multiple time frame EMAs to construct adaptive systems.
- Set stop losses to limit maximal loss per trade.
Summary
This strategy integrates moving average filtering, ATR channel tracking and the golden ratio methodology, which can effectively follow mid-to-long term trends with good stability. By tuning parameters, it can be adapted to different products across various frequencies, worthy of exploring for its excellent market adaptivity.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 52 | Length |
| v_input_2 | 1.618 | Length |
| v_input_3 | 2.618 | Length |
| v_input_4 | 8 | From Month |
| v_input_5 | 18 | From Day |
| v_input_6 | 2008 | From Year |
| v_input_7 | true | To Month |
| v_input_8 | true | To Day |
| v_input_9 | 2020 | To Year |
Source Pine Script
/*backtest
start: 2024-01-01 00:00:00
end: 2024-01-31 23:59:59
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy("ATR Long Only Strategy lower band buy", overlay=true, default_qty_type=strategy.percent_of_equity, default_qty_value=100)

len = input(52, type=input.integer, minval=1, title="Length")
mul = input(1.618, type=input.float, minval=0, title="Length")
mullow = input(2.618, type=input.float, minval=0, title="Length")

price = sma(close, 1)
average = ema(close, len)
diff = atr(len) * mul
difflow = atr(len) * mullow

bull_level = average + diff
bear_level = average - difflow
bull_cross = crossunder(price, bear_level)
bear_cross = crossunder(bull_level, price)

FromMonth = input(defval = 8, title = "From Month", minval = 1, maxval = 12)
FromDay   = input(defval = 18, title = "From Day", minval = 1, maxval = 31)
FromYear  = input(defval = 2008, title = "From Year", minval = 2008)
ToMonth   = input(defval = 1, title = "To Month", minval = 1, maxval = 12)
ToDay     = input(defval = 1, title = "To Day", minval = 1, maxval = 31)
ToYear    = input(defval = 2020, title = "To Year", minval = 2019)

start     = timestamp(FromYear, FromMonth, FromDay, 00, 00)
finish    = timestamp(ToYear, ToMonth, ToDay, 23, 59)
startTimeOk()  => true

if (startTimeOk())
    strategy.entry("KOP", strategy.long, when=bull_cross)
    strategy.close("KOP", when=bear_cross)  //strategy.entry("Sell", strategy.short, when=bear_cross)

plot(price, title="price", color=color.black, transp=50, linewidth=2)
a0 = plot(average, title="average", color=color.red, transp=50, linewidth=1)
a1 = plot(bull_level, title="bull", color=color.green, transp=50, linewidth=1)
a2 = plot(bear_level, title="bear", color=color.red, transp=50, linewidth=1)
fill(a0, a1, color=color.green, transp=97)
fill(a0, a2, color=color.red, transp=97)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-26. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Average-True-Range-Breakout-Strategy-with-Golden-Ratio.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- BB Breakout StrategyPine Script · Breakout · 1d
- EMA and Bollinger Bands Breakout StrategyPine Script · Breakout · 1h
- Momentum Breakout Moving Average StrategyPine Script · Breakout · 1d
- Momentum Breakout Trading Strategy 440964Pine Script · Breakout · 5m
- Moving Average Crossover and Upper Rail Breakthrough Impulse StrategyPine Script · Breakout · 1m
- Quantitative Strategy PSARZigZagMACDART Based on Multi Indicator CombinationPine Script · Breakout · 1m