Bollinger Band Awesome Oscillator Breakout Trading Strategy
This strategy combines the Bollinger Bands indicator and the Awesome Oscillator (AO) indicator to implement a breakout trading model. It generates buy and sell signals when the fast EMA breaks through the BB channel…
Overview
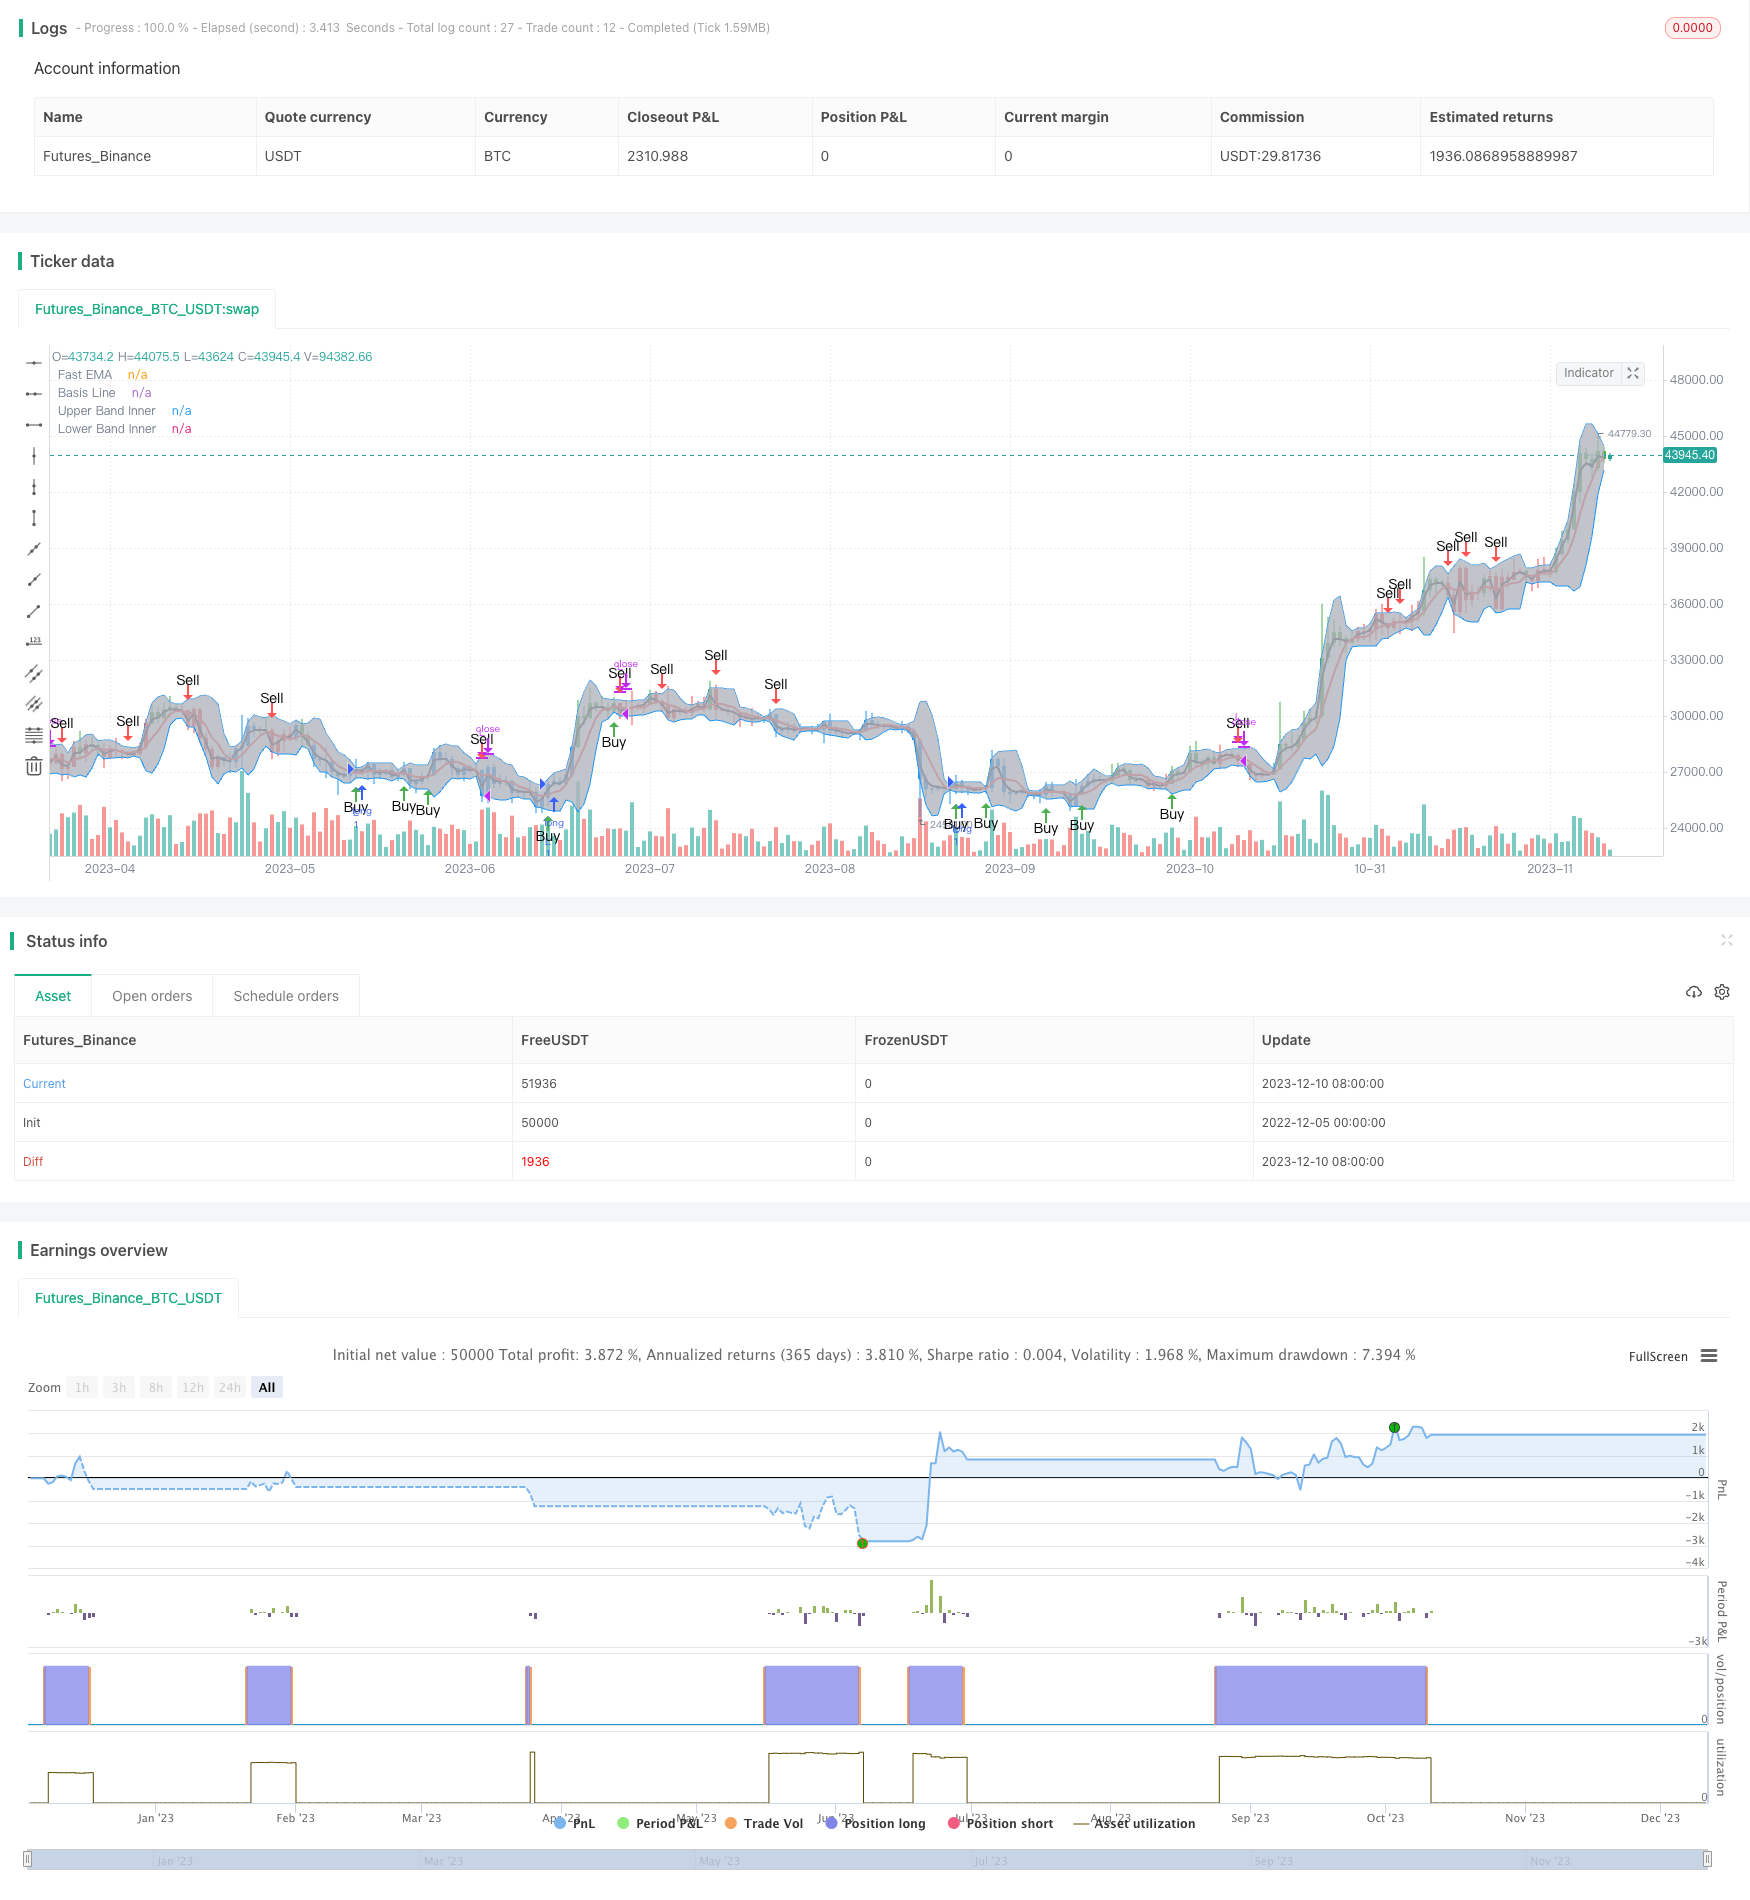
This strategy combines the Bollinger Bands indicator and the Awesome Oscillator (AO) indicator to implement a breakout trading model. It generates buy and sell signals when the fast EMA breaks through the BB channel, together with the AO indicator's directional signals.
Strategy Logic
- Use the middle, upper and lower bands of Bollinger Bands to determine the price channel.
- Judge a channel breakout when fast EMA crosses the middle band.
- AO indicator determines the direction of uptrend or downtrend.
- When fast EMA breaks through middle band upward and AO is positive, a buy signal is generated.
- When fast EMA breaks through middle band downward and AO is negative, a sell signal is generated.
Advantage Analysis
- BB channel avoids wrong signals.
- AO indicator improves accuracy of signals.
- Captures greater profit at the beginning of a trend.
Risk Analysis
- Improper BB parameters may cause too wide or too narrow channel.
- AO parameters affect the accuracy.
- Breakout signal may be false breakout.
Solutions
- Optimize parameters of BB and AO to find best combination.
- Add strength condition to avoid false breakout.
- Combine with other indicators to ensure reliability.
Optimization Directions
- Optimize BB parameters to find suitable channel range.
- Optimize long and short term periods of AO to improve accuracy.
- Add volume or other filters to ensure breakout reliability.
- Optimize strength condition to lower false breakout rate.
Conclusion
This strategy comprehensively considers the price channel, trend direction and breakout model. It can be more robust and profitable through parameter optimization and indicator combinations. Its breakout model captures early trend opportunities and is very practical.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 6 | From Month |
| v_input_2 | true | From Day |
| v_input_3 | 2018 | From Year |
| v_input_4 | true | To Month |
| v_input_5 | true | To Day |
| v_input_6 | 9999 | To Year |
| v_input_7 | false | Use EMA for Bollinger Band |
| v_input_8 | 5 | Bollinger Length |
| v_input_9_close | 0 | Bollinger Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_10 | 2 | Base Multiplier |
| v_input_11 | 2 | Fast EMA length |
| v_input_12 | 34 | Awesome Length Slow |
| v_input_13 | 5 | Awesome Length Fast |
Source Pine Script
/*backtest
start: 2022-12-05 00:00:00
end: 2023-12-11 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3

strategy(shorttitle="BB+AO STRAT", title="BB+AO STRAT", overlay=true)


// === BACKTEST RANGE ===
FromMonth = input(defval = 6, title = "From Month", minval = 1)
FromDay   = input(defval = 1, title = "From Day", minval = 1)
FromYear  = input(defval = 2018, title = "From Year", minval = 2014)
ToMonth   = input(defval = 1, title = "To Month", minval = 1)
ToDay     = input(defval = 1, title = "To Day", minval = 1)
ToYear    = input(defval = 9999, title = "To Year", minval = 2014)

// Bollinger Bands Inputs
bb_use_ema = input(false, title="Use EMA for Bollinger Band")
bb_length = input(5, minval=1, title="Bollinger Length")
bb_source = input(close, title="Bollinger Source")
bb_mult = input(2.0, title="Base Multiplier", minval=0.5, maxval=10)
// EMA inputs
fast_ma_len = input(2, title="Fast EMA length", minval=2)
// Awesome Inputs
nLengthSlow = input(34, minval=1, title="Awesome Length Slow")
nLengthFast = input(5, minval=1, title="Awesome Length Fast")


// Breakout Indicator Inputs
bb_basis = bb_use_ema ? ema(bb_source, bb_length) : sma(bb_source, bb_length)
fast_ma  = ema(bb_source, fast_ma_len)

// Deviation

dev = stdev(bb_source, bb_length)
bb_dev_inner = bb_mult * dev

// Upper bands
inner_high = bb_basis + bb_dev_inner
// Lower Bands
inner_low = bb_basis - bb_dev_inner

// Calculate Awesome Oscillator
xSMA1_hl2 = sma(hl2, nLengthFast)
xSMA2_hl2 = sma(hl2, nLengthSlow)
xSMA1_SMA2 = xSMA1_hl2 - xSMA2_hl2
// Calculate direction of AO
AO = xSMA1_SMA2>=0? xSMA1_SMA2 > xSMA1_SMA2[1] ? 1 : 2 : xSMA1_SMA2 > xSMA1_SMA2[1] ? -1 : -2


// === PLOTTING ===

// plot BB basis
plot(bb_basis, title="Basis Line", color=red, transp=10, linewidth=2)
// plot BB upper and lower bands
ubi = plot(inner_high, title="Upper Band Inner", color=blue, transp=10, linewidth=1)
lbi = plot(inner_low, title="Lower Band Inner", color=blue, transp=10, linewidth=1)
// center BB channel fill
fill(ubi, lbi, title="Center Channel Fill", color=silver, transp=90)

// plot fast ma
plot(fast_ma, title="Fast EMA", color=black, transp=10, linewidth=2)

// Calc breakouts
break_down =   crossunder(fast_ma, bb_basis) and close < bb_basis and abs(AO)==2
break_up   =  crossover(fast_ma, bb_basis) and close > bb_basis and abs(AO)==1

// Show Break Alerts
plotshape(break_down, title="Breakout Down", style=shape.arrowdown, location=location.abovebar, size=size.auto, text="Sell", color=red, transp=0)
plotshape(break_up, title="Breakout Up", style=shape.arrowup, location=location.belowbar, size=size.auto, text="Buy", color=green, transp=0)
// === ALERTS ===


strategy.entry("L", strategy.long, when=(break_up and (time > timestamp(FromYear, FromMonth, FromDay, 00, 00)) and (time < timestamp(ToYear, ToMonth, ToDay, 23, 59))))


strategy.close("L", when=(break_down and (time < timestamp(ToYear, ToMonth, ToDay, 23, 59))))

// === /PLOTTING ===
barcolor(AO == 2 ? red: AO == 1 ? green : blue )


// eofPublished by ChaoZhang on the FMZ strategy square · last modified 2023-12-12. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Bollinger-Band-Awesome-Oscillator-Breakout-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- BB Breakout StrategyPine Script · Breakout · 1d
- Bollinger Band T3 Moving Average StrategyPine Script · Breakout · 10m
- Bollinger Bands Dual track Breakthrough StrategyPine Script · Breakout · 30m
- Bollinger Breakout StrategyPine Script · Breakout · 30m
- Dynamic Bollinger Bands Breakout Quantitative Trading StrategyPine Script · Breakout · 2d
- EMA and Bollinger Bands Breakout StrategyPine Script · Breakout · 1h