Bollinger Band RSI Dual Line Strategy
This strategy combines Bollinger Bands with the Relative Strength Index (RSI) indicator. It requires signals from both indicators - RSI overbought/oversold together with breakouts of Bollinger Bands upper/lower lines…
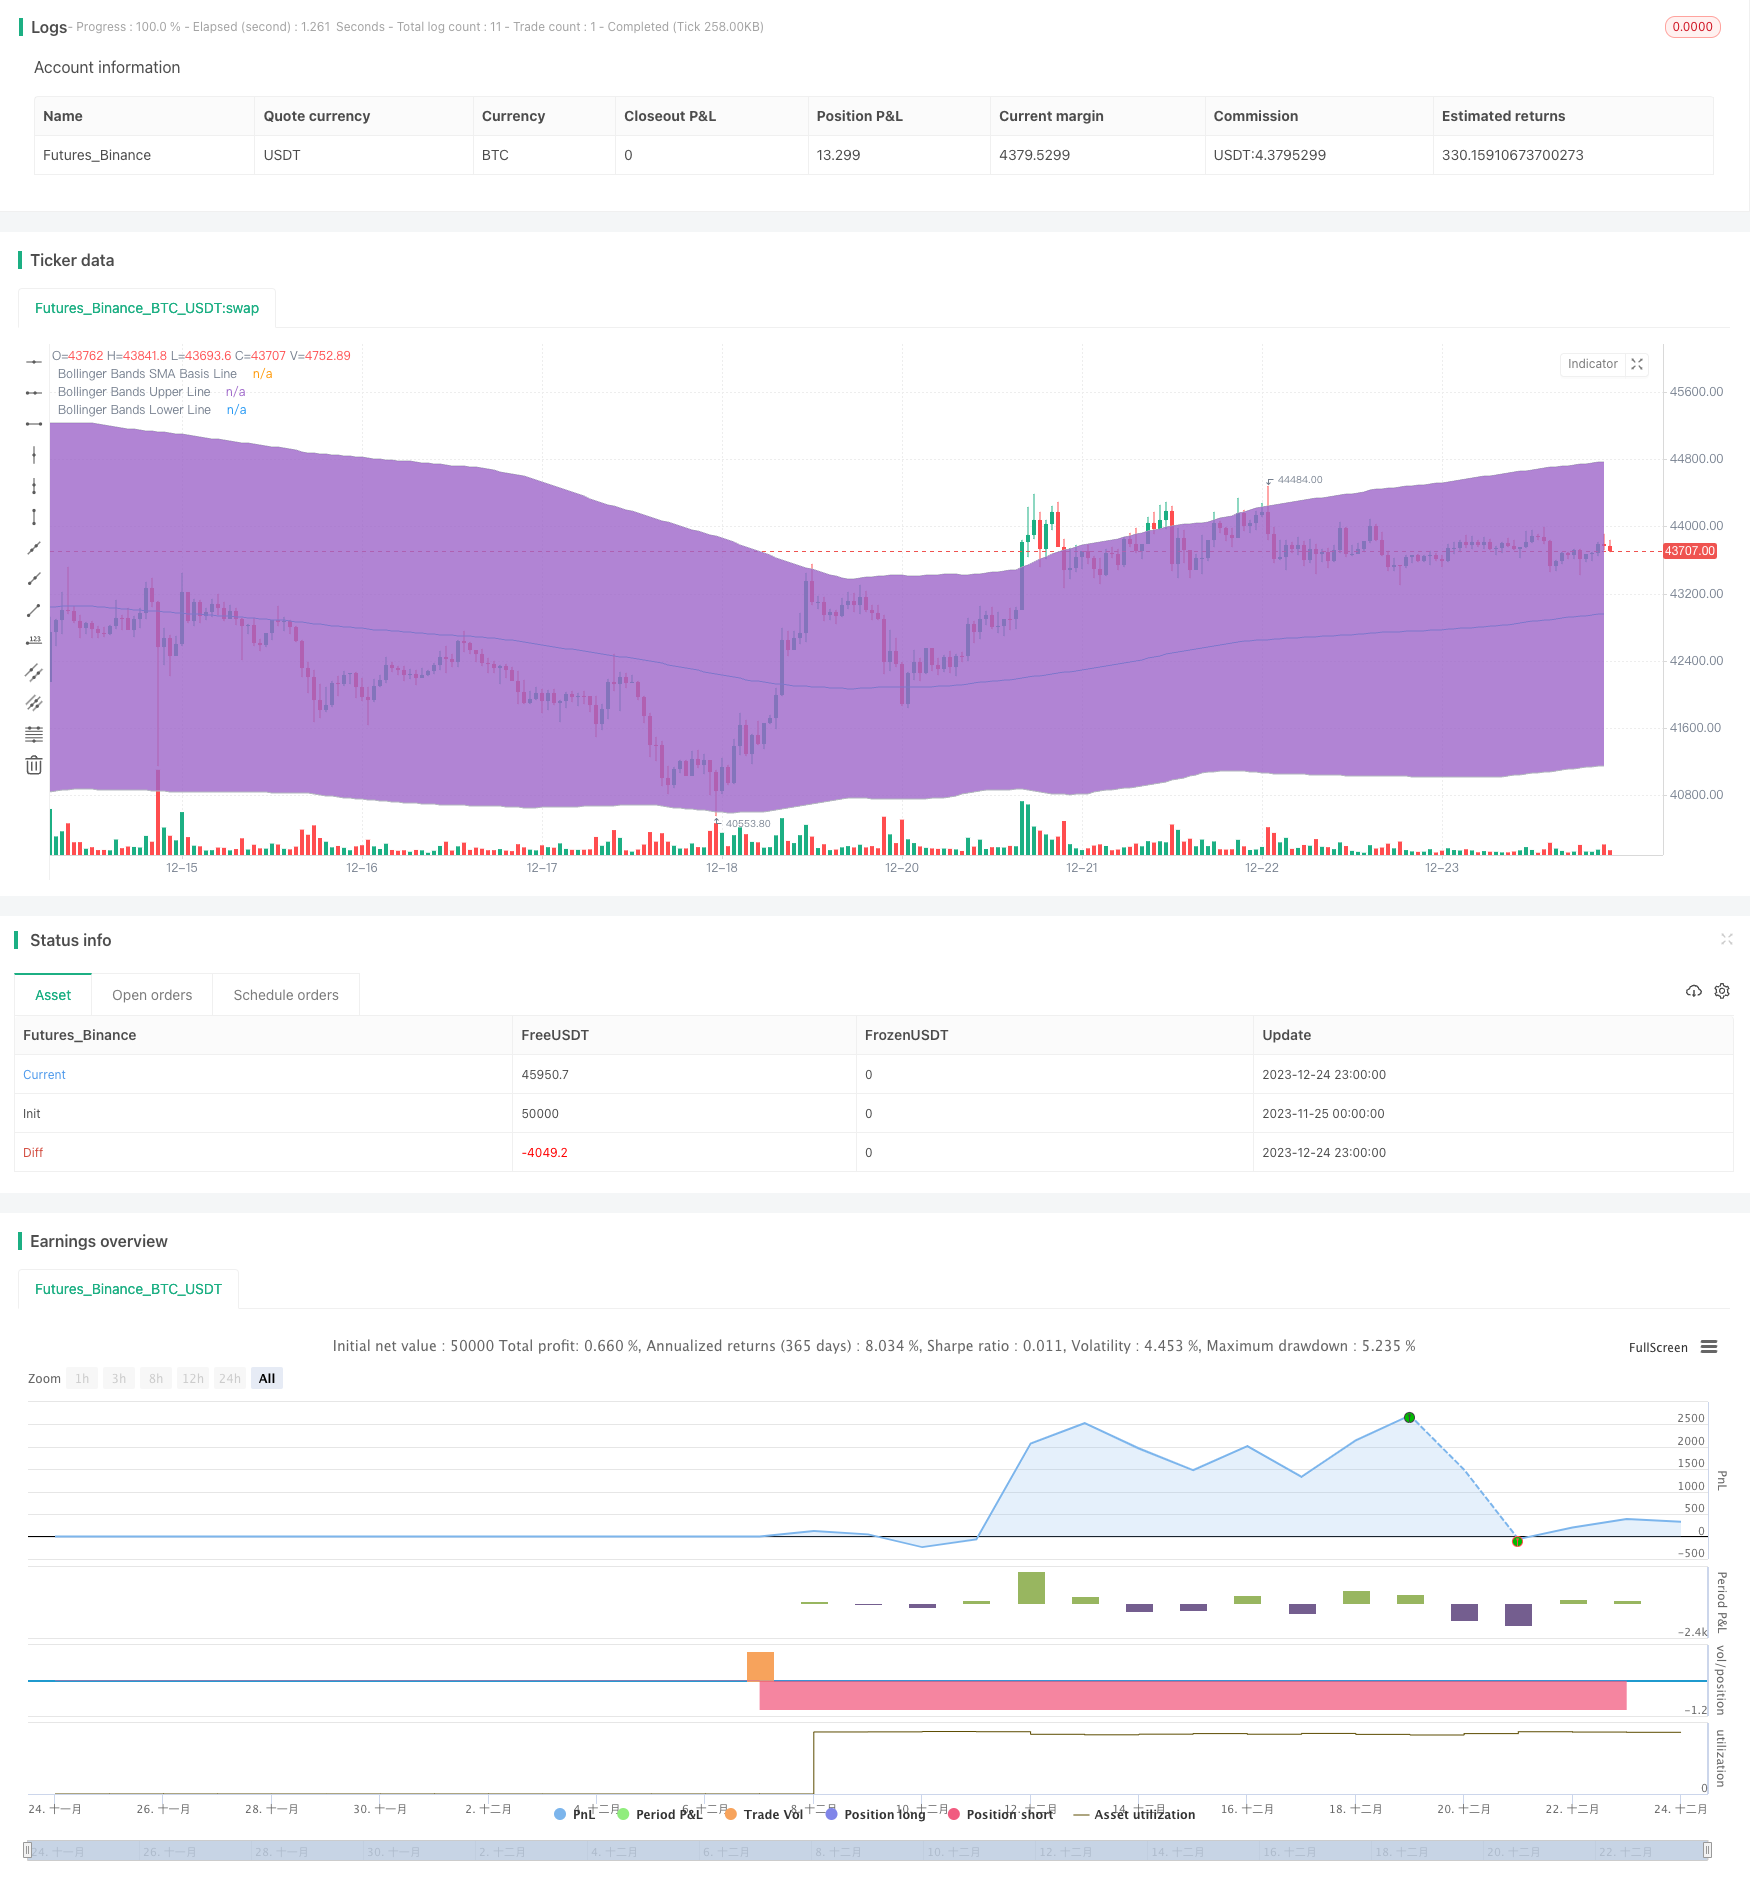
Overview
This strategy combines Bollinger Bands with the Relative Strength Index (RSI) indicator. It requires signals from both indicators - RSI overbought/oversold together with breakouts of Bollinger Bands upper/lower lines - before issuing any trading signals. This makes the strategy's signals more strict and reliable.
Strategy Logic
- Calculate Bollinger Bands consisting of middle line, upper line and lower line based on closing prices over a lookback period.
- Compute RSI indicator to judge if the market is overly bullish or bearish.
- Initiate short trade only when RSI shows overbought (higher than rsi_overbought parameter) and price breaks above Bollinger upper line.
- Initiate long trade only when RSI shows oversold (lower than rsi_oversold parameter) and price breaks below Bollinger lower line.
By requiring agreement from both Bollinger Bands and RSI, this strategy avoids acting on misleading signals from a single indicator, hence more reliable.
Advantages
- Utilizes strengths of both Bollinger Bands and RSI, making signals more strict and avoiding mistakes.
- Bollinger Bands set dynamic channels to capture market volatility patterns.
- RSI gauges overbought/oversold scenarios, preventing chasing peaks or killing dips.
Risks
- Improper Bollinger parameters may fail to envelop prices effectively.
- Improper RSI parameters may fail to judge real overbought/oversold conditions accurately.
- Strategy itself cannot determine trend direction, requiring other indicators.
To address the above risks, parameters should be optimized, models strictly tested, and major trends determined with additional indicators.
Optimization Directions
- Test Bollinger Bands with different lookback periods to find optimal parameters.
- Test different RSI parameters to determine relatively better settings.
- Add other indicators like moving averages to determine overall trend.
Conclusion
This strategy successfully combines the strengths of Bollinger Bands and RSI, issuing trading signals only when both indicators agree. This avoids acting on misleading signals from any single indicator, making trades more reliable. Nonetheless, parameters should be optimized, models strictly tested, and major trends determined with other indicators, to further enhance the strategy's stability and profitability.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 6 | RSI Period Length |
| v_input_2 | 200 | Bollinger Period Length |
| v_input_3 | true | Enable Bar Color? |
| v_input_4 | true | Enable Background Color? |
Source Pine Script
/*backtest
start: 2023-11-25 00:00:00
end: 2023-12-25 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=2
strategy("Bollinger + RSI, Double Strategy (by ChartArt) v1.1", shorttitle="CA_-_RSI_Bol_Strat_1.1", overlay=true)

// ChartArt's RSI + Bollinger Bands, Double Strategy - Update
//
// Version 1.1
// Idea by ChartArt on January 18, 2015.
//
// This strategy uses the RSI indicator
// together with the Bollinger Bands
// to sell when the price is above the
// upper Bollinger Band (and to buy when
// this value is below the lower band).
//
// This simple strategy only triggers when
// both the RSI and the Bollinger Bands
// indicators are at the same time in
// a overbought or oversold condition.
//
// In this version 1.1 the strategy was
// both simplified for the user and
// made more successful in backtesting.
//
// List of my work:
// https://www.tradingview.com/u/ChartArt/
//
//  __             __  ___       __  ___
// /  ` |__|  /\  |__)  |   /\  |__)  |
// \__, |  | /~~\ |  \  |  /~~\ |  \  |
//
//


///////////// RSI
RSIlength = input(6,title="RSI Period Length")
RSIoverSold = 50
RSIoverBought = 50
price = close
vrsi = rsi(price, RSIlength)


///////////// Bollinger Bands
BBlength = input(200, minval=1,title="Bollinger Period Length")
BBmult = 2 // input(2.0, minval=0.001, maxval=50,title="Bollinger Bands Standard Deviation")
BBbasis = sma(price, BBlength)
BBdev = BBmult * stdev(price, BBlength)
BBupper = BBbasis + BBdev
BBlower = BBbasis - BBdev
source = close
buyEntry = crossover(source, BBlower)
sellEntry = crossunder(source, BBupper)
plot(BBbasis, color=aqua,title="Bollinger Bands SMA Basis Line")
p1 = plot(BBupper, color=silver,title="Bollinger Bands Upper Line")
p2 = plot(BBlower, color=silver,title="Bollinger Bands Lower Line")
fill(p1, p2)


///////////// Colors
switch1=input(true, title="Enable Bar Color?")
switch2=input(true, title="Enable Background Color?")
TrendColor = RSIoverBought and (price[1] > BBupper and price < BBupper) and BBbasis < BBbasis[1] ? red : RSIoverSold and (price[1] < BBlower and price > BBlower) and BBbasis > BBbasis[1] ? green : na
barcolor(switch1?TrendColor:na)
bgcolor(switch2?TrendColor:na,transp=50)


///////////// RSI + Bollinger Bands Strategy
if (not na(vrsi))

    if (crossover(vrsi, RSIoverSold) and crossover(source, BBlower))
        strategy.entry("RSI_BB_L", strategy.long, stop=BBlower,  comment="RSI_BB_L")
    else
        strategy.cancel(id="RSI_BB_L")

    if (crossunder(vrsi, RSIoverBought) and crossunder(source, BBupper))
        strategy.entry("RSI_BB_S", strategy.short, stop=BBupper,  comment="RSI_BB_S")
    else
        strategy.cancel(id="RSI_BB_S")

//plot(strategy.equity, title="equity", color=red, linewidth=2, style=areabr)Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-26. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Bollinger-Band-RSI-Dual-Line-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bollinger Band Channel Breakout Trading StrategyPine Script · Breakout · 1d
- Bollinger Bands Dynamic Breakout StrategyPine Script · Breakout · 1h
- Cross boundary Dynamic Range Quantitative Trading Strategy Based on Bollinger BandsPine Script · Breakout · 3h
- EMA and Bollinger Bands Breakout StrategyPine Script · Breakout · 1h
- Momentum Breakout Moving Average StrategyPine Script · Breakout · 1d
- Momentum Breakout Trading Strategy 440964Pine Script · Breakout · 5m