Bollinger Bands Breakout short term trend following Strategy
The Bollinger Bands Breakout Strategy is a short-term trend following strategy optimized for crypto trading. It utilizes the well-established Bollinger Bands indicator as the core signal generator and is capable of…
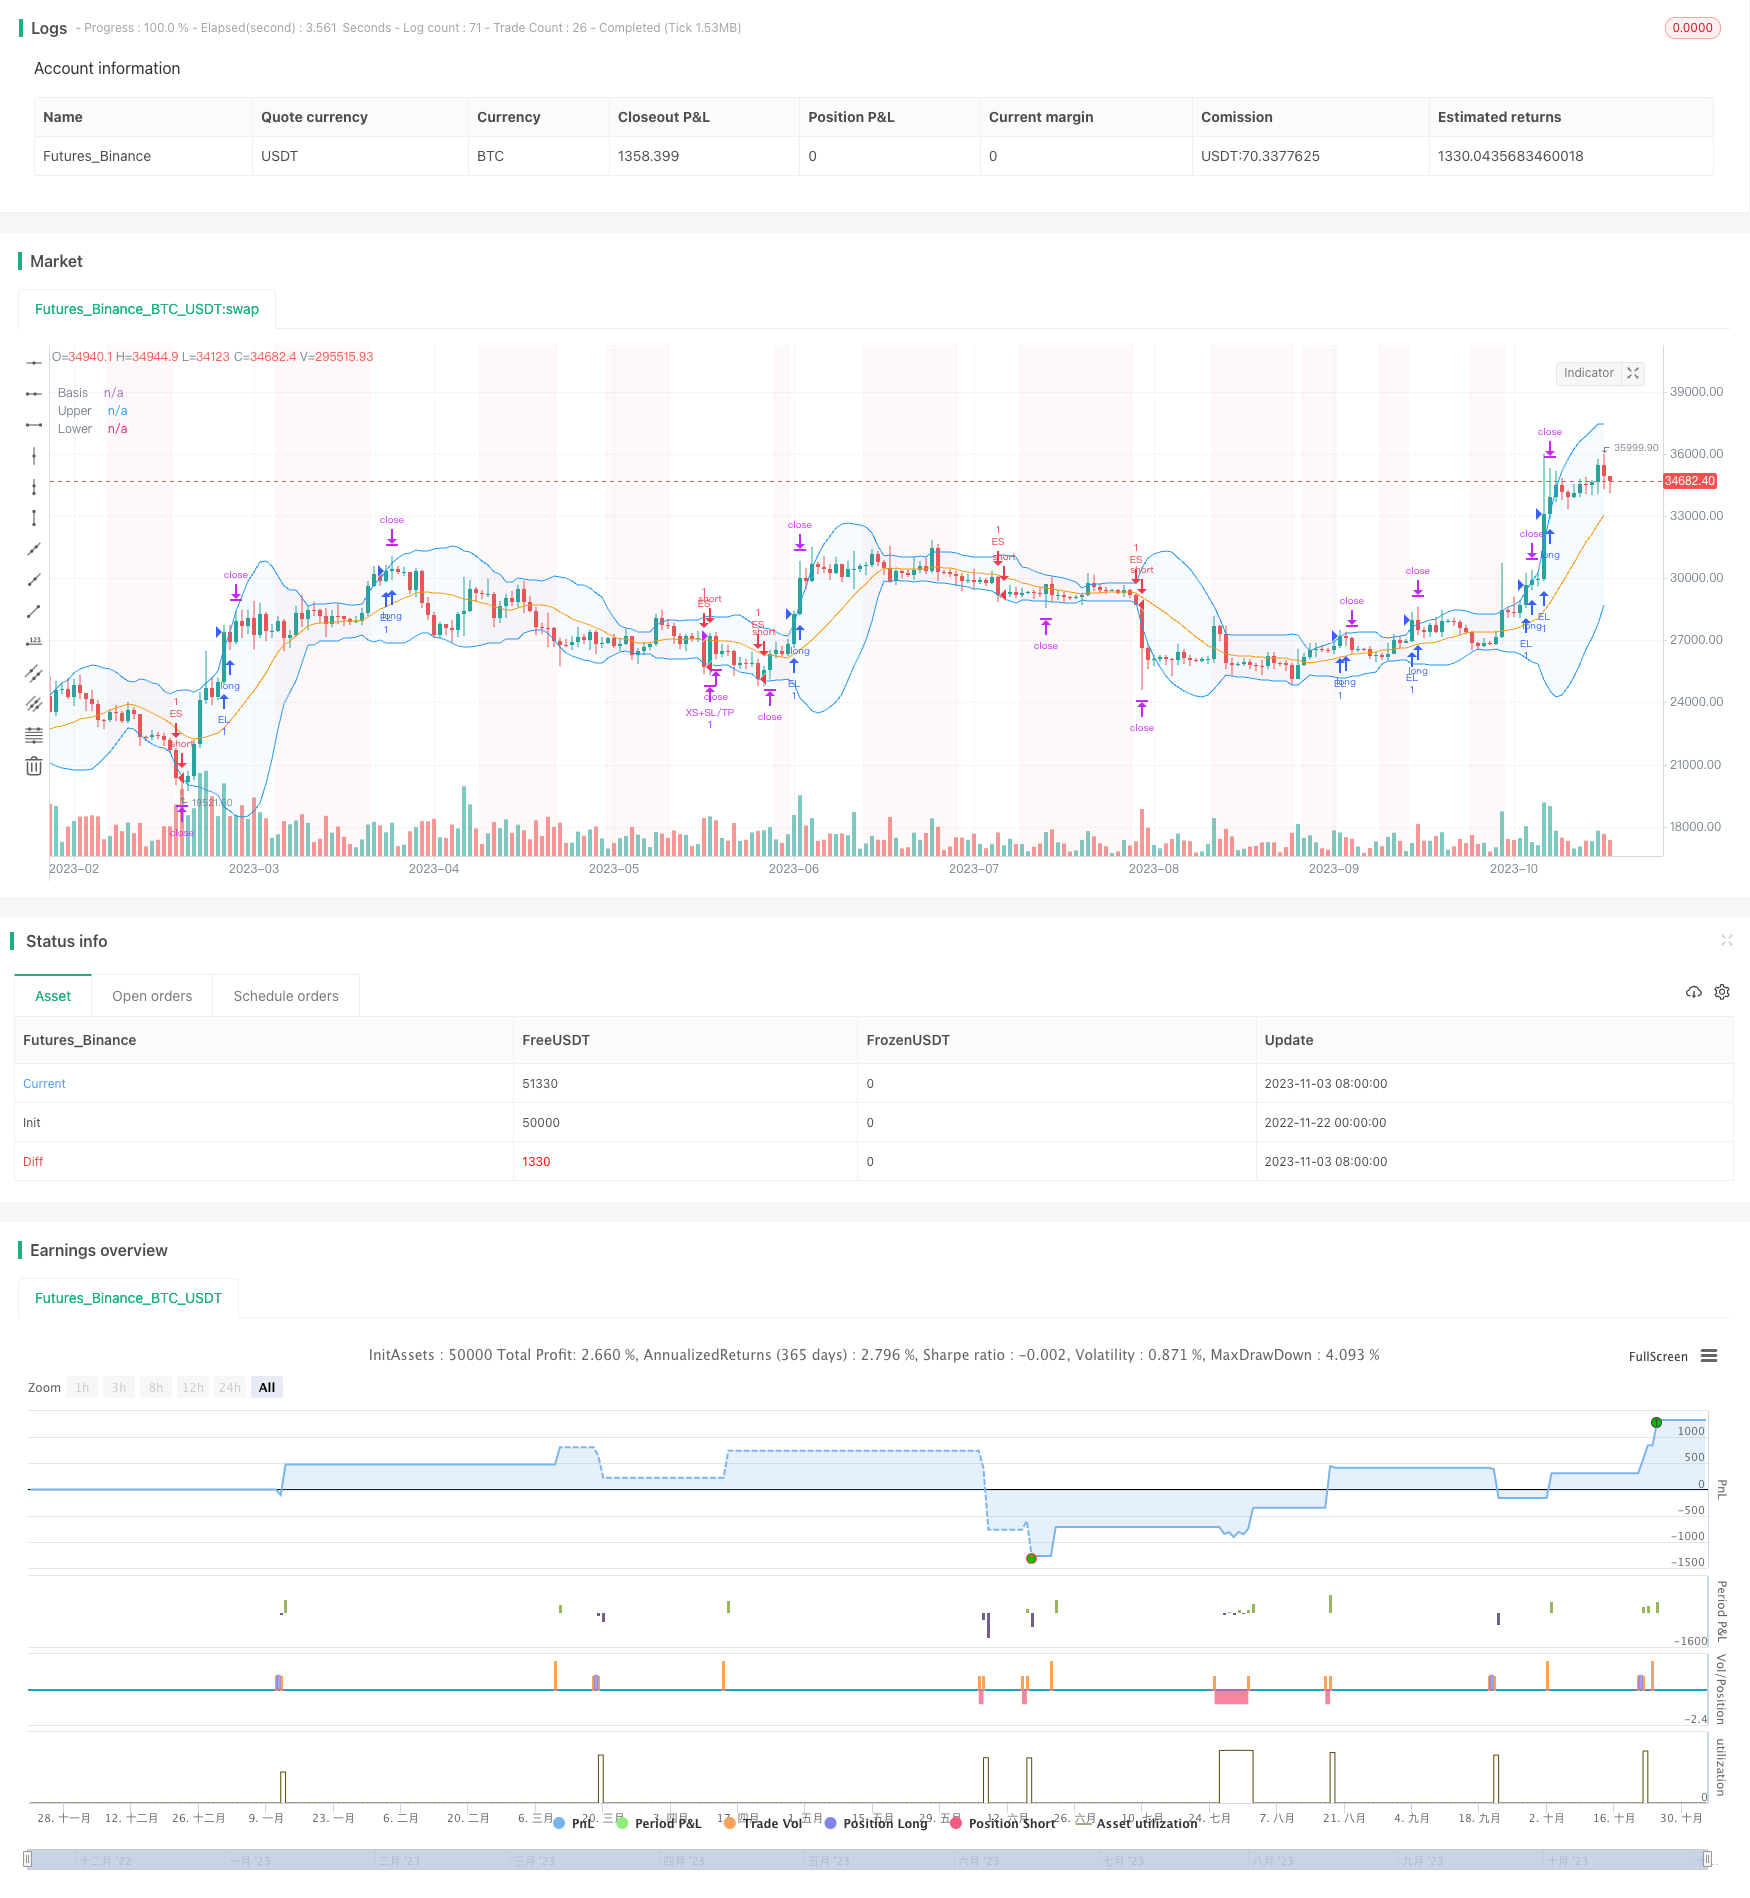
Overview
The Bollinger Bands Breakout Strategy is a short-term trend following strategy optimized for crypto trading. It utilizes the well-established Bollinger Bands indicator as the core signal generator and is capable of taking both long and short positions. With comprehensive risk management mechanisms, it is a robust automated trading system suitable for trending markets.
The strategy features a high level of configurability, including the Bollinger Bands parameters, various filters, take profit/stop loss settings and maximum intraday loss threshold. This adaptability empowers the strategy to achieve reliable performance across various market regimes.
How It Works
The strategy centres around the Bollinger Bands indicator, which calculates a middle band, an upper band and a lower band that serve as proxies for price averages and volatility limits. The crossing of price over the upper or lower bands generates entry signals – long when price breaks above upper band, short when below lower band.
In addition, multiple filters are implemented to avoid false signals:
Trend Filter: long above moving average, short below moving average
Volatility Filter: only trade when volatility expands
Direction Filter: configurable for long-only, short-only or both directions
Rate of Change Filter: sufficient price movement from previous close required
Date Filter: for backtesting timeframe specification
Exits are handled through take profit, stop loss and trailing stop mechanisms to lock in gains and limit losses. Maximum intraday loss threshold provides another layer of daily drawdown protection.
Advantages
The main advantages of this strategy include:
Reliable Bollinger Bands indicator as core signal
Customizable filters prevent unwanted trades
Comprehensive stop loss/take profit design
Max intraday loss guards against extreme drawdown
Thrives in trending markets with profit potential
Risks
Despite the advantages, some risks remain:
Whipsaws around Bollinger Bands may lead to losses
Too rigid filters reduce trades in range-bound markets
Gaps can stop out positions preemptively
Extreme moves cannot be fully avoided
Mitigations include adjusting filters, manual intervention and tweaked stops.
Enhancement Opportunities
Possible optimizations for this strategy:
Search for optimal parameter combinations
Introduce machine learning for adaptive optimization
Research better stop loss methods e.g. volatility stops
Incorporate sentiment to guide discretionary actions
Utilize correlated instruments for statistical arbitrage
Conclusion
The Bollinger Bands Breakout Strategy is a time-tested system for short-term trend trading. By combining the merits of Bollinger Bands signal and prudent filters, it generates quality entries for trends while avoiding false signals. Comprehensive risk management mechanisms also contain drawdowns effectively. With continuous improvements, this strategy has the potential to become a formidable automated trading system.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_int_1 | 15 | (?Bollinger Bands)Length |
| v_input_float_1 | 2 | StdDev |
| v_input_bool_1 | false | (?Trend Filter)Above/Below |
| v_input_1 | 223 | trendFilterPeriodInput |
| v_input_string_1 | 0 | trendFilterType: EMA | SMA | RMA | WMA |
| v_input_bool_2 | true | (?Volatility Filter)StdDev |
| v_input_2 | 15 | volatilityFilterStDevLength |
| v_input_3 | 15 | >MA |
| v_input_bool_3 | false | (?ROC Filter from CloseD)roc_enable |
| v_input_float_2 | true | Treshold |
| v_input_4 | timestamp(2017-01-01) | (?Date Filter)Start |
| v_input_5 | timestamp(2050-01-01) | End |
| v_input_float_3 | 2 | (?Exit Long)TS |
| v_input_float_4 | 0.5 | TO |
| v_input_float_5 | 2 | SL |
| v_input_float_6 | 9 | TP |
| v_input_float_7 | 2 | (?Exit Short)TS |
| v_input_float_8 | 0.5 | TO |
| v_input_float_9 | 2 | SL |
| v_input_float_10 | 9 | TP |
| v_input_int_2 | 10 | (?Risk Management)Max Intraday Loss (Percent) |
| v_input_6 | 2 | (?Results Table)Precision |
| v_input_bool_4 | true | Dark Mode |
Source Pine Script
/*backtest
start: 2022-11-22 00:00:00
end: 2023-11-04 05:20:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/


//@version=5
strategy("Bollinger Bands - Breakout Strategy",overlay=true
         )


// Define the length of the Bollinger Bands
bbLengthInput = input.int (15,title="Length", group="Bollinger Bands", inline="BB")
bbDevInput = input.float (2.0,title="StdDev", group="Bollinger Bands", inline="BB")

// Define the settings for the Trend Filter
trendFilterInput = input.bool(false, title="Above/Below", group = "Trend Filter", inline="Trend")
trendFilterPeriodInput = input(223,title="", group = "Trend Filter", inline="Trend")
trendFilterType = input.string (title="", defval="EMA",options=["EMA","SMA","RMA", "WMA"], group = "Trend Filter", inline="Trend")

volatilityFilterInput = input.bool(true,title="StdDev", group = "Volatility Filter", inline="Vol")
volatilityFilterStDevLength = input(15,title="",group = "Volatility Filter", inline="Vol")
volatilityStDevMaLength = input(15,title=">MA",group = "Volatility Filter", inline="Vol")

// ROC Filter

// f_security function by LucF for PineCoders available here: https://www.tradingview.com/script/cyPWY96u-How-to-avoid-repainting-when-using-security-PineCoders-FAQ/
f_security(_sym, _res, _src, _rep) => request.security(_sym, _res, _src[not _rep and barstate.isrealtime ? 1 : 0])[_rep or barstate.isrealtime ? 0 : 1]
high_daily = f_security(syminfo.tickerid, "D", high, false)

roc_enable = input.bool(false, "", group="ROC Filter from CloseD", inline="roc")
roc_threshold = input.float(1, "Treshold", step=0.5, group="ROC Filter from CloseD", inline="roc")

closed = f_security(syminfo.tickerid,"1D",close, false)
roc_filter= roc_enable ? (close-closed)/closed*100  > roc_threshold : true

// Trade Direction Filter

// tradeDirectionInput = input.string("Auto",options=["Auto", "Long&Short","Long Only", "Short Only"], title="Trade", group="Direction Filter", tooltip="Auto: if a PERP is detected (in the symbol description), trade long and short\n Otherwise as per user-input")

// tradeDirection = switch tradeDirectionInput
// 	"Auto" => str.contains(str.lower(syminfo.description), "perp") or str.contains(str.lower(syminfo.description), ".p") ? strategy.direction.all : strategy.direction.long
// 	"Long&Short" => strategy.direction.all
// 	"Long Only" => strategy.direction.long
//     "Short Only" => strategy.direction.short
// 	=> strategy.direction.all

// strategy.risk.allow_entry_in(tradeDirection)


// Calculate and plot the Bollinger Bands
[bbMiddle, bbUpper, bbLower] = ta.bb (close, bbLengthInput, bbDevInput)

plot(bbMiddle, "Basis", color=color.orange)
bbUpperPlot = plot(bbUpper, "Upper", color=color.blue)
bbLowerrPlot = plot(bbLower, "Lower", color=color.blue)
fill(bbUpperPlot, bbLowerrPlot, title = "Background", color=color.new(color.blue, 95))


// Calculate and view Trend Filter

float tradeConditionMa = switch trendFilterType
	"EMA" => ta.ema(close, trendFilterPeriodInput)
	"SMA" => ta.sma(close, trendFilterPeriodInput)
	"RMA" => ta.rma(close, trendFilterPeriodInput)
    "WMA" => ta.wma(close, trendFilterPeriodInput)
	// Default used when the three first cases do not match.
	=> ta.wma(close, trendFilterPeriodInput)


trendConditionLong  = trendFilterInput ? close > tradeConditionMa : true
trendConditionShort = trendFilterInput ? close < tradeConditionMa : true
plot(trendFilterInput ? tradeConditionMa : na, color=color.yellow)

// Calculate and view Volatility Filter

stdDevClose = ta.stdev(close,volatilityFilterStDevLength)
volatilityCondition = volatilityFilterInput ? stdDevClose > ta.sma(stdDevClose,volatilityStDevMaLength) : true

bbLowerCrossUnder =  ta.crossunder(close, bbLower)
bbUpperCrossOver =  ta.crossover(close, bbUpper)

bgcolor(volatilityCondition ? na : color.new(color.red, 95))


// Date Filter

start = input(timestamp("2017-01-01"), "Start", group="Date Filter")
finish = input(timestamp("2050-01-01"), "End", group="Date Filter")

date_filter = true

// Entry and Exit Conditions

entryLongCondition = bbUpperCrossOver and trendConditionLong and volatilityCondition and date_filter and roc_filter
entryShortCondition = bbLowerCrossUnder and trendConditionShort and volatilityCondition and date_filter and roc_filter

exitLongCondition = bbLowerCrossUnder
exitShortCondition = bbUpperCrossOver

// Orders

if entryLongCondition
    strategy.entry("EL", strategy.long)

if entryShortCondition
    strategy.entry("ES", strategy.short)

if exitLongCondition
    strategy.close("EL")

if exitShortCondition
    strategy.close("ES")


// Long SL/TP/TS

xl_ts_percent      = input.float(2,step=0.5, title= "TS", group="Exit Long", inline="LTS", tooltip="Trailing Treshold %")
xl_to_percent      = input.float(0.5, step=0.5, title= "TO", group="Exit Long", inline="LTS", tooltip="Trailing Offset %")

xl_ts_tick = xl_ts_percent * close/syminfo.mintick/100
xl_to_tick = xl_to_percent * close/syminfo.mintick/100

xl_sl_percent      = input.float (2, step=0.5, title="SL",group="Exit Long", inline="LSLTP")
xl_tp_percent      = input.float(9, step=0.5, title="TP",group="Exit Long", inline="LSLTP")

xl_sl_price = strategy.position_avg_price * (1-xl_sl_percent/100)
xl_tp_price = strategy.position_avg_price * (1+xl_tp_percent/100)

strategy.exit("XL+SL/TP", "EL", stop=xl_sl_price, limit=xl_tp_price, trail_points=xl_ts_tick, trail_offset=xl_to_tick,comment_loss= "XL-SL", comment_profit = "XL-TP",comment_trailing = "XL-TS")

// Short SL/TP/TS
xs_ts_percent      = input.float(2,step=0.5, title= "TS",group="Exit Short", inline ="STS", tooltip="Trailing Treshold %")
xs_to_percent      = input.float(0.5, step=0.5, title= "TO",group="Exit Short", inline ="STS", tooltip="Trailing Offset %")

xs_ts_tick = xs_ts_percent * close/syminfo.mintick/100
xs_to_tick = xs_to_percent * close/syminfo.mintick/100

xs_sl_percent      = input.float (2, step=0.5, title="SL",group="Exit Short", inline="ESSLTP", tooltip="Stop Loss %")
xs_tp_percent      = input.float(9, step=0.5, title="TP",group="Exit Short",  inline="ESSLTP", tooltip="Take Profit %")

xs_sl_price = strategy.position_avg_price * (1+xs_sl_percent/100)
xs_tp_price = strategy.position_avg_price * (1-xs_tp_percent/100)

strategy.exit("XS+SL/TP", "ES", stop=xs_sl_price, limit=xs_tp_price, trail_points=xs_ts_tick, trail_offset=xs_to_tick,comment_loss= "XS-SL", comment_profit = "XS-TP",comment_trailing = "XS-TS")


max_intraday_loss = input.int(10, title="Max Intraday Loss (Percent)", group="Risk Management")

//strategy.risk.max_intraday_loss(max_intraday_loss, strategy.percent_of_equity)

// Monthly Returns table, modified from QuantNomad. Please put calc_on_every_tick = true to plot it.

monthly_table(int results_prec, bool results_dark) =>
    new_month = month(time) != month(time[1])
    new_year  = year(time)  != year(time[1])

    eq = strategy.equity

    bar_pnl = eq / eq[1] - 1

    cur_month_pnl = 0.0
    cur_year_pnl  = 0.0

    // Current Monthly P&L
    cur_month_pnl := new_month ? 0.0 :
                     (1 + cur_month_pnl[1]) * (1 + bar_pnl) - 1

    // Current Yearly P&L
    cur_year_pnl := new_year ? 0.0 :
                     (1 + cur_year_pnl[1]) * (1 + bar_pnl) - 1

    // Arrays to store Yearly and Monthly P&Ls
    var month_pnl  = array.new_float(0)
    var month_time = array.new_int(0)

    var year_pnl  = array.new_float(0)
    var year_time = array.new_int(0)

    last_computed = false

    if (not na(cur_month_pnl[1]) and (new_month or barstate.islast))
        if (last_computed[1])
            array.pop(month_pnl)
            array.pop(month_time)

        array.push(month_pnl , cur_month_pnl[1])
        array.push(month_time, time[1])

    if (not na(cur_year_pnl[1]) and (new_year or barstate.islast))
        if (last_computed[1])
            array.pop(year_pnl)
            array.pop(year_time)

        array.push(year_pnl , cur_year_pnl[1])
        array.push(year_time, time[1])

    last_computed := barstate.islast ? true : nz(last_computed[1])

    // Monthly P&L Table
    var monthly_table = table(na)

    cell_hr_bg_color = results_dark ? #0F0F0F : #F5F5F5
    cell_hr_text_color = results_dark ? #D3D3D3 : #555555
    cell_border_color = results_dark ? #000000 : #FFFFFF

    // ell_hr_bg_color = results_dark ? #0F0F0F : #F5F5F5
    // cell_hr_text_color = results_dark ? #D3D3D3 : #555555
    // cell_border_color = results_dark ? #000000 : #FFFFFF
    if (barstate.islast)
        monthly_table := table.new(position.bottom_right, columns = 14, rows = array.size(year_pnl) + 1, bgcolor=cell_hr_bg_color,border_width=1,border_color=cell_border_color)

        table.cell(monthly_table, 0,  0, syminfo.tickerid + " " + timeframe.period,     text_color=cell_hr_text_color, bgcolor=cell_hr_bg_color)
        table.cell(monthly_table, 1,  0, "Jan",  text_color=cell_hr_text_color, bgcolor=cell_hr_bg_color)
        table.cell(monthly_table, 2,  0, "Feb",  text_color=cell_hr_text_color, bgcolor=cell_hr_bg_color)
        table.cell(monthly_table, 3,  0, "Mar",  text_color=cell_hr_text_color, bgcolor=cell_hr_bg_color)
        table.cell(monthly_table, 4,  0, "Apr",  text_color=cell_hr_text_color, bgcolor=cell_hr_bg_color)
        table.cell(monthly_table, 5,  0, "May",  text_color=cell_hr_text_color, bgcolor=cell_hr_bg_color)
        table.cell(monthly_table, 6,  0, "Jun",  text_color=cell_hr_text_color, bgcolor=cell_hr_bg_color)
        table.cell(monthly_table, 7,  0, "Jul",  text_color=cell_hr_text_color, bgcolor=cell_hr_bg_color)
        table.cell(monthly_table, 8,  0, "Aug",  text_color=cell_hr_text_color, bgcolor=cell_hr_bg_color)
        table.cell(monthly_table, 9,  0, "Sep",  text_color=cell_hr_text_color, bgcolor=cell_hr_bg_color)
        table.cell(monthly_table, 10, 0, "Oct",  text_color=cell_hr_text_color, bgcolor=cell_hr_bg_color)
        table.cell(monthly_table, 11, 0, "Nov",  text_color=cell_hr_text_color, bgcolor=cell_hr_bg_color)
        table.cell(monthly_table, 12, 0, "Dec",  text_color=cell_hr_text_color, bgcolor=cell_hr_bg_color)
        table.cell(monthly_table, 13, 0, "Year", text_color=cell_hr_text_color, bgcolor=cell_hr_bg_color)

        for yi = 0 to array.size(year_pnl) - 1
            table.cell(monthly_table, 0,  yi + 1, str.tostring(year(array.get(year_time, yi))), text_color=cell_hr_text_color, bgcolor=cell_hr_bg_color)

            y_color = array.get(year_pnl, yi) > 0 ? color.lime :  array.get(year_pnl, yi) < 0 ? color.red : color.gray
            table.cell(monthly_table, 13, yi + 1, str.tostring(math.round(array.get(year_pnl, yi) * 100, results_prec)), bgcolor = y_color)

        for mi = 0 to array.size(month_time) - 1
            m_row   = year(array.get(month_time, mi))  - year(array.get(year_time, 0)) + 1
            m_col   = month(array.get(month_time, mi))
            m_color = array.get(month_pnl, mi) > 0 ? color.lime : array.get(month_pnl, mi) < 0 ? color.red : color.gray

            table.cell(monthly_table, m_col, m_row, str.tostring(math.round(array.get(month_pnl, mi) * 100, results_prec)), bgcolor = m_color)

results_prec = input(2, title = "Precision", group="Results Table")
results_dark = input.bool(defval=true, title="Dark Mode", group="Results Table")
monthly_table(results_prec, results_dark)Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-23. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Bollinger-Bands-Breakout-short-term-trend-following-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- BB Breakout StrategyPine Script · Breakout · 1d
- Bollinger Band T3 Moving Average StrategyPine Script · Breakout · 10m
- Bollinger Bands Dual track Breakthrough StrategyPine Script · Breakout · 30m
- Bollinger Breakout StrategyPine Script · Breakout · 30m
- Dynamic Bollinger Bands Breakout Quantitative Trading StrategyPine Script · Breakout · 2d
- EMA and Bollinger Bands Breakout StrategyPine Script · Breakout · 1h