Bollinger Bands Channel Breakout Mean Reversion Strategy
This is a mean reversion breakout strategy based on the Bollinger Bands channel. It goes long when the price breaks below the lower band of the Bollinger Bands. The stop loss is set at the low of the breakout bar…
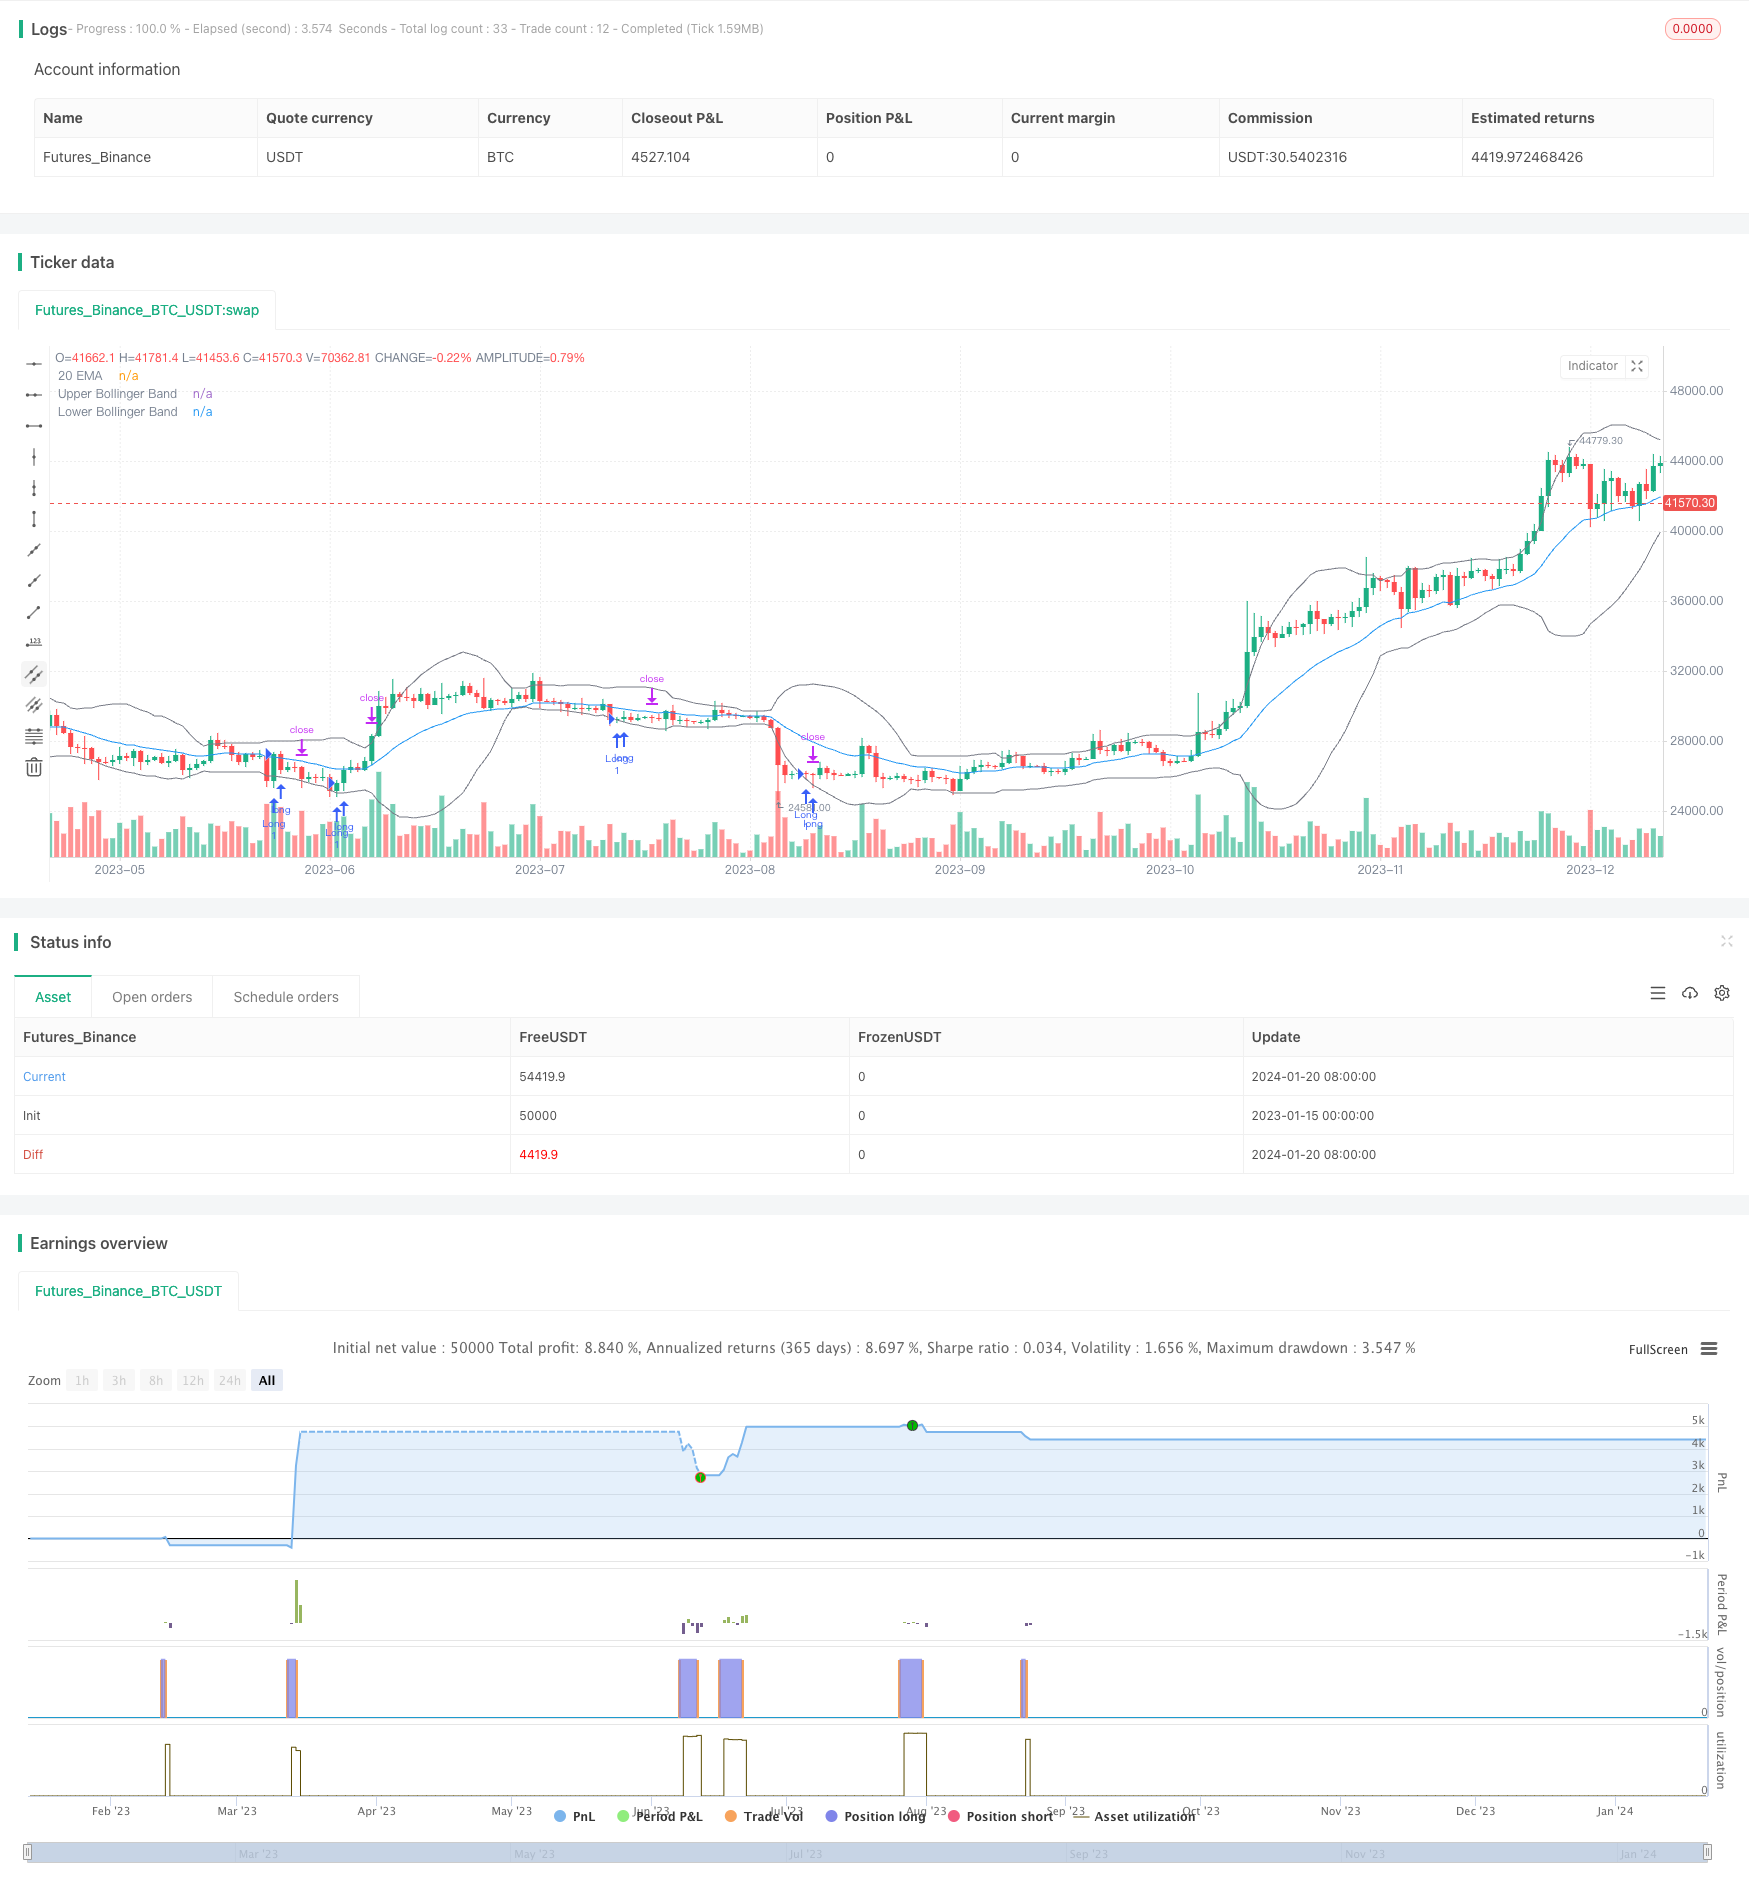
Overview
This is a mean reversion breakout strategy based on the Bollinger Bands channel. It goes long when the price breaks below the lower band of the Bollinger Bands. The stop loss is set at the low of the breakout bar. The profit target is the upper band of the Bollinger Bands.
Strategy Logic
The strategy uses a 20-period Bollinger Bands channel, which consists of a middle band, an upper band and a lower band. The middle band is a 20-period simple moving average. The upper band is the middle band plus 2 standard deviations. The lower band is the middle band minus 2 standard deviations.
When the price breaks below the lower band, it indicates the price has entered an oversold status. The strategy will go long at this point. After entering the position, the stop loss is set at the low of the entry bar, and the profit target is the upper band. Thus the strategy aims to capture the reversion process from oversold to the mean, in order to make profits.
Advantage Analysis
The advantages of this strategy are:
- Use Bollinger Bands to judge overbought/oversold status, which has some timeliness
- Reversion trading strategy, avoiding chasing highs and killing lows
- Reasonable stop loss and take profit setting for better risk control
Risk Analysis
The risks of this strategy include:
- Bollinger Bands cannot perfectly determine price trends, breakouts may fail
- Continous market crash may hit stop loss
- Take profit near upper band has the risk of high cost
Optimization Directions
The strategy can be improved from the following aspects:
- Optimize parameters of Bollinger Bands to find the best combination
- Add filter indicators to improve entry accuracy
- Optimize stop loss and take profit for higher profitability
Conclusion
The strategy has clear logic and is tradable to some extent. However, its effectiveness in judging overbought/oversold with Bollinger Bands is limited, and it cannot perfectly determine the trend. Also, the stop loss and take profit mechanism needs improvement. Going forwards, it can be optimized by choosing more accurate indicators, tuning parameters, and enhancing the exit logic to improve profitability.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_int_1 | 20 | Bollinger Bands Length |
| v_input_float_1 | 2 | Multiplier |
| v_input_3_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_bool_1 | true | (?Backtest Time Period)Filter Date Range of Backtest |
| v_input_1 | timestamp(1 Jan 1997) | Start Date |
| v_input_2 | timestamp(1 Sept 2023) | End Date |
Source Pine Script
/*backtest
start: 2023-01-15 00:00:00
end: 2024-01-21 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © Ronsword
//@version=5

strategy("bb 2ND target", overlay=true)

// STEP 1. Create inputs that configure the backtest's date range
useDateFilter = input.bool(true, title="Filter Date Range of Backtest",
     group="Backtest Time Period")
backtestStartDate = input(timestamp("1 Jan 1997"),
     title="Start Date", group="Backtest Time Period",
     tooltip="This start date is in the time zone of the exchange " +
     "where the chart's instrument trades. It doesn't use the time " +
     "zone of the chart or of your computer.")
backtestEndDate = input(timestamp("1 Sept 2023"),
     title="End Date", group="Backtest Time Period",
     tooltip="This end date is in the time zone of the exchange " +
     "where the chart's instrument trades. It doesn't use the time " +
     "zone of the chart or of your computer.")

// STEP 2. See if the current bar falls inside the date range
inTradeWindow = true

// Bollinger Bands inputs
length = input.int(20, title="Bollinger Bands Length")
mult = input.float(2.0, title="Multiplier")
src = input(close, title="Source")
basis = ta.sma(src, length)
dev = mult * ta.stdev(src, length)
upper = basis + dev
lower = basis - dev

// EMA Settings
ema20 = ta.ema(close, 20)
plot(ema20, color=color.blue, title="20 EMA")

// Entry condition
longEntryCondition = ta.crossover(close, lower)

// Define stop loss level as the low of the entry bar
var float stopLossPrice = na
if longEntryCondition
    stopLossPrice := low

// Top Bollinger Band itself is set as the target
topBandTarget = upper

// Enter long position when conditions are met
if inTradeWindow and longEntryCondition
    strategy.entry("Long", strategy.long, qty=1)

// Set profit targets
strategy.exit("ProfitTarget2", from_entry="Long", limit=topBandTarget)

// Set stop loss
strategy.exit("StopLoss", stop=stopLossPrice)

// Plot Bollinger Bands with the same gray color
plot(upper, color=color.gray, title="Upper Bollinger Band")
plot(lower, color=color.gray, title="Lower Bollinger Band")
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-22. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Bollinger-Bands-Channel-Breakout-Mean-Reversion-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- BB Breakout StrategyPine Script · Breakout · 1d
- Bollinger Band T3 Moving Average StrategyPine Script · Breakout · 10m
- Bollinger Bands Dual track Breakthrough StrategyPine Script · Breakout · 30m
- Bollinger Breakout StrategyPine Script · Breakout · 30m
- Dynamic Bollinger Bands Breakout Quantitative Trading StrategyPine Script · Breakout · 2d
- EMA and Bollinger Bands Breakout StrategyPine Script · Breakout · 1h