CBMA Bollinger Bands Breaker Strategy
This strategy uses CBMA as the major technical indicator combined with Bollinger Bands to identify market trends and implement a breaker strategy. It goes short when price breaks above the upper band and goes long…
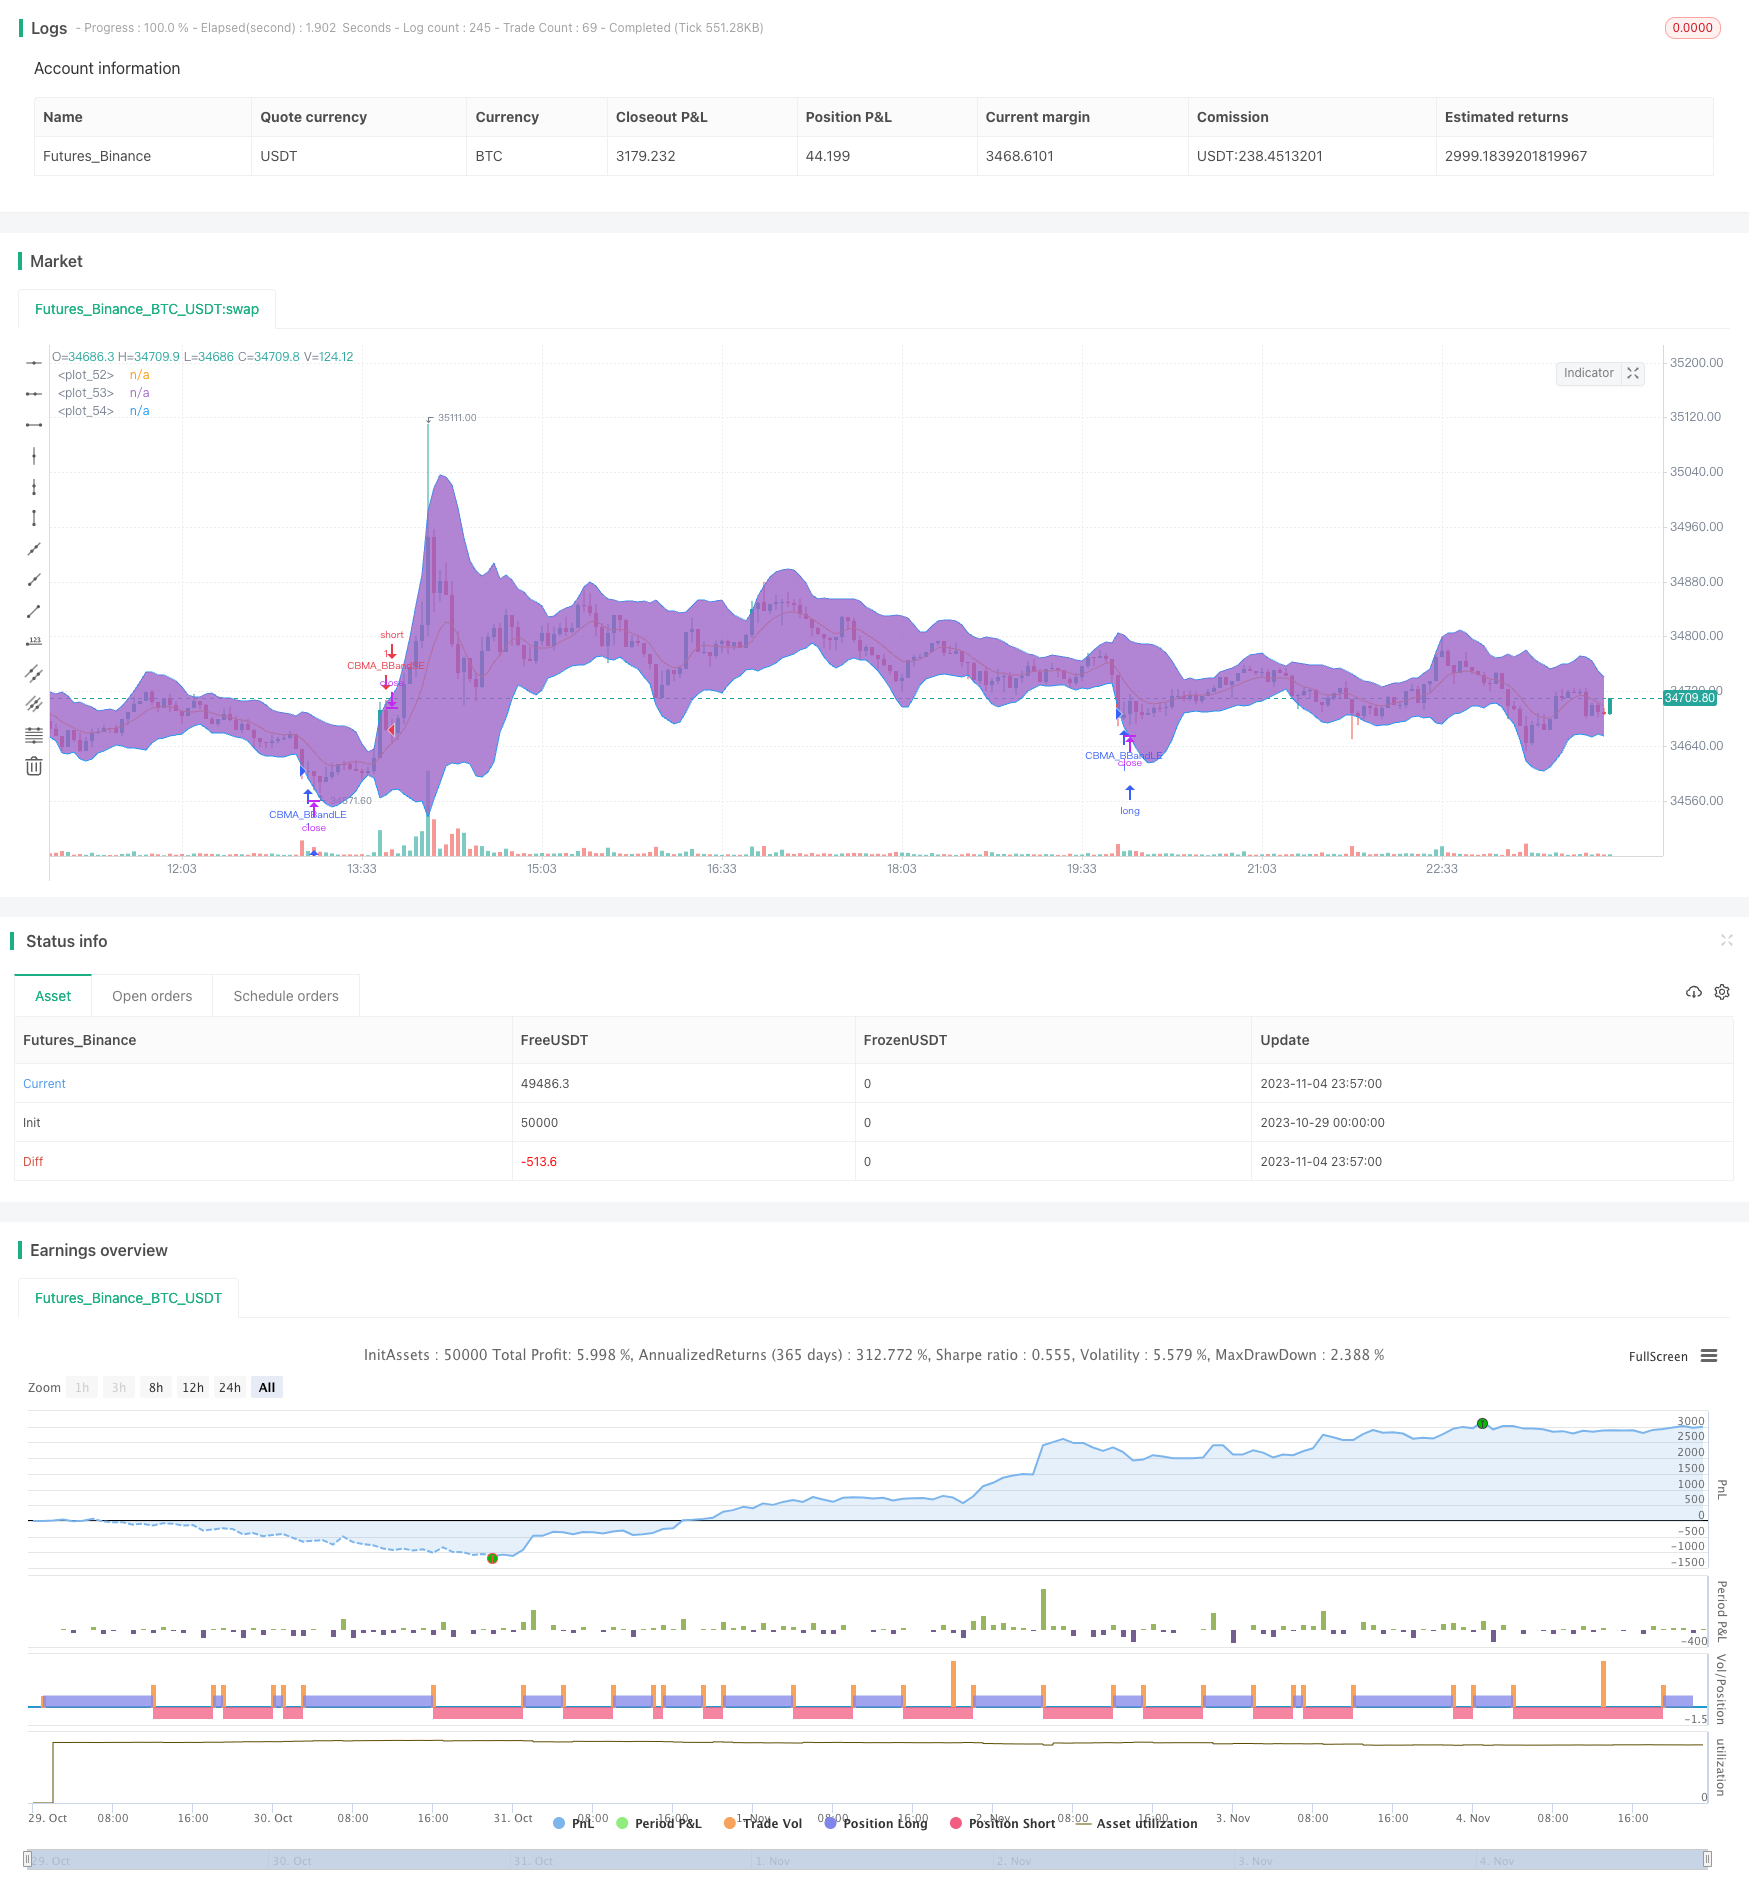
Overview
This strategy uses CBMA as the major technical indicator combined with Bollinger Bands to identify market trends and implement a breaker strategy. It goes short when price breaks above the upper band and goes long when price breaks below the lower band, belonging to the popular dual-track breakout system.
Strategy Logic
Calculate CBMA: Use adaptive EMA to smooth CBMA which can track price changes effectively.
Set Bollinger Bands parameters: Use CBMA as middle band, and set upper/lower bands using standard deviation multiplier, which can be adjusted based on market.
Breakout trading: Sell when price breaks above upper band, buy when price breaks below lower band, using trend following breaker strategy.
Use cancel flash orders, only trade one direction at a time.
Set fixed order size, can be adjusted based on capital.
Advantage Analysis
CBMA has good smoothness and can track price effectively.
Adaptive EMA optimizes the responsiveness of moving average.
Upper/lower bands give clear directional signals when breakout happens.
Trend following model avoids whipsaw trades.
Fixed order size controls single trade risk.
Risk Analysis
Bollinger Bands parameters need optimization, too wide or too narrow can cause issues.
Breakout signals may have false breakouts.
Need stop loss to control loss.
Fixed order size cannot adjust position based on market.
Only trade one direction, cannot profit more.
Optimization Directions
Dynamically optimize Bollinger Bands parameters to fit market better.
Add more indicators for filtration, avoid false breakouts.
Add trailing stop loss to lock in profits.
Hedge trading, go both long and short for bigger profit.
Add position sizing system.
Conclusion
This strategy is a breaker trend following system using adaptive moving average technology combined with Bollinger Bands for clear breakout signals. It has simple logic and fixed order size controls risk, having some practical value. But issues like false breakouts and parameter optimization remain, which need more indicators to improve and enhance real trading performance while controlling risk. Overall it is a decent starter breakout system with much room for improvement.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 12 | Length |
| v_input_2 | false | Regular BB Or CBMA? |
| v_input_3_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_4 | 2.3 | Multipler |
| v_input_5 | 11 | EMA Length |
| v_input_6 | 50 | EMA Gain Limit |
| v_input_7 | true | Highlight On/Off |
| v_input_8 | false | Strategy Direction |
Source Pine Script
/*backtest
start: 2023-10-29 00:00:00
end: 2023-11-05 00:00:00
period: 3m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy(title="CBMA Bollinger Bands Strategy directed [ChuckBanger]", shorttitle="CBMA BB CB",
   overlay=true )


length = input(title="Length", type=input.integer, defval=12, minval=1)
regular = input(title="Regular BB Or CBMA?", type=input.bool, defval=false)
src = input(title="Source", type=input.source, defval=close)
mult = input(title="Multipler", type=input.float, defval=2.3, minval=.001, maxval=50, step=.1)
emaLen = input(title="EMA Length", type=input.integer, defval=11, minval=1)
emaGL = input(title="EMA Gain Limit", type=input.integer, defval=50, minval=1)
highlight = input(title="Highlight On/Off", type=input.bool, defval=true)

direction = input(0, title = "Strategy Direction", type=input.integer, minval=-1, maxval=1)

strategy.risk.allow_entry_in(direction == 0 ? strategy.direction.all : (direction < 0 ? strategy.direction.short : strategy.direction.long))

//strategy.risk.max_drawdown(50, strategy.percent_of_equity)

calc_hma(src, length) =>
    hullma = wma(2*wma(src, length/2)-wma(src, length), round(sqrt(length)))
    hullma

calc_cbma(price, length, emaLength, emaGainLimit) =>
    alpha = 2 / (emaLength + 1)
    ema = ema(price, emaLength)
    int leastError = 1000000

    float ec = 0
    float bestGain = 0

    for i = emaGainLimit to emaGainLimit
        gain = i / 10
        ec := alpha * ( ema + gain * (price - nz(ec[1])) ) + (1 - alpha) * nz(ec[1])
        error = price - ec
        if (abs(error) < leastError)
            leastError = abs(error)
            bestGain = gain

    ec := alpha * ( ema + bestGain * (price - nz(ec[1])) ) + (1 - alpha) * nz(ec[1])
    hull = calc_hma(price, length)

    cbma = (ec + hull) / 2
    cbma

cbma = calc_cbma(src, length, emaLen, emaGL)
basis = regular ? sma(src, length) : cbma
dev = mult * stdev(src, length)
upper = basis + dev
lower = basis - dev
cbmaColor = fixnan(highlight and not regular ? cbma > high ? color.purple : cbma < low ? color.aqua : na : color.red)
plot(basis, color=cbmaColor)
p1 = plot(upper, color=color.blue)
p2 = plot(lower, color=color.blue)
fill(p1, p2)

if (crossover(src, lower))
    strategy.entry("CBMA_BBandLE", strategy.long, stop=lower, oca_name="BollingerBands", comment="CBMA_BBandLE")
else
    strategy.cancel(id="CBMA_BBandLE")

if (crossunder(src, upper))
    strategy.entry("CBMA_BBandSE", strategy.short, stop=upper, oca_name="BollingerBands", comment="CBMA_BBandSE")
else
    strategy.cancel(id="CBMA_BBandSE")
Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-06. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/CBMA-Bollinger-Bands-Breaker-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- BB Breakout StrategyPine Script · Breakout · 1d
- Bollinger Band T3 Moving Average StrategyPine Script · Breakout · 10m
- Bollinger Bands Dual track Breakthrough StrategyPine Script · Breakout · 30m
- Bollinger Breakout StrategyPine Script · Breakout · 30m
- Dynamic Bollinger Bands Breakout Quantitative Trading StrategyPine Script · Breakout · 2d
- EMA and Bollinger Bands Breakout StrategyPine Script · Breakout · 1h