Cloud Nebula Dual Moving Average Breakthrough Strategy
The Cloud Nebula Dual Moving Average Breakthrough Strategy is a strategy that utilizes fast moving averages and slow moving averages to form dual clouds for breakthrough trading. The strategy has the characteristics…
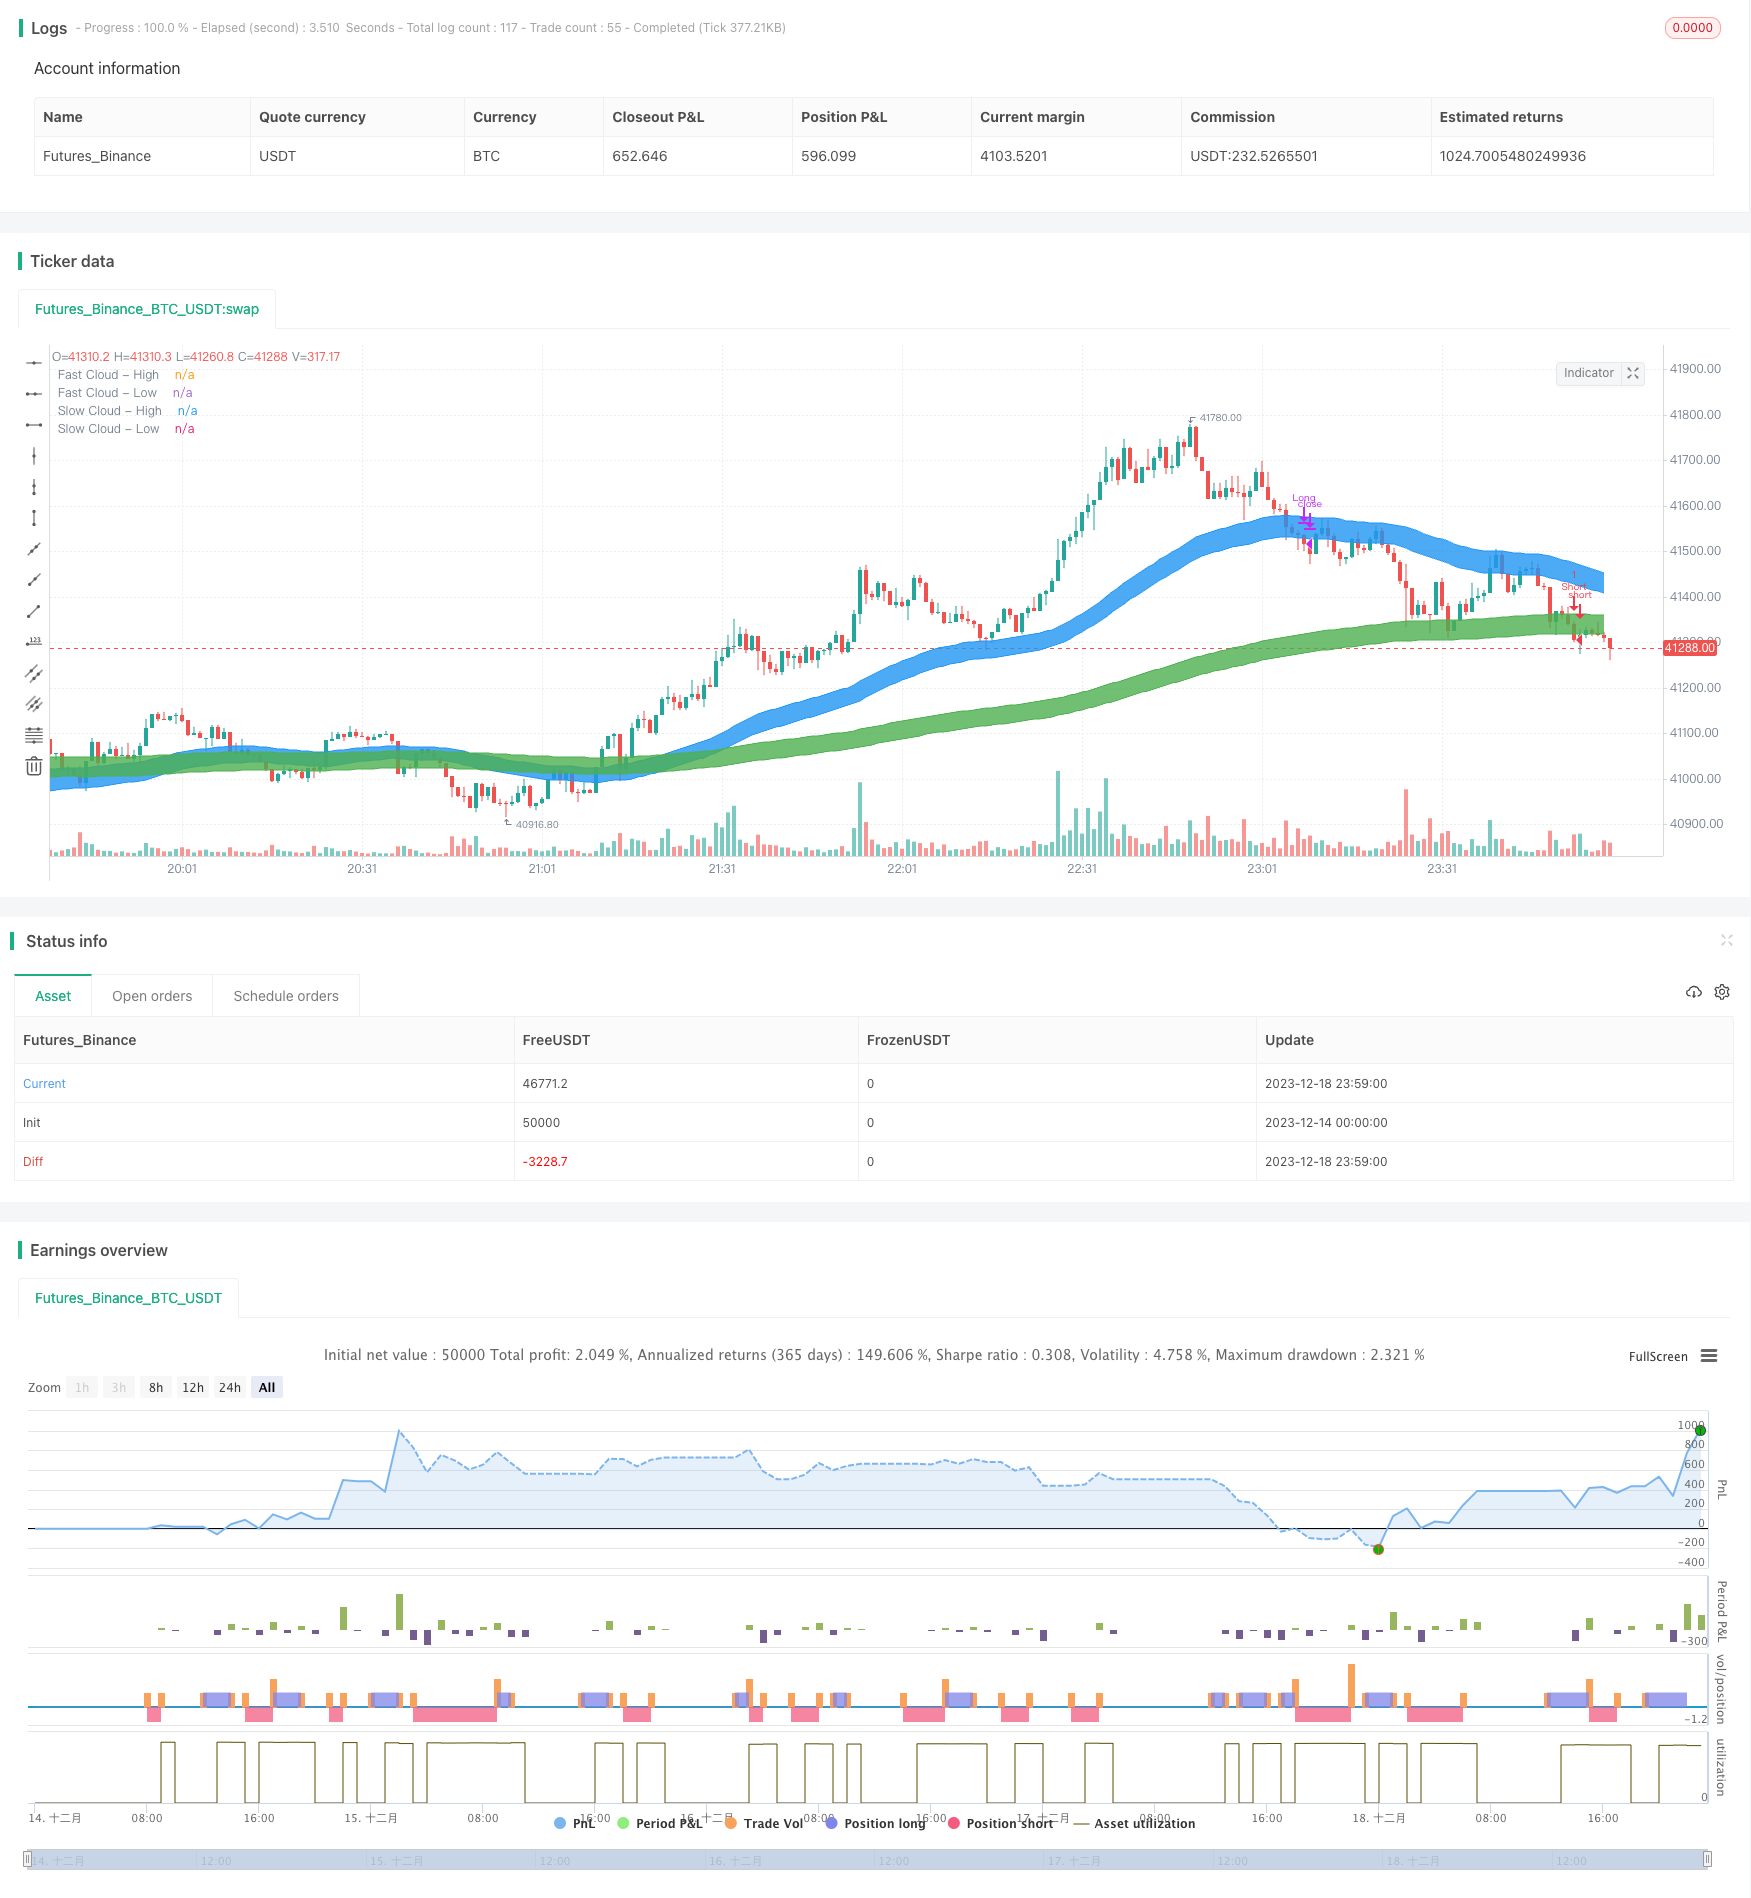
Overview**
The Cloud Nebula Dual Moving Average Breakthrough Strategy is a strategy that utilizes fast moving averages and slow moving averages to form dual clouds for breakthrough trading. The strategy has the characteristics of both trend tracking and reversal trading.
Strategy Principle
The strategy calculates the 60-period high-low price EMA as the fast cloud and the 240-period high-low price EMA as the slow cloud. When the fast cloud is completely below the slow cloud, go long; when the fast cloud is completely above the slow cloud, go short. The specific entry rules are that there are opportunities to enter when the price breaks through the upper or lower edges of the slow cloud. The stop loss is set at the highest and lowest prices within 5 days, and the take profit is set when the price breaks through the upper or lower edges of the fast cloud.
The strategy has both the characteristics of trend tracking and reversal trading. When the market is oscillating, the fold-over of the fast and slow clouds is an opportunity to make a reversal; when the fast and slow clouds are parallel, follow the trend to trade the trend.
Advantage Analysis
The dual cloud structure can effectively judge market trends, using the up and down crossovers between dual clouds to make reversal trades, greatly improving win rate.
The separation of the fast and slow clouds in the dual cloud structure is a signal of market change, which provides us with potential opportunities.
By using crossovers between clouds and price breakouts against clouds, the strategy has both trend following and reversal trading characteristics, balancing frequency of operation and win rate.
Using cloud edges as stop loss and take profit points can effectively control risks.
Risk Analysis
During violent price fluctuations, frequent crossovers may occur between fast and slow clouds, leading to multiple losing positions.
This strategy is more suitable for oscillating market environments. In trending markets, there are often many parallel situations between fast and slow clouds, which can easily lead to being trapped.
Within consolidation periods, there is a lack of effective methods to follow trends, unable to capture potential major rallies or declines after consolidations.
Optimization Directions
Price channels and trading volumes can be added before cloud crossovers occur to avoid false signals caused by violent price fluctuations.
Trend judgment indicators can be added. When separations between fast and slow clouds occur, judge the major trend direction and selectively participate in reversal trading.
Adaptive algorithms for the width of the fast cloud can be set to find the optimal parameter combination in oscillating and trending market environments.
Conclusion
The Cloud Nebula Dual Moving Average Breakthrough Strategy comprehensively utilizes the advantages of fast moving averages and slow moving averages to construct a dual cloud system for reversal and trend trading. It balances frequency of operation and win rate, and can effectively grasp the rhythm of market changes. By adding auxiliary judgment indicators and parameter optimization, the advantages of the strategy can be further expanded to better adapt to complex and ever-changing market environments.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 60 | Fast Cloud Length |
| v_input_2 | 240 | Slow Cloud Length |
Source Pine Script
/*backtest
start: 2023-12-14 00:00:00
end: 2023-12-19 00:00:00
period: 1m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// High Low Cloud Strategy Backtesting
// © inno14

//@version=4
strategy(title="High Low Cloud Strategy Backtesting", overlay=true, pyramiding=0)
c1=input(60, title="Fast Cloud Length")
c2=input(240, title="Slow Cloud Length")
c1_high=ema(high,c1)
c1_low=ema(low,c1)
highc1=plot(c1_high, title="Fast Cloud - High", color=color.blue, offset=0, transp=50, linewidth=1)
lowc1=plot(c1_low, title="Fast Cloud - Low", color=color.blue, offset=0, transp=50, linewidth=1)
fill(highc1, lowc1, transp=60, color=color.blue, title="Fast Cloud")
c2_high=ema(high,c2)
c2_low=ema(low,c2)
highc2=plot(c2_high, title="Slow Cloud - High", color=color.green, offset=0, transp=50, linewidth=1)
lowc2=plot(c2_low, title="Slow Cloud - Low", color=color.green, offset=0, transp=50, linewidth=1)
fill(highc2, lowc2, transp=40, color=color.green, title="Slow Cloud")
//Backtesting
//Long condition
ycloud_entry=
       c1_high<c2_low
       and crossover(close,c2_high)


ycloud_stoploss=
       crossunder(close,valuewhen(ycloud_entry,lowest(close[1],c2),0))

ycloud_takeprofit=
      c1_low>c2_high
      and crossunder(close,c1_low)


strategy.entry("Long", strategy.long, when=ycloud_entry)
strategy.close("Long", when=ycloud_takeprofit or ycloud_stoploss)

//Short condition
xcloud_entry=
       c1_low>c2_high
       and crossunder(close,c2_low)

xcloud_stoploss=
       crossover(close,valuewhen(xcloud_entry,highest(close[1],c2),0))

xcloud_takeprofit=
       c1_high<c2_low
       and crossover(close,c1_high)

strategy.entry("Short", strategy.short, when=xcloud_entry)
strategy.close("Short", when=xcloud_takeprofit or xcloud_stoploss)


//EOF
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-22. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Cloud-Nebula-Dual-Moving-Average-Breakthrough-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive Multi Period Trading Strategy Based on Wave Trend Momentum BreakoutPine Script · Breakout · 2h
- BB Breakout StrategyPine Script · Breakout · 1d
- BMSB Breakout Strategy BMSBPine Script · Breakout · 1h
- Bollinger Band T3 Moving Average StrategyPine Script · Breakout · 10m
- Bollinger Bands Dual track Breakthrough StrategyPine Script · Breakout · 30m
- Bollinger Breakout StrategyPine Script · Breakout · 30m