Consolidation Breakout Strategy
This strategy is a day trading intraday consolidation breakout indicator for the Indian markets. It incorporates time condition, commission, and stop-loss trailing. The advantages of this strategy include clear…
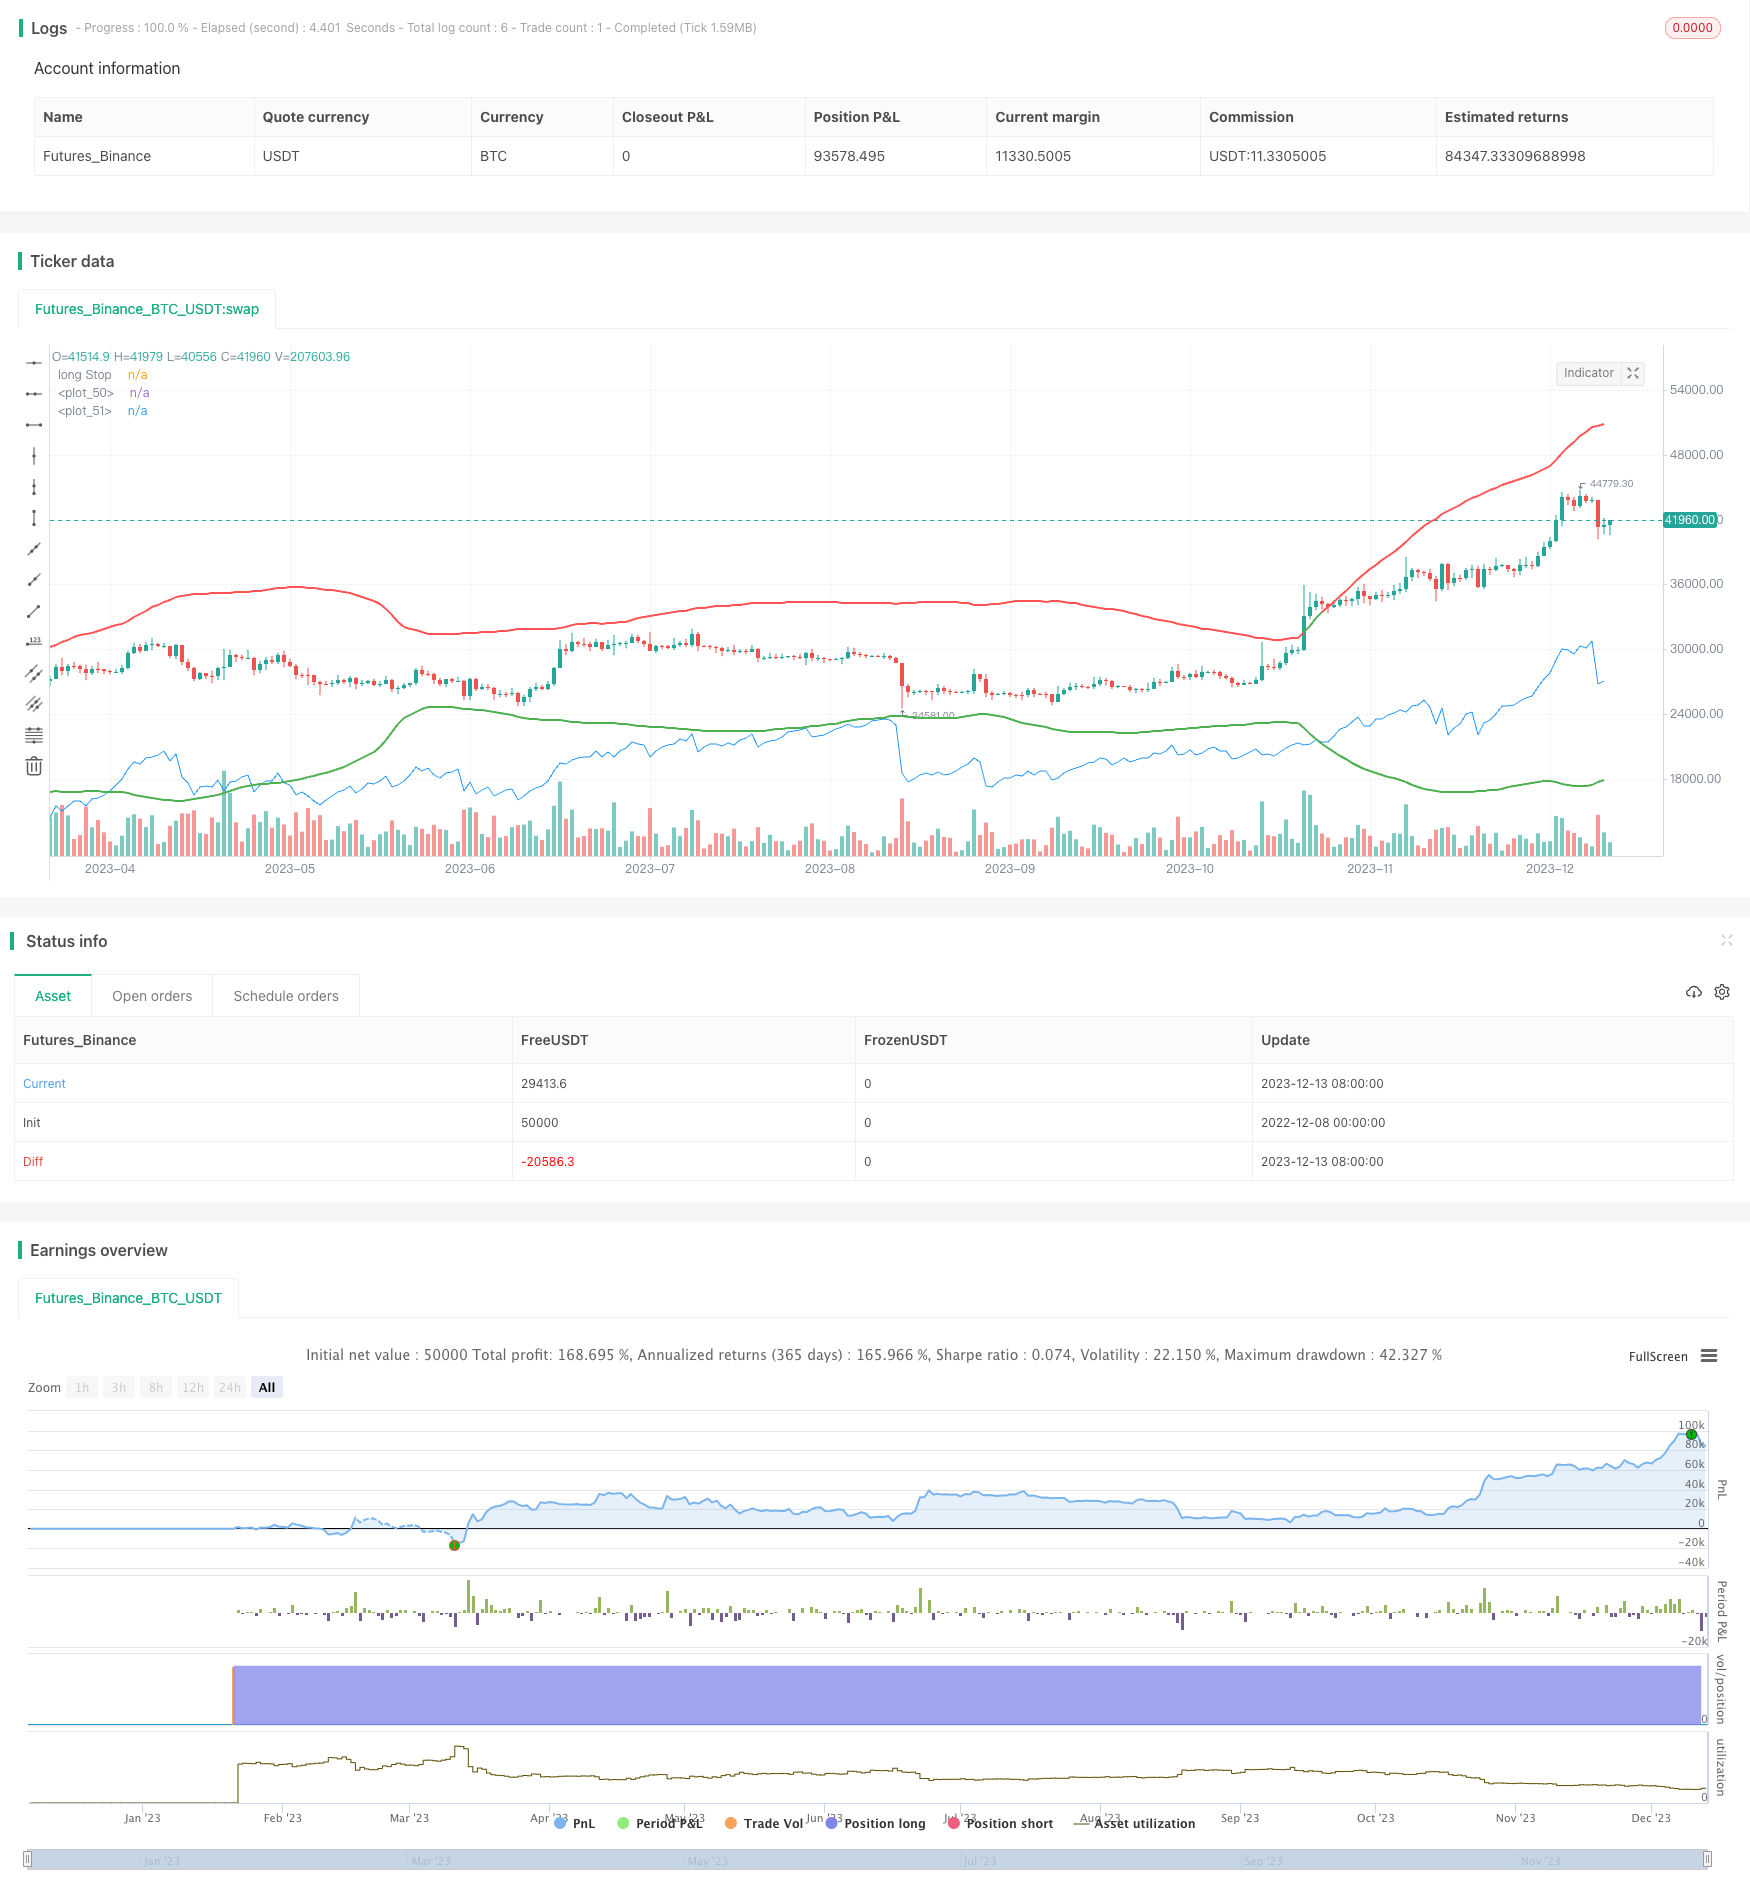
Overview
This strategy is a day trading intraday consolidation breakout indicator for the Indian markets. It incorporates time condition, commission, and stop-loss trailing. The advantages of this strategy include clear logic, flexible parameter tuning, and adaption to market dynamics. However, certain risks exist and need further optimization.
Strategy Logic
The core strategy is based on Bollinger Bands. It uses a LENGTH-period simple moving average as the mid-line and up/low bands are +MULT/-MULT standard deviations. Buy signals are generated when close breaks above the upper band, and sell signals are generated when close breaks below the lower band, forming Range Breakout strategy.
For risk control, it uses ATR for stop loss line. It also considers the Indian market trading hours and close all positions at 14:57 everyday.
Advantage Analysis
The advantages of this strategy:
- Clear logic, easy parameter tuning, flexible adaption
- Incorporate stop loss and timing control for risk management
- Consider specifics of Indian markets for localization
- Reasonable trading frequency, avoid over-trading
- Good extensibility for further optimization
Risk Analysis
The risks of this strategy:
- Bollinger Bands relies on parameter tuning based on experience
- Single indicator susceptible to false signals
- ATR stop loss can only control limited risks
- Black swan events not considered
Risks can be reduced by:
- Combining multiple indicators for signal filtering
- Optimizing parameter tuning rules
- Incorporating gap trading logic
- Enhancing stop loss robustness
- Combining market sentiment indices
Optimization Directions
The strategy can be optimized in several directions:
- Optimizing parameter tuning for better adaptiveness
- Adding more indicators to avoid false signals
- Enhancing stop loss robustness
- Incorporating more analysis for trend detection
- Consider auto position sizing
With model and algorithm optimization, the Parameter Tuning and Signal Filtering capabilities can be improved for broader adaption and higher risk tolerance.
Conclusion
In summary, this is a straightforward intraday breakout strategy. It addresses the Indian market specifics and controls trading risks. With further improvements on Parameter Tuning and Signal Filtering, this strategy can meet the requirement for commercialization.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_int_1 | 75 | LENGTH |
| v_input_float_1 | 3.2 | MULT_STDEV |
| v_input_float_2 | 10 | ATR TRAIL |
Source Pine Script
/*backtest
start: 2022-12-08 00:00:00
end: 2023-12-14 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Consolidation Breakout [Indian Market Timing]",overlay = true , pyramiding = 0 ,initial_capital = 50000, default_qty_value=5, currency = currency.NONE,commission_type = strategy.cash, commission_value = 30, slippage = 1 )


// ══════════════════════════════════//
// --------> INPUT VALUES <--------- //
// ══════════════════════════════════//

LENGTH = input.int(title='LENGTH', defval = 75, minval = 10 ,maxval = 300)
MULT = input.float(title='MULT_STDEV',defval = 3.2 , minval = 1 , maxval = 7 , step =0.1)

//EMA1 = input.int(title='EMA1', defval = 50, minval = 10 ,maxval = 550)
//EMA2 = input.int(title='EMA2', defval = 135, minval = 10 ,maxval = 550)
factor_tr = input.float(title = "ATR TRAIL", defval = 10, step = 0.1)

// ══════════════════════════════════//
// --------> DAY TIME LIMIT <------- //
// ══════════════════════════════════//

t = time(timeframe.period, '0935-1430:1234567')
time_condition = not na(t)

//**********************// ════════════════════════════════//
//**********************// --------> ATR & PLOT <--------- //
//**********************// ════════════════════════════════//
//ema1 = ta.ema(close,EMA1)
//ema2 = ta.ema(close,EMA2)

//plot(ema1, color=color.new(color.blue, 0), style=plot.style_linebr, title='ema1')
//plot(ema2, color=color.new(color.yellow, 0), style=plot.style_linebr, title='ema2')

atr_tr = ta.atr(16)*factor_tr

longStop = close - atr_tr
shortStop = close + atr_tr

Entry = close
length = LENGTH
mult = MULT
basis = ta.sma(Entry , length)
dev = mult * ta.stdev(Entry , length)
upper = (basis + dev)
lower = (basis - dev)
buyEntry = ta.crossover(Entry , upper)
sellEntry = ta.crossunder(Entry , lower)

//plot(upper, color=color.new(color.red, 0), style=plot.style_linebr, title="short stop")
//plot(lower, color=color.new(color.green, 0), style=plot.style_linebr, title="Long stop")

plot(upper, color=close[1] > upper and close > upper ? color.green : color.red, linewidth=2)
plot(lower, color=close[1] > lower and close > lower ? color.green : color.red, linewidth=2)


// ══════════════════════════════════//
// --------> LONG POSITIONS <--------//
// ══════════════════════════════════//
//******barinstate.isconfirmed used to avoid repaint in real time*******

if ( buyEntry and strategy.opentrades==0 and barstate.isconfirmed and time_condition)
    strategy.entry(id= "Long" ,direction = strategy.long, comment = "B")

plot(longStop , color=color.new(color.blue, 0), style=plot.style_linebr, title='long Stop')

if strategy.position_size > 0
    strategy.exit("long tsl", "Long" , stop = longStop , comment='S')

// ═════════════════════════════════════//
// --------> SHORT POSITIONS <--------- //
// ═════════════════════════════════════//
if ( sellEntry and strategy.opentrades==0 and barstate.isconfirmed and time_condition)
    strategy.entry(id = "Short" ,direction = strategy.short,  comment = "S")

if strategy.position_size < 0
    strategy.exit("short tsl", "Short" , stop = shortStop ,comment='B')

// ════════════════════════════════════════════════//
// --------> CLOSE ALL POSITIONS BY 3PM <--------- //
// ════════════════════════════════════════════════//
strategy.close_all(when = hour == 14 and minute == 57)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-15. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Consolidation-Breakout-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- BB Breakout StrategyPine Script · Breakout · 1d
- EMA and Bollinger Bands Breakout StrategyPine Script · Breakout · 1h
- Momentum Breakout Moving Average StrategyPine Script · Breakout · 1d
- Momentum Breakout Trading Strategy 440964Pine Script · Breakout · 5m
- Moving Average Crossover and Upper Rail Breakthrough Impulse StrategyPine Script · Breakout · 1m
- Quantitative Strategy PSARZigZagMACDART Based on Multi Indicator CombinationPine Script · Breakout · 1m