Strategy vault / Machine learning
Dual EMA Adaptive Optimization Strategy with Dynamic Stop Management System
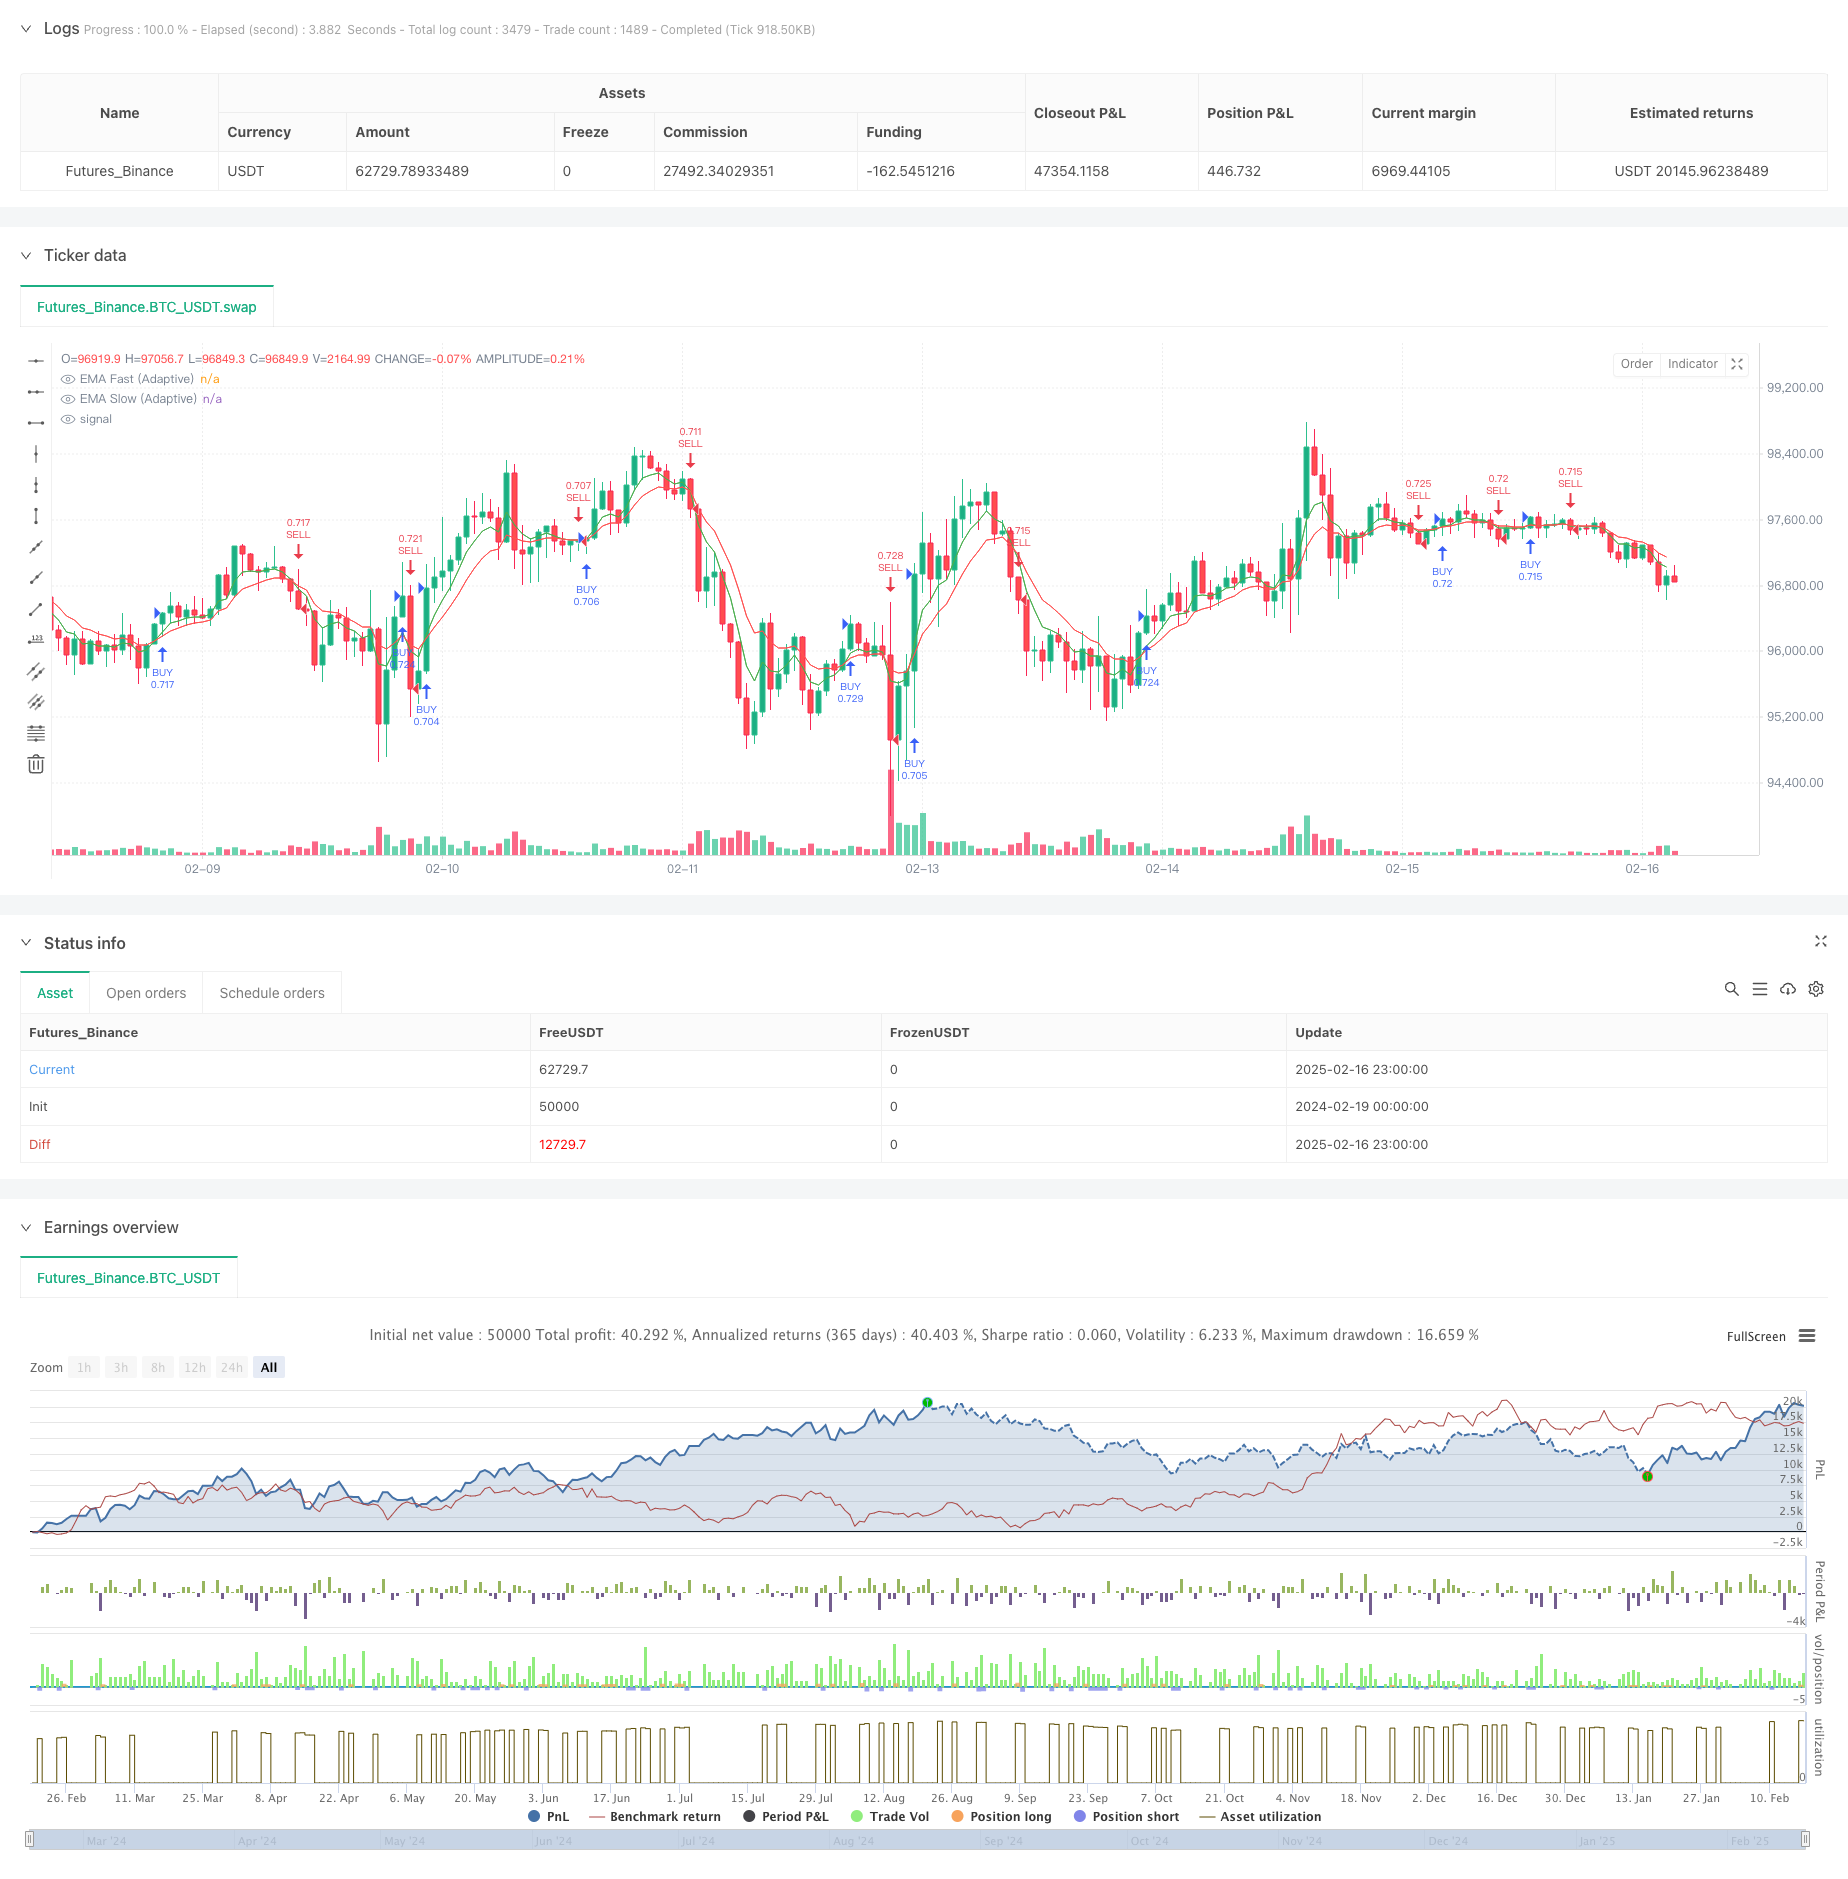
This strategy is an adaptive trading system based on Exponential Moving Averages (EMA) that utilizes AI optimization methods to dynamically adjust parameters for continuous performance improvement. The strategy…
Overview
This strategy is an adaptive trading system based on Exponential Moving Averages (EMA) that utilizes AI optimization methods to dynamically adjust parameters for continuous performance improvement. The strategy integrates fast and slow EMA crossover signals as trading triggers, coupled with an intelligent stop-loss and take-profit management mechanism to achieve optimal risk-reward balance.
Strategy Principles
The strategy's core is based on two EMAs with different periods. The system initially uses 5 and 10 periods as parameters, generating trading signals through the observation of crossovers between fast and slow EMAs. A buy signal is triggered when the fast EMA crosses above the slow EMA, while a sell signal is generated when the fast EMA crosses below the slow EMA. The system's distinctive feature lies in its adaptive optimization mechanism - continuously monitoring trading performance and dynamically adjusting stop-loss and take-profit levels to ensure the system operates under optimal parameter combinations.
Strategy Advantages
- Parameter Adaptability: The system automatically adjusts stop-loss and take-profit parameters based on market conditions, avoiding the lag issues associated with fixed parameters.
- Intelligent Risk Management: Through dynamic tracking of best profit performance, the system continuously optimizes risk control parameters, improving capital management efficiency.
- Objective Operation: The EMA crossover-based signal system provides clear entry and exit conditions, reducing interference from subjective judgment.
- Visualization Monitoring: The system provides real-time parameter optimization results display, facilitating traders' understanding of strategy performance.
Strategy Risks
- Market Volatility Risk: In ranging markets, EMA crossover signals may generate frequent false breakouts.
- Parameter Optimization Delay: The adaptive system requires accumulating sufficient trading data for effective parameter optimization.
- Drawdown Control: The system may exhibit some lag in response to sharp trend reversals.
Strategy Optimization Directions
- Incorporate Volatility Indicators: Consider integrating ATR or volatility indicators for dynamic EMA parameter adjustment to improve system adaptability to market conditions.
- Enhance Parameter Adjustment Mechanism: Implement more sophisticated machine learning algorithms to improve parameter optimization efficiency and accuracy.
- Add Market Environment Filters: Introduce trend strength indicators to adopt differentiated parameter settings under various market conditions.
Summary
This is a trading system that combines traditional technical analysis wisdom with modern adaptive optimization technology. It provides basic trading signals through EMA crossovers, coupled with dynamic stop-loss and take-profit management, achieving intelligent operation of the trading strategy. The system's adaptive nature enables continuous optimization capability, but attention must still be paid to market environment changes and the importance of risk control. It is recommended to conduct thorough backtesting and parameter sensitivity analysis before live trading.
Source Pine Script
/*backtest
start: 2024-02-19 00:00:00
end: 2025-02-17 00:00:00
period: 1h
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Evolutivna Strategija - AI Optimizacija", overlay=true, default_qty_type=strategy.percent_of_equity, default_qty_value=100)

// Varijable za praćenje performansi
var float bestProfit = na
var float bestStopLoss = na
var float bestTakeProfit = na

// Početni parametri (fiksne vrednosti)
ema_fast_final = input.int(5, "Početni EMA Fast", minval=5, maxval=50)  // Mora biti simple int
ema_slow_final = input.int(10, "Početni EMA Slow", minval=10, maxval=100)  // Mora biti simple int

// Kreiranje EMA koristeći fiksne vrednosti
ema_fast_adaptive = ta.ema(close, ema_fast_final)
ema_slow_adaptive = ta.ema(close, ema_slow_final)

// Signali kupovine i prodaje
buy_signal = ta.crossover(ema_fast_adaptive, ema_slow_adaptive)
sell_signal = ta.crossunder(ema_fast_adaptive, ema_slow_adaptive)

// Stop Loss i Take Profit parametri
sl_input = input.float(1.0, "Početni Stop Loss (%)", step=0.1)
tp_input = input.float(1.0, "Početni Take Profit (%)", step=0.1)

// Dinamično prilagođavanje parametara SL i TP
if (na(bestProfit) or strategy.netprofit > bestProfit)
    bestProfit := strategy.netprofit
    bestStopLoss := sl_input
    bestTakeProfit := tp_input

// Otvaranje pozicija
if (buy_signal)
    strategy.entry("BUY", strategy.long)
    strategy.exit("TP/SL", "BUY", stop=close * (1 - bestStopLoss / 100), limit=close * (1 + bestTakeProfit / 100))

if (sell_signal)
    strategy.entry("SELL", strategy.short)
    strategy.exit("TP/SL", "SELL", stop=close * (1 + bestStopLoss / 100), limit=close * (1 - bestTakeProfit / 100))

// Vizualizacija
plot(ema_fast_adaptive, color=color.green, title="EMA Fast (Adaptive)")
plot(ema_slow_adaptive, color=color.red, title="EMA Slow (Adaptive)")

// Prikaz najboljih rezultata
var label result_label = na
if (na(result_label))
    result_label := label.new(x=bar_index, y=high, text="", style=label.style_label_down, color=color.blue)

label.set_xy(result_label, bar_index, high)
label.set_text(result_label, "Best rezult: " + str.tostring(bestProfit, "#.##") +
 "\nSL: " + str.tostring(bestStopLoss) + "%" +
 "\nTP: " + str.tostring(bestTakeProfit) + "%" +
 "\nEMA Fast: " + str.tostring(ema_fast_final) +
 "\nEMA Slow: " + str.tostring(ema_slow_final))
Published by ChaoZhang on the FMZ strategy square · last modified 2025-02-18. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-EMA-Adaptive-Optimization-Strategy-with-Dynamic-Stop-Management-System.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- AI Driven Dynamic Volatility Adaptive Trend Breakout Trading StrategyPine Script · Machine learning · 2d
- Dual Moving Average Matching Strategy Based on Bollinger BandsPine Script · Machine learning · 1h
- Multi Indicator Dynamic Adaptive Quantitative Trading StrategyPine Script · Machine learning · 1h
- kNN based Trend Following StrategyPine Script · Machine learning · 1h
- Dual Indicator Stochastic RSI and EMA Trading StrategyPine Script · Machine learning · 1d
- High Low Cryptocurrency Strategy Based on Multiple IndicatorsPine Script · Machine learning · 45m