Strategy vault / Trend following
Dual EMA Golden Cross Long Line Strategy
The Dual EMA Golden Cross Long Line strategy is a trend tracking strategy that only opens long positions. The strategy uses three moving averages, short-term EMA, medium-term EMA and long-term EMA. The specific entry…
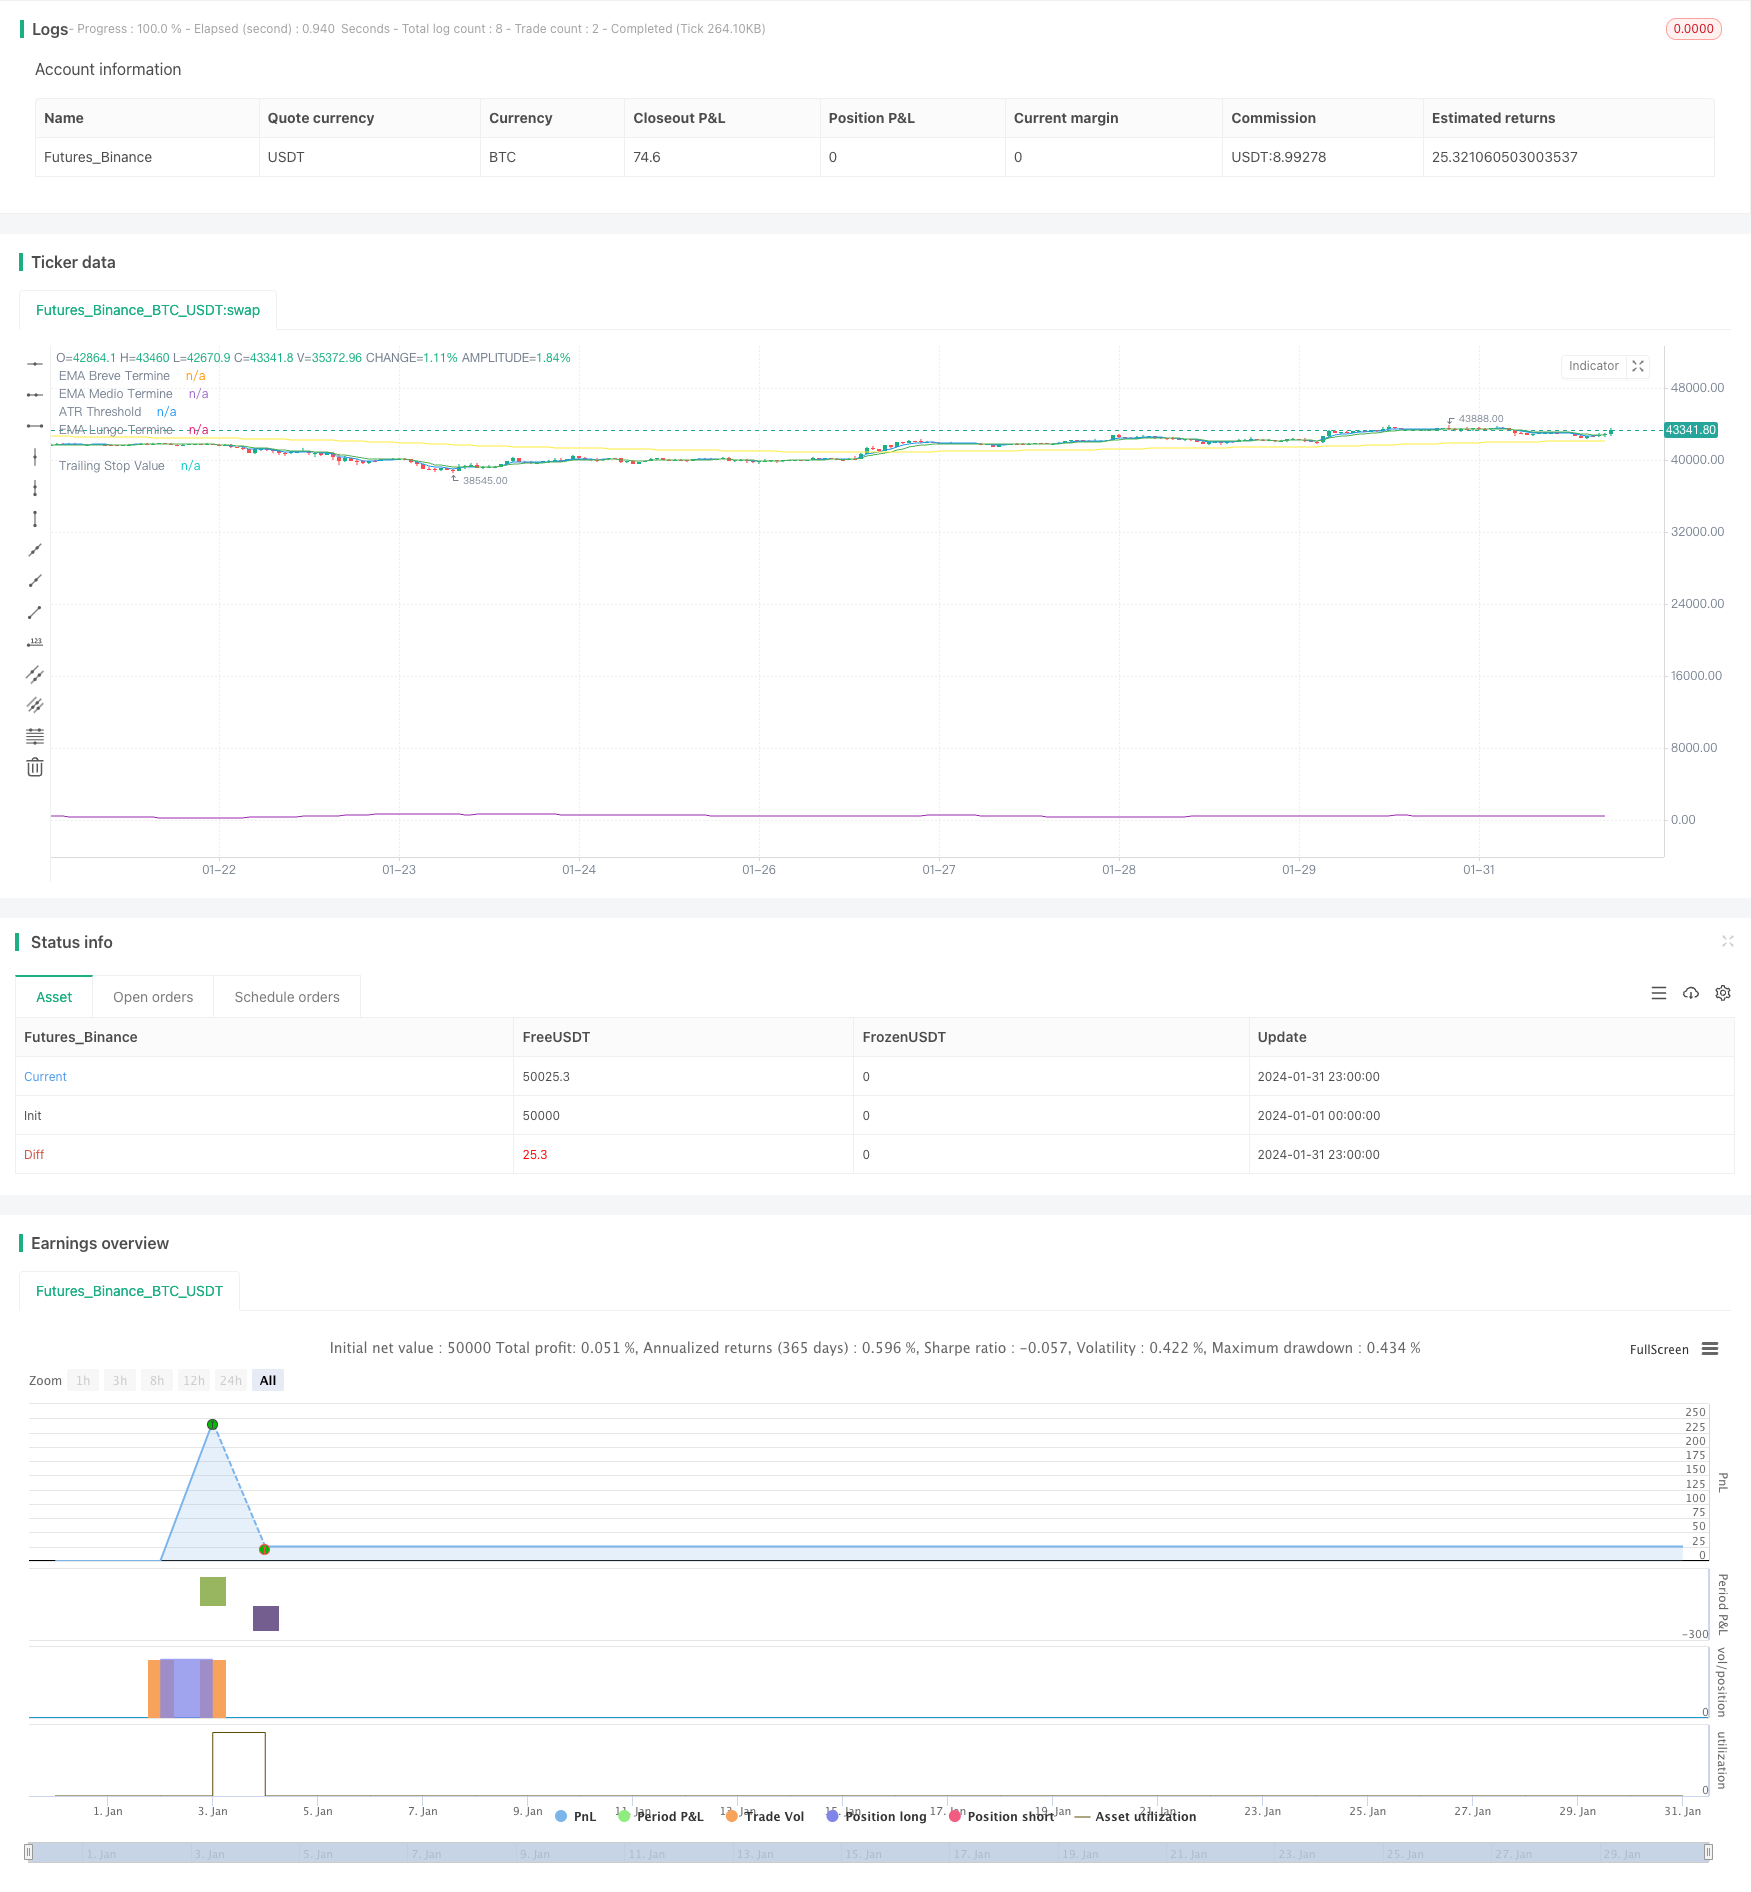
Overview
The Dual EMA Golden Cross Long Line strategy is a trend tracking strategy that only opens long positions. The strategy uses three moving averages, short-term EMA, medium-term EMA and long-term EMA. The specific entry rule is: open long when the price is above the long-term EMA and the short-term EMA crosses above the medium-term EMA to form a golden cross.
Strategy Logic
Calculate short-term EMA, medium-term EMA and long-term EMA using three EMA periods that are configurable.
If the price is above the long-term EMA, it proves that it is currently in a bullish trend.
If the short-term EMA crosses above the medium-term EMA from below to form a golden cross, it further proves that the bullish trend is strengthening.
When both conditions above are met at the same time, open long.
Advantage Analysis
The biggest advantage of this strategy is that it can effectively identify trends by using multi-period EMAs combined judgment to avoid being misled by short-term market noise. At the same time, stop loss is configured as a risk control means to keep losses within a certain range.
Risk Analysis
The main risk of this strategy is the long position. When the market reverses, it is unable to close positions in time, leading to the risk of expanding losses. In addition, improper EMAs period setting can also lead to frequent trading and increase transaction costs.
Optimization Direction
Increase position sizing management to reduce positions when drawdowns reach a certain percentage.
Increase stop loss settings when breaking new highs.
Optimize EMAs period parameters to reduce trading frequency.
Summary
This strategy is overall a stable high-quality long-term holding strategy. It has strong ability to identify trends with proper risk control. With further optimization, it is expected to obtain better stable returns.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_bool_1 | true | Usa Filtro di Volatilità |
| v_input_int_1 | 14 | Periodi ATR |
| v_input_float_1 | 1.5 | Moltiplicatore ATR |
| v_input_bool_2 | true | Usa Trailing Stop |
| v_input_float_2 | 15 | Percentuale Trailing Stop |
| v_input_bool_3 | true | Usa Uscita EMA Corta incrocia EMA Media al Ribasso |
| v_input_int_2 | 200 | Periodo EMA Lungo Termine |
| v_input_int_3 | 5 | Periodo EMA Breve Termine |
| v_input_int_4 | 10 | Periodo EMA Medio Termine |
Source Pine Script
/*backtest
start: 2024-01-01 00:00:00
end: 2024-01-31 23:59:59
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Strategia EMA Long con Opzioni di Uscita Avanzate e Periodi EMA Personalizzabili", overlay=true)

// Parametri di input generali
useVolatilityFilter = input.bool(true, title="Usa Filtro di Volatilità")
atrPeriods = input.int(14, title="Periodi ATR", minval=1)
atrMultiplier = input.float(1.5, title="Moltiplicatore ATR", step=0.1)
useTrailingStop = input.bool(true, title="Usa Trailing Stop")
trailingStopPercent = input.float(15.0, title="Percentuale Trailing Stop", minval=0.1, step=0.1) / 100.0
useEMAExit = input.bool(true, title="Usa Uscita EMA Corta incrocia EMA Media al Ribasso")

// Parametri di input per periodi EMA personalizzabili
emaLongTermPeriod = input.int(200, title="Periodo EMA Lungo Termine", minval=1)
emaShortTermPeriod = input.int(5, title="Periodo EMA Breve Termine", minval=1)
emaMidTermPeriod = input.int(10, title="Periodo EMA Medio Termine", minval=1)

// Calcolo delle EMA con periodi personalizzabili
longTermEMA = ta.ema(close, emaLongTermPeriod)
shortTermEMA = ta.ema(close, emaShortTermPeriod)
midTermEMA = ta.ema(close, emaMidTermPeriod)

// Calcolo ATR e soglia di volatilità
atr = ta.atr(atrPeriods)
atrThreshold = ta.sma(atr, atrPeriods) * atrMultiplier

// Condizione di entrata
enterLongCondition = close > longTermEMA and shortTermEMA > midTermEMA
enterLong = useVolatilityFilter ? (enterLongCondition and atr > atrThreshold) : enterLongCondition

if (enterLong)
    strategy.entry("Enter Long", strategy.long)

// Tracking del prezzo di entrata e del massimo prezzo raggiunto per il trailing stop
var float entryPrice = na
var float maxPriceSinceEntry = na
if (strategy.position_size > 0)
    maxPriceSinceEntry := math.max(na(maxPriceSinceEntry) ? high : maxPriceSinceEntry, high)
    entryPrice := na(entryPrice) ? strategy.position_avg_price : entryPrice
else
    maxPriceSinceEntry := na
    entryPrice := na

// Calcolo del valore del trailing stop
trailStopPrice = maxPriceSinceEntry * (1 - trailingStopPercent)

// Implementazione delle condizioni di uscita
exitCrossUnder = close < longTermEMA
emaCross = ta.crossunder(shortTermEMA, midTermEMA)

if (useEMAExit and emaCross)
    strategy.close("Enter Long", comment="EMA Cross Exit")

if (useTrailingStop)
    strategy.exit("Trailing Stop", from_entry="Enter Long", stop=trailStopPrice)

// Visualizzazioni
plot(longTermEMA, color=color.yellow, title="EMA Lungo Termine")
plot(shortTermEMA, color=color.blue, title="EMA Breve Termine")
plot(midTermEMA, color=color.green, title="EMA Medio Termine")
plot(useVolatilityFilter ? atrThreshold : na, color=color.purple, title="ATR Threshold")
plot(strategy.position_size > 0 ? trailStopPrice : na, color=color.orange, title="Trailing Stop Value", style=plot.style_linebr)Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-23. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-EMA-Golden-Cross-Long-Line-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dual MA Crossover Trend Tracking StrategyPine Script · Trend following · 1h
- Dual Mode Adaptive Trend Trading Strategy EMA Crossover with ATR Volatility Based Risk Management SystemPine Script · Trend following · 1d
- Dual Moving Average Crossover Dynamic Position Optimization Strategy with EMA Cross Signal SystemPine Script · Trend following · 1h