Strategy vault / Trend following
Dual EMA Golden Cross Trend Tracking Strategy
This strategy calculates fast EMA line and slow EMA line and compares the size relationship between the two EMAs to determine the trend direction of the market. It belongs to a simple trend tracking strategy. When…
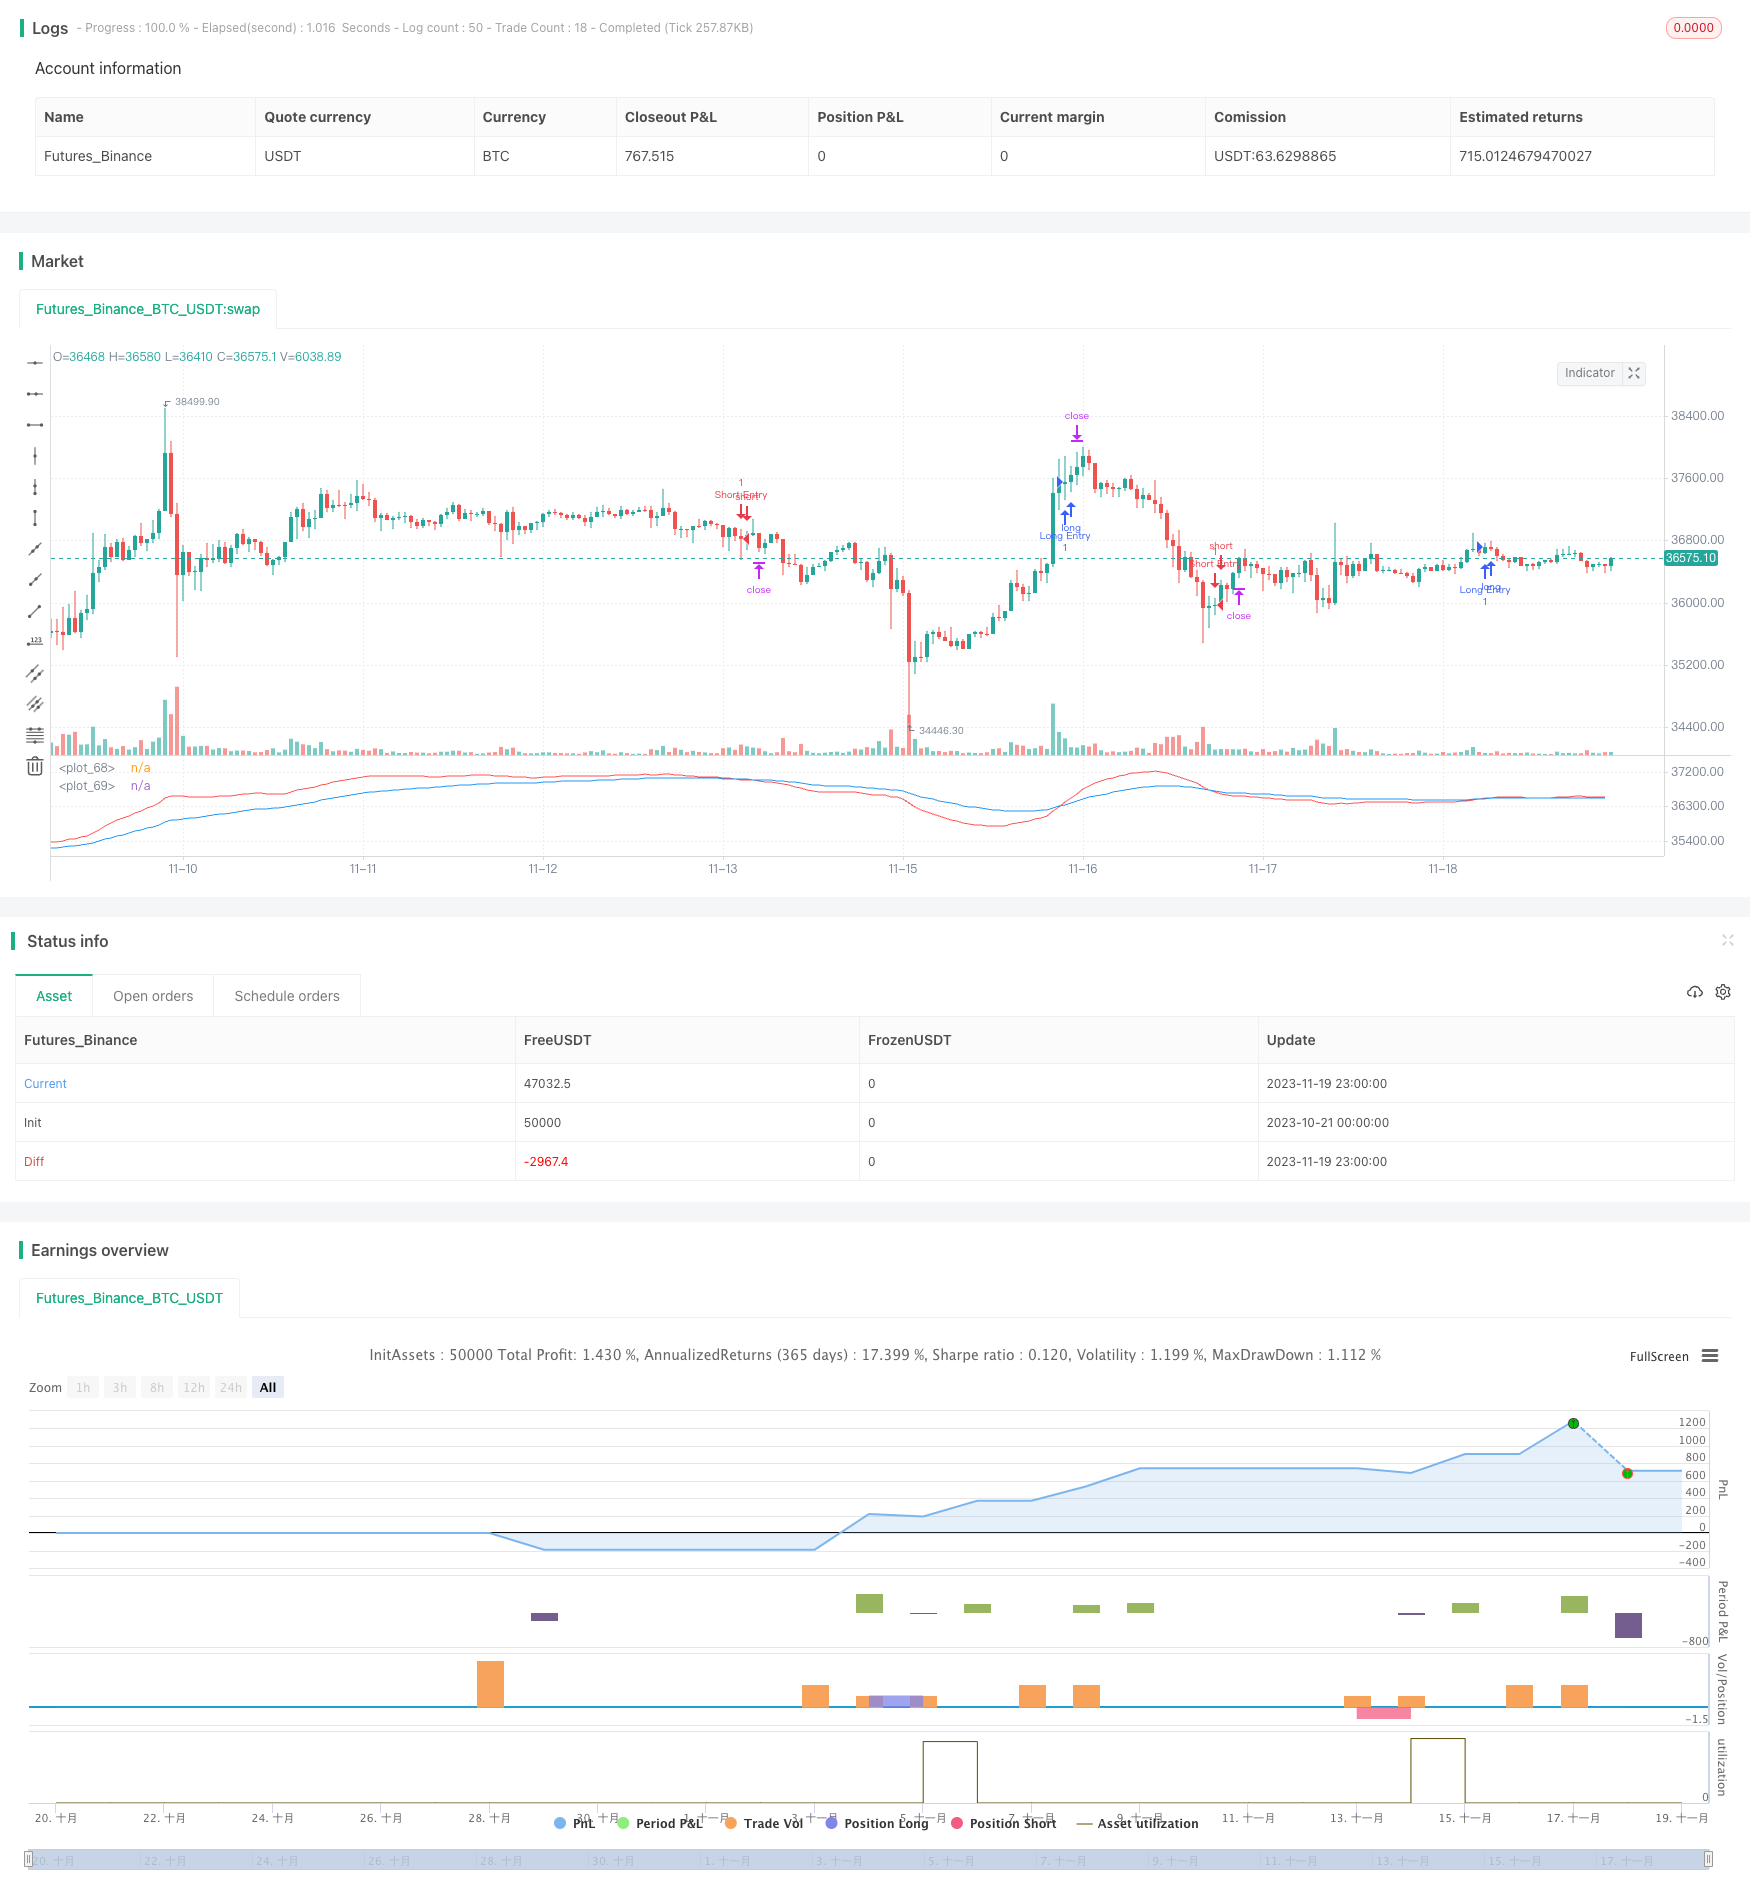
Overview
This strategy calculates fast EMA line and slow EMA line and compares the size relationship between the two EMAs to determine the trend direction of the market. It belongs to a simple trend tracking strategy. When the fast EMA crosses above the slow EMA, go long. When the fast EMA crosses below the slow EMA, go short. It is a typical dual EMA golden cross strategy.
Strategy Logic
The core indicators of this strategy are fast EMA and slow EMA. The fast EMA length is set to 21 periods and the slow EMA length is set to 55 periods. The fast EMA can respond to price changes faster, reflecting the recent short-term trend; the slow EMA responds more slowly to price changes, filtering out some noise and reflecting the medium-to-long term trend.
When the fast EMA crosses above the slow EMA, it indicates that the short-term trend has turned upward and the medium-to-long term trend may have reversed, which is a signal to go long. When the fast EMA crosses below the slow EMA, it indicates that the short-term trend has turned downward and the medium-to-long term trend may have reversed, which is a signal to go short.
By comparing fast and slow EMAs, it captures trend reversal points on two timescales, short-term and medium-to-long term, which is a typical trend tracking strategy.
Advantages
- Simple and clear logic, easy to understand and implement
- Flexible parameter tuning, fast and slow EMA periods can be customized
- Configurable ATR stop loss and take profit for controllable risks
Risks
- Inappropriate timing of EMA crossovers, risk of missing best entry point
- Frequent invalid signals during market consolidation, causing losses
- Improper ATR parameter setting, leading to too loose or too aggressive stops
Risk Management:
- Optimize EMA fast and slow line parameters to find optimal combinations
- Add filtering mechanisms to avoid invalid signals from market consolidation
- Test and optimize ATR parameters to ensure reasonable stop loss and take profit
Enhancement Areas
- Test stability of different EMA period parameters based on statistical methods
- Add filtering conditions combined with other indicators to avoid invalid signals
- Optimize ATR parameters to get best stop loss/take profit ratio
Summary
This strategy judges trend based on EMA crossovers, which is simple and clear to implement. With ATR-based stops, risks are controllable. Further improvements on stability and profitability can be made through parameter optimization and filtering conditions.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 2017 | Backtest Start Year |
| v_input_2 | true | Backtest Start Month |
| v_input_3 | true | Backtest Start Day |
| v_input_4 | 2025 | Backtest End Year |
| v_input_5 | true | Backtest End Month |
| v_input_6 | true | Backtest End Day |
| v_input_7 | false | Fixed Perc stop |
| v_input_8 | 0.1 | Percentage for fixed stop |
| v_input_9 | true | ATR Based stop |
| v_input_10 | 14 | ATR Length for stop |
| v_input_11 | 1.5 | ATR Multiplier for stoploss |
| v_input_12 | true | ATR Multiplier for profit |
| v_input_13 | true | Trade the Asian Session |
| v_input_14 | true | Trade the European Session |
| v_input_15 | true | Trade the US session |
| v_input_16 | true | End of Session Close Out? |
| v_input_17 | 21 | fastInput |
| v_input_18 | 55 | slowInput |
Source Pine Script
/*backtest
start: 2023-10-21 00:00:00
end: 2023-11-20 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
strategy(title = "VP Backtester", overlay=false)


// Create General Strategy Inputs
st_yr_inp = input(defval=2017, title='Backtest Start Year')
st_mn_inp = input(defval=01, title='Backtest Start Month')
st_dy_inp = input(defval=01, title='Backtest Start Day')
en_yr_inp = input(defval=2025, title='Backtest End Year')
en_mn_inp = input(defval=01, title='Backtest End Month')
en_dy_inp = input(defval=01, title='Backtest End Day')

// Default Stop Types
fstp = input(defval=false, title="Fixed Perc stop")
fper = input(defval=0.1, title='Percentage for fixed stop', type=float)
atsp = input(defval=true, title="ATR Based stop")
atrl = input(defval=14, title='ATR Length for stop')
atrmsl = input(defval=1.5, title='ATR Multiplier for stoploss')
atrtpm = input(defval=1, title='ATR Multiplier for profit')

// Sessions
asa_inp = input(defval=true, title="Trade the Asian Session")
eur_inp = input(defval=true, title="Trade the European Session")
usa_inp = input(defval=true, title="Trade the US session")
ses_cls = input(defval=true, title="End of Session Close Out?")

// Session Start / End times (In exchange TZ = UTC-5)
asa_ses = "1700-0300"
eur_ses = "0200-1200"
usa_ses = "0800-1700"

in_asa = time(timeframe.period, asa_ses)
in_eur = time(timeframe.period, eur_ses)
in_usa = time(timeframe.period, usa_ses)

strategy.risk.allow_entry_in(strategy.direction.all)

// Set start and end dates for backtest
start = timestamp(st_yr_inp, st_mn_inp, st_dy_inp,00,00)
end = timestamp(en_yr_inp, en_mn_inp, en_dy_inp,00,00)
window()  => time >= start and time <= end ? true : false // create function "within window of time"


// Check if we are in a sessions we want to trade
can_trade = asa_inp and not na(in_asa) ? true :
  eur_inp and not na(in_eur) ? true :
  usa_inp and not na(in_usa) ? true :
  false

// atr calc for stop and profit
atr = atr(atrl)
atr_stp_dst_sl = atr * atrmsl
atr_stp_dst_tp = atr * atrtpm


//*************************************************************************************
// Put your strategy/indicator code below
// and make sure to set long_condition=1 for opening a buy trade
// and short_condition for opening a sell trade
//*************************************************************************************
fastInput = input(21)
slowInput = input(55)

fast = ema(close, fastInput)
slow = ema(close, slowInput)

plot(fast, color = red)
plot(slow, color = blue)

long_condition = crossover(fast, slow)
short_condition = crossunder(fast, slow)


//*************************************************************************************
// Trade management with ATR based stop & profit
//*************************************************************************************
if (long_condition and window() )
    strategy.entry("Long Entry",  strategy.long)
    if strategy.position_size <= 0 // Less than as in both direction strat - Could be long before switching
        if atsp
            atr_stop = open  - atr_stp_dst_sl
            atr_profit = open + atr_stp_dst_tp
            strategy.exit('ATR Long Exit', "Long Entry", stop=atr_stop, limit = atr_profit)
        if fstp
            stop = open - (open * fper)
            strategy.exit('Perc Fixed Long Stop Exit', "Long Entry", stop=stop)

if (short_condition and window() )
    strategy.entry("Short Entry",strategy.short)
    if strategy.position_size >= 0 // Greater than as in both direction strat - Could be long before switching
        if atsp
            atr_stop = open  + atr_stp_dst_sl
            atr_profit = open - atr_stp_dst_tp
            strategy.exit('ATR Short Exit', "Short Entry", stop=atr_stop, limit = atr_profit)
        if fstp
            stop = open + (open * fper)
            strategy.exit('Perc Fixed Short Stop Exit', "Short Entry", stop=stop)


strategy.close_all(when=not can_trade and ses_cls)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-21. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-EMA-Golden-Cross-Trend-Tracking-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ATR Dynamic Trend Following and EMA Crossover Trading StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- ATR and T3 Moving Average StrategyPine Script · Trend following · 5m
- Adaptive ATR and RSI Trend Following Strategy with Trailing Stop LossPine Script · Trend following · 1h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m