Strategy vault / Trend following
Dual Exponential Moving Average Crossover Algorithmic Trading Strategy
The strategy is named "Dual Exponential Moving Average Crossover Algorithmic Trading Strategy". It calculates dual exponential moving averages (EMA) and generates trading signals when the EMAs cross over. Combined…
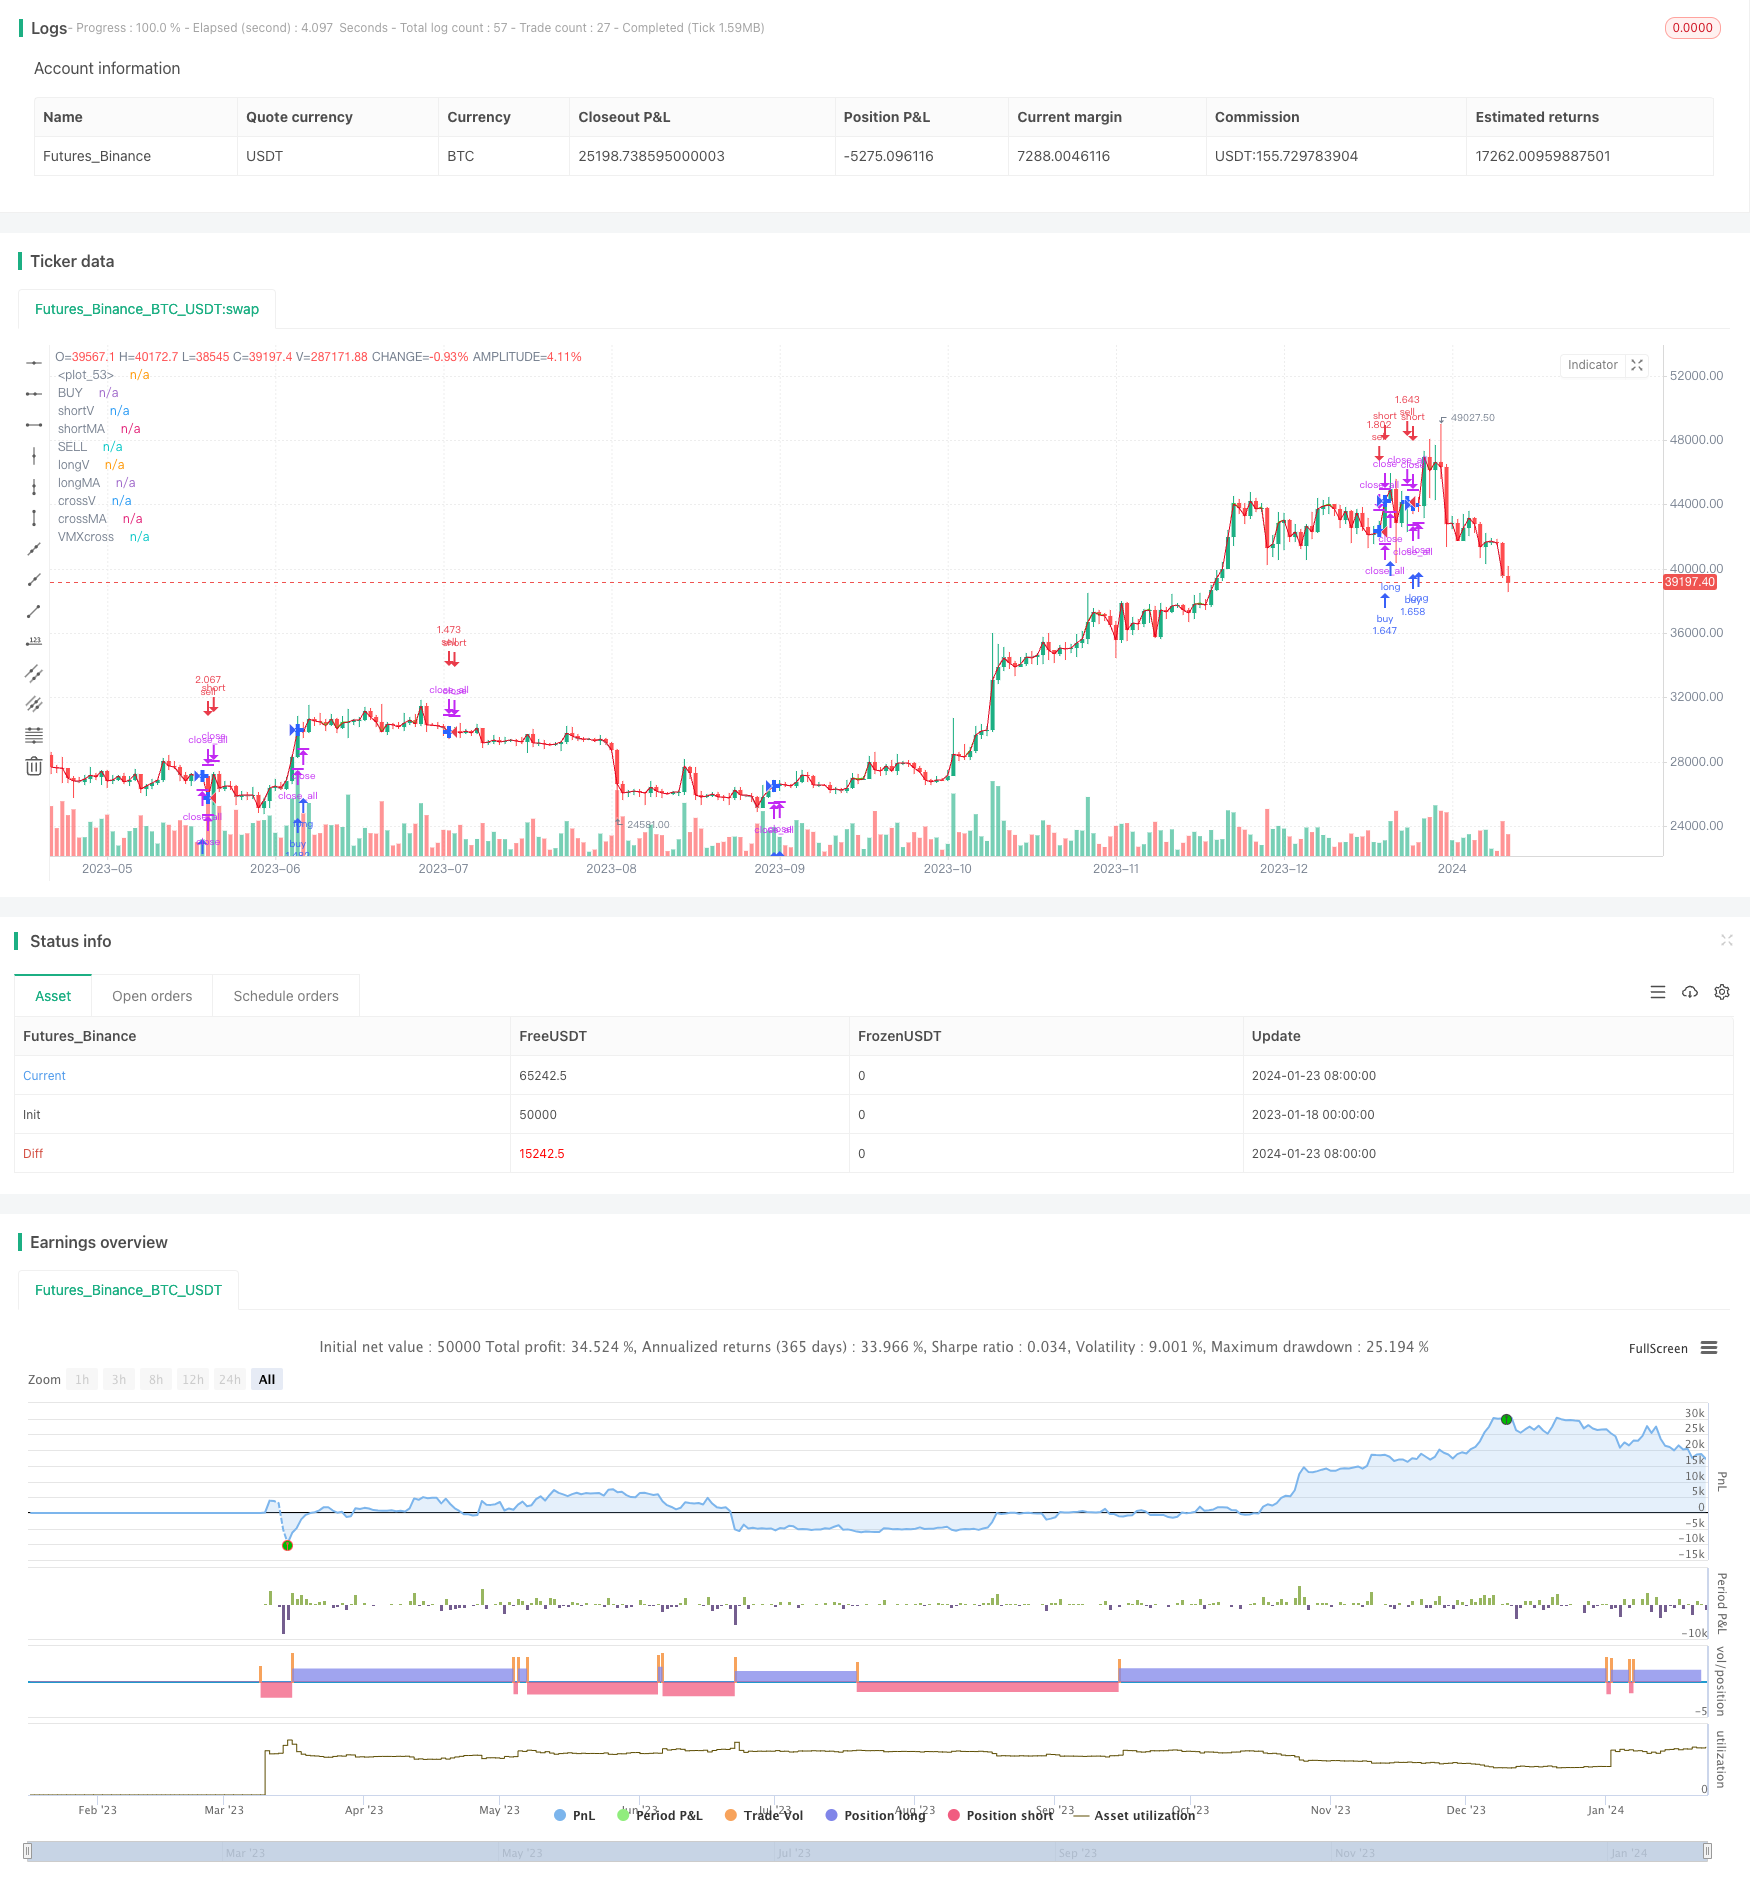
Overview
The strategy is named "Dual Exponential Moving Average Crossover Algorithmic Trading Strategy". It calculates dual exponential moving averages (EMA) and generates trading signals when the EMAs cross over. Combined with the algorithmic trading principles for order entry, it automates the entire trading process.
Strategy Logic
The core logic of this strategy is based on the dual EMA crossovers. Indicator 1 is the 20-day EMA and Indicator 2 is the 50-day EMA. A buy signal is generated when the shorter-term EMA crosses over the longer-term EMA from below. A sell signal is generated when the shorter-term EMA crosses below the longer-term EMA from above. So the crossover of EMAs with different parameters is used to determine market entry and exit points.
In addition, the Vortex indicator is used to aid in identifying the trend and generating trading signals. The Vortex indicator determines the bullish or bearish momentum by comparing the difference between the highest price and yesterday's close, and the lowest price and yesterday's open, over a 1-day and 3-day period. Using the Vortex can help filter out some less significant signals from the EMA crosses.
When a trading signal is generated, the built-in money management module helps manage risks by controlling position sizing based on predefined profit loss ratios. Stop loss and take profit levels can also be set to lock in profits and limit downsides.
Advantage Analysis
The strategy integrates dual EMA crossovers and the Vortex indicator to take advantage of both, thus improving signal accuracy
The automated trading system removes emotional human errors and minimizes risks
The auto stop loss/take profit functions limit max loss for each trade
The money management module controls capital allocation for each trade, thus manages overall risks
Risk Analysis
EMA crossovers may generate false signals. And the Vortex indicator cannot completely filter out false signals either. There can still be some losing trades.
Black swan events can lead to huge losses on open positions.
The strategy relies on stop losses to control drawdowns. If stopped out, losses may exceed expectations.
Improvement Opportunities:
EMA parameters can be further optimized to improve signal quality
More indicators may be added to better filter signals
Machine learning algorithms may help auto-optimize parameters
Conclusion
Overall this is a typical dual EMA crossover strategy for medium-term trading. It identifies trading opportunities from EMA crossovers. The biggest advantage lies in using indicators like the Vortex to filter signals, executing the automated strategy reliably, plus the embedded stop loss/take profit functions to mitigate risks. Going forward, strategy performance may be further enhanced through parameter tuning and integrating more complementary indicators.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 15 | short Time |
| v_input_2 | 25 | long time |
| v_input_3 | 5 | Vortex Power |
| v_input_4 | 20 | ShortMa |
| v_input_5 | 29 | LongMA |
| v_input_6 | true | Vortex Stabilize |
| v_input_7 | true | MACross Stabilize |
| v_input_8 | false | Stop Loss Long |
| v_input_9 | true | Stop Long |
| v_input_10 | false | Take Profit Long |
| v_input_11 | true | Take Long |
| v_input_12 | false | Stop Loss Short |
| v_input_13 | true | Stop Short |
| v_input_14 | false | Take Profit Short |
| v_input_15 | true | Take Short |
Source Pine Script
/*backtest
start: 2023-01-18 00:00:00
end: 2024-01-24 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © smottybugger

//@version= 5
strategy("The  Averages Moving_X_Vortex", shorttitle="2.5billion BTC lol" , calc_on_order_fills=true, calc_on_every_tick=true, commission_type=strategy.commission.percent, commission_value=0.02, default_qty_type=strategy.percent_of_equity, default_qty_value=100, initial_capital=100, margin_long=0, margin_short=0,overlay=true)
// Dual Vortex
period_1 = input(15, "short Time")
period_2 = input(25, "long time")
VMP = math.sum(math.abs(high - low[3]), period_1)
VMM = math.sum(math.abs(low - high[1]), period_2)
STR = math.sum(ta.atr(1), period_1)
STR2 = math.sum(ta.atr(1), period_2)
VXpower= (input(5,"Vortex Power")/10000)*close
shorterV =(VMP / STR)*VXpower
longerV = (VMM / STR2)*VXpower

// MACross
shortlen = input(20, "ShortMa")
longlen = input(29, "LongMA")
shorterMA = ta.sma(close, shortlen)
longerMA = ta.sma(close, longlen)

// Vortex "MACross Stabilized"
Varance = input(1, "Vortex Stabilize")
Vpercent = (Varance / 100)
shortV= ((((shorterMA-close)* Vpercent)+shorterV)/2)+close
longV = ((((longerMA -close )*Vpercent)+longerV)/2)+close

//MAcross vortex stabilized
Marance = input(1, "MACross Stabilize")
MApercent = Marance / 100
shortMA = ((((shorterMA-close)*MApercent)+shorterV)/2)+close
longMA = ((((longerMA-close)*MApercent)+longerV)/2)+close

//VMXadveraged Moving cross adveraged
VMXL=(longV+longMA)/2
VMXS=(shortV+shortMA)/2
VXcross= ta.cross(VMXS,VMXL) ? VMXS : na
VMXcross= ta.cross(VMXS,VMXL)

//plot
plot(VMXS,"BUY",color=#42D420)
plot(VMXL,"SELL",color=#e20420)
crossV= ta.cross(shortV, longV) ? shortV : na
plot(shortV ,"shortV", color=#42D420)
plot(longV,"longV", color=#e20420)
plot(crossV,"crossV", color=#2962FF, style=plot.style_cross, linewidth=4)
crossMA = ta.cross(shortMA, longMA) ? shortMA : na
plot(shortMA,"shortMA", color=#42D420)
plot(longMA,"longMA", color=#e20420)
plot(crossMA,"crossMA", color=#2962FF, style=plot.style_cross, linewidth=4)
plot(VXcross,"VMXcross",color=#2962FF, style= plot.style_cross,linewidth=4)
plot(close,color=#999999)

// Vortex Condistyle
is_Vlong =shortV< longV
is_Vshort =shortV>longV


// Vortex commands
Vlong =  ta.crossunder(longV, shortV)
Vshort =ta.crossover(shortV,longV)
VorteX = ta.cross(longV, shortV)

// MACross Conditions
is_MAlong = shortMA < longV
is_MAshort = shortMA > shortV


//VMX Conditions
is_VMXlong=VMXS<VMXL
is_VMXshort=VMXS>VMXL

// MA commands
MAlong = ta.crossunder(shortMA, longV)
MAshort =ta.crossover(shortMA, shortV)
MAcross =  ta.cross(shortMA, longMA)

//VMX COMMANss
VMXBUY=ta.crossover( VMXS,VMXL)
VMXSELL=ta.crossunder(VMXS,VMXL)

// Close Crossing PositionLMXs

CS=is_MAshort or is_VMXshort
CL= is_MAlong or is_VMXlong
OS=MAshort or VMXSELL
OL=MAlong or VMXBUY


if VMXcross
    strategy.close_all ("closed")

//if CS and  OL
    strategy.close("Short",comment="Short Closed")


//if CL and  OS
    strategy.close("Long",comment="Long Closed" )

//CA1= is_MAcross and is_VorteX
//if CA1
   // strategy.close_all(comment="X2X")

// Defalongyntry qty

if is_VMXlong and VMXSELL
    strategy.entry("sell",strategy.short)


if is_VMXshort and VMXBUY
    strategy.entry("buy",strategy.long)


// Stop Losses & Taking Profit
sllp = input(0, "Stop Loss Long")
sll = (1 - sllp / 100) * strategy.position_avg_price
is_sll = input(true, "Stop Long")

tplp = input(0, "Take Profit Long")
tpl = (1 + tplp / 100) * strategy.position_avg_price
is_tpl = input(true, "Take Long")

slsp = input(0, "Stop Loss Short")
sls = (1 + slsp / 100) * strategy.position_avg_price
is_sls = input(true, "Stop Short")

tpsp = input(0, "Take Profit Short")
tps = (1 - tpsp / 100) * strategy.position_avg_price
is_tps = input(true, "Take Short")

if (is_sll or is_sls)
    strategy.close("Stop Losses", qty_percent=100)

if (is_tpl or is_tps)
    strategy.close("Take Profits", qty_percent=100)


 //Strategy Backtest
//plot(strategy.equity, "Equity", color=color.red, linewidth=2, style=plot.style_areabr)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-25. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-Exponential-Moving-Average-Crossover-Algorithmic-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dual MA Crossover Trend Tracking StrategyPine Script · Trend following · 1h
- Dual Mode Adaptive Trend Trading Strategy EMA Crossover with ATR Volatility Based Risk Management SystemPine Script · Trend following · 1d
- Dual Moving Average Crossover Dynamic Position Optimization Strategy with EMA Cross Signal SystemPine Script · Trend following · 1h