Strategy vault / Trend following
Dual Moving Average Crossover Trend Following Strategy with Dynamic Stop Loss and Take Profit System
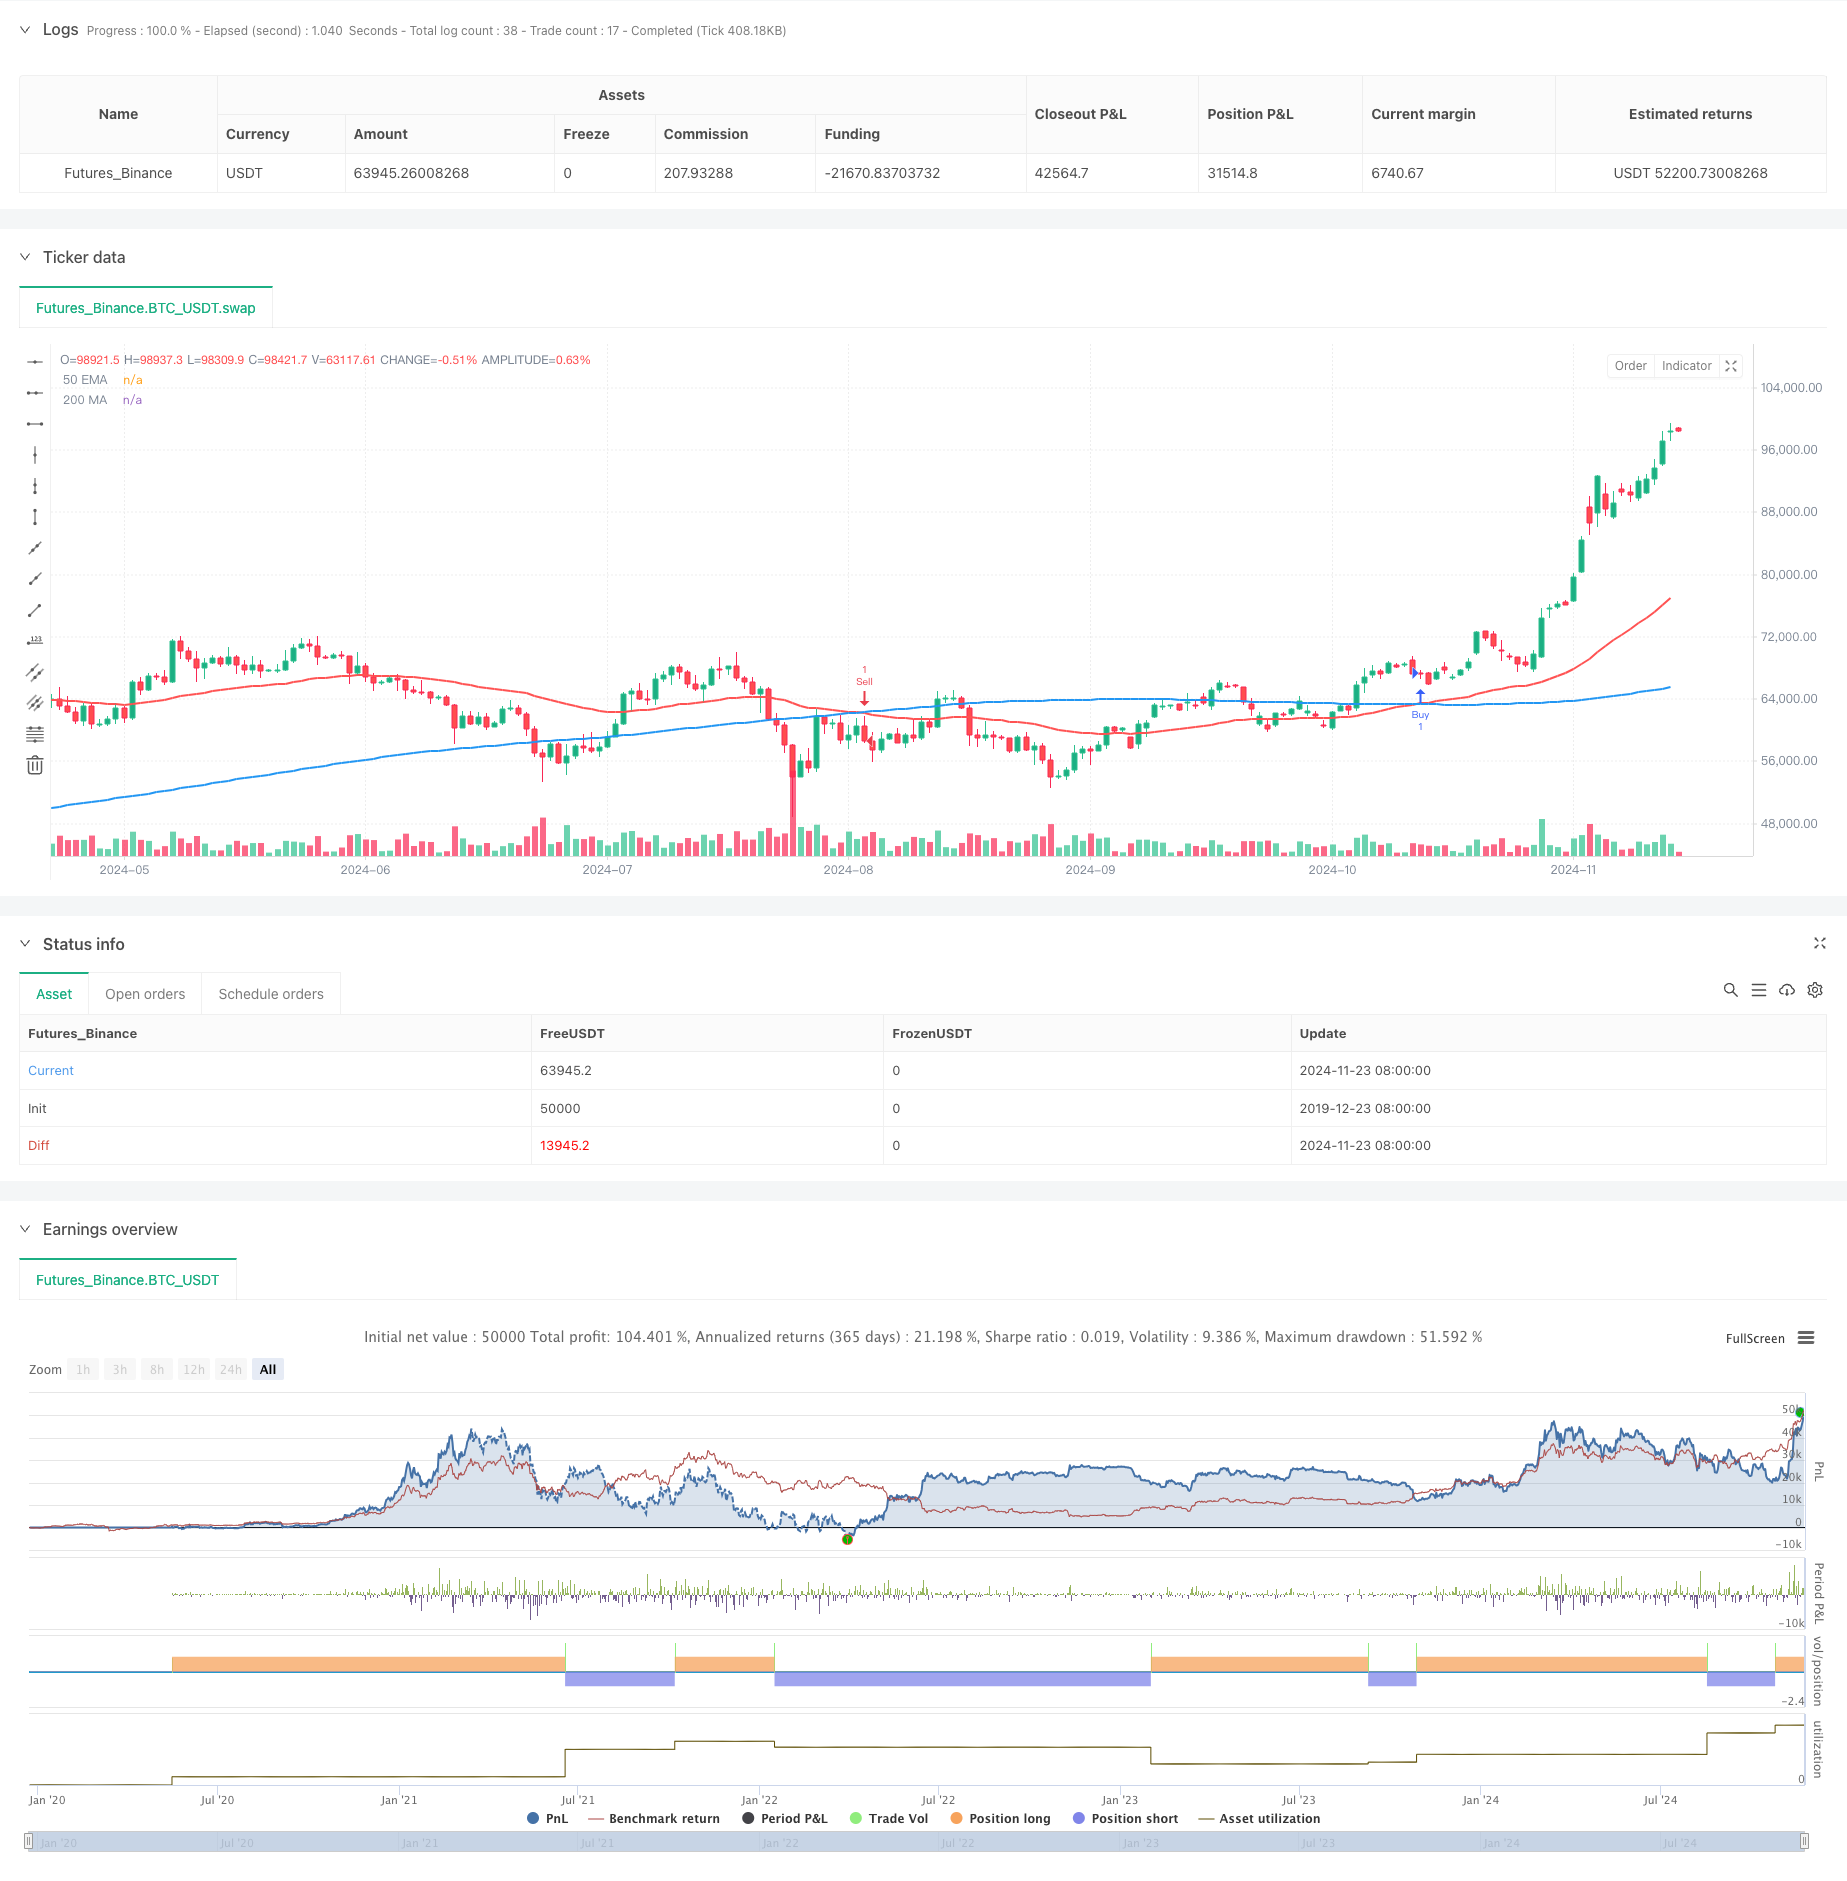
This strategy is a trend-following system based on technical analysis, primarily utilizing the crossover signals between the 50-period Exponential Moving Average (EMA) and 200-period Simple Moving Average (MA) to…
Overview
This strategy is a trend-following system based on technical analysis, primarily utilizing the crossover signals between the 50-period Exponential Moving Average (EMA) and 200-period Simple Moving Average (MA) to capture market trends. The strategy integrates a dynamic stop-loss and take-profit mechanism to control risks and secure profits, allowing it to both capture major trends and exit promptly during market reversals.
Strategy Principles
The core logic is based on the crossover of two moving averages: a buy signal is generated when the 50-period EMA crosses above the 200-period MA, while a sell signal is triggered when the 50-period EMA crosses below the 200-period MA. After each entry, the system automatically sets stop-loss levels (3 points from entry) and take-profit levels (7.5 points from entry). Additionally, positions are automatically closed when reverse signals appear to prevent holding positions against the market trend.
Strategy Advantages
- Strong trend following capability: Effectively captures market trend transitions by combining fast and slow moving averages
- Comprehensive risk control: Integrates dynamic stop-loss and take-profit mechanisms for effective risk management
- High systematization: Clear trading signals and fixed exit points reduce subjective judgment interference
- Strong adaptability: Strategy can be applied to different market environments and trading instruments
- Simple operation: Clear entry and exit logic, convenient for execution and backtesting
Strategy Risks
- Choppy market risk: False breakouts in ranging markets may lead to consecutive losses
- Slippage risk: Actual execution prices may significantly deviate from theoretical prices during high volatility
- Fixed stop-loss risk: Preset fixed stop-loss levels may not suit all market conditions
- Trend reversal risk: Potential delayed exits during sudden trend reversals
- Money management risk: Fixed stop-loss ranges may not be suitable for different account sizes
Optimization Directions
- Incorporate volatility indicators: Dynamically adjust stop-loss and take-profit levels based on market volatility
- Add trend confirmation indicators: Such as RSI or MACD to improve signal reliability
- Optimize money management: Adjust position sizes based on account size and market volatility
- Add market environment filters: Reduce trading frequency or pause trading in ranging markets
- Improve exit mechanism: Implement trailing stops to maximize profits
Summary
This strategy combines a classic dual moving average crossover system with dynamic stop-loss and take-profit mechanisms to create a complete trend-following trading system. Its strengths lie in high systematization and comprehensive risk control, though practical application requires optimization based on specific market conditions and capital size. The strategy's stability and profitability can be further enhanced by adding more technical indicators and improving money management methods. For investors seeking steady returns, this serves as a valuable basic strategy framework to build upon.
Source Pine Script
/*backtest
start: 2019-12-23 08:00:00
end: 2024-11-24 00:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("200 MA & 50 EMA Crossover Strategy with **Estimated** SL & TP", overlay=true)

 // Parameters for the 200 MA and 50 EMA
ma200 = ta.sma(close, 200) // 200-period simple moving average
ema50 = ta.ema(close, 50) // 50-period exponential moving average

 // Plot the MA and EMA on the chart
plot(ma200, color=color.blue, linewidth=2, title="200 MA")
plot(ema50, color=color.red, linewidth=2, title="50 EMA")

 // Define **estimated** stop loss and take profit values
// SL = 3 points, TP = 7.5 points from the entry price
sl_points = 3
tp_points = 7.5

 // Buy signal: when the 50 EMA crosses above the 200 MA (bullish crossover)
if (ta.crossover(ema50, ma200))
    strategy.entry("Buy", strategy.long)
 // Set **estimated** stop loss and take profit strategy.exit("Take Profit/Stop Loss", "Buy", stop=strategy.position_avg_price - sl_points, limit=strategy.position_avg_price + tp_points)

 // Sell signal: when the 50 EMA crosses below the 200 MA (bearish crossover)
if (ta.crossunder(ema50, ma200))
    strategy.entry("Sell", strategy.short)
 // Set **estimated** stop loss and take profit strategy.exit("Take Profit/Stop Loss", "Sell", stop=strategy.position_avg_price + sl_points, limit=strategy.position_avg_price - tp_points)

 // Optional: Close the position when an opposite signal appears
if (strategy.position_size > 0 and ta.crossunder(ema50, ma200))
    strategy.close("Buy")
if (strategy.position_size < 0 and ta.crossover(ema50, ma200))
    strategy.close("Sell")
Published by ChaoZhang on the FMZ strategy square · last modified 2024-11-25. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-Moving-Average-Crossover-Trend-Following-Strategy-with-Dynamic-Stop-Loss-and-Take-Profit-System.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dynamic Dual EMA Crossover Strategy with Adaptive Profit Loss ControlPine Script · Trend following · 1d
- EMA SMA Multi Indicator Comprehensive Trend Following StrategyPine Script · Trend following · 1h
- EMA and RSI Trend Trading StrategyPine Script · Trend following · 1d
- Fixed Range Volume Profile And Anchored VWAP Trend Identification Strategy With Dynamic Stop LossPine Script · Trend following · 1h