Strategy vault / Trend following
Dual Moving Average Tracking Stop Loss Strategy 441073
This strategy generates buy signals when the fast moving average crosses over the slow moving average. At the same time, it calculates the trailing stop loss price based on Average True Range to set sell signals…
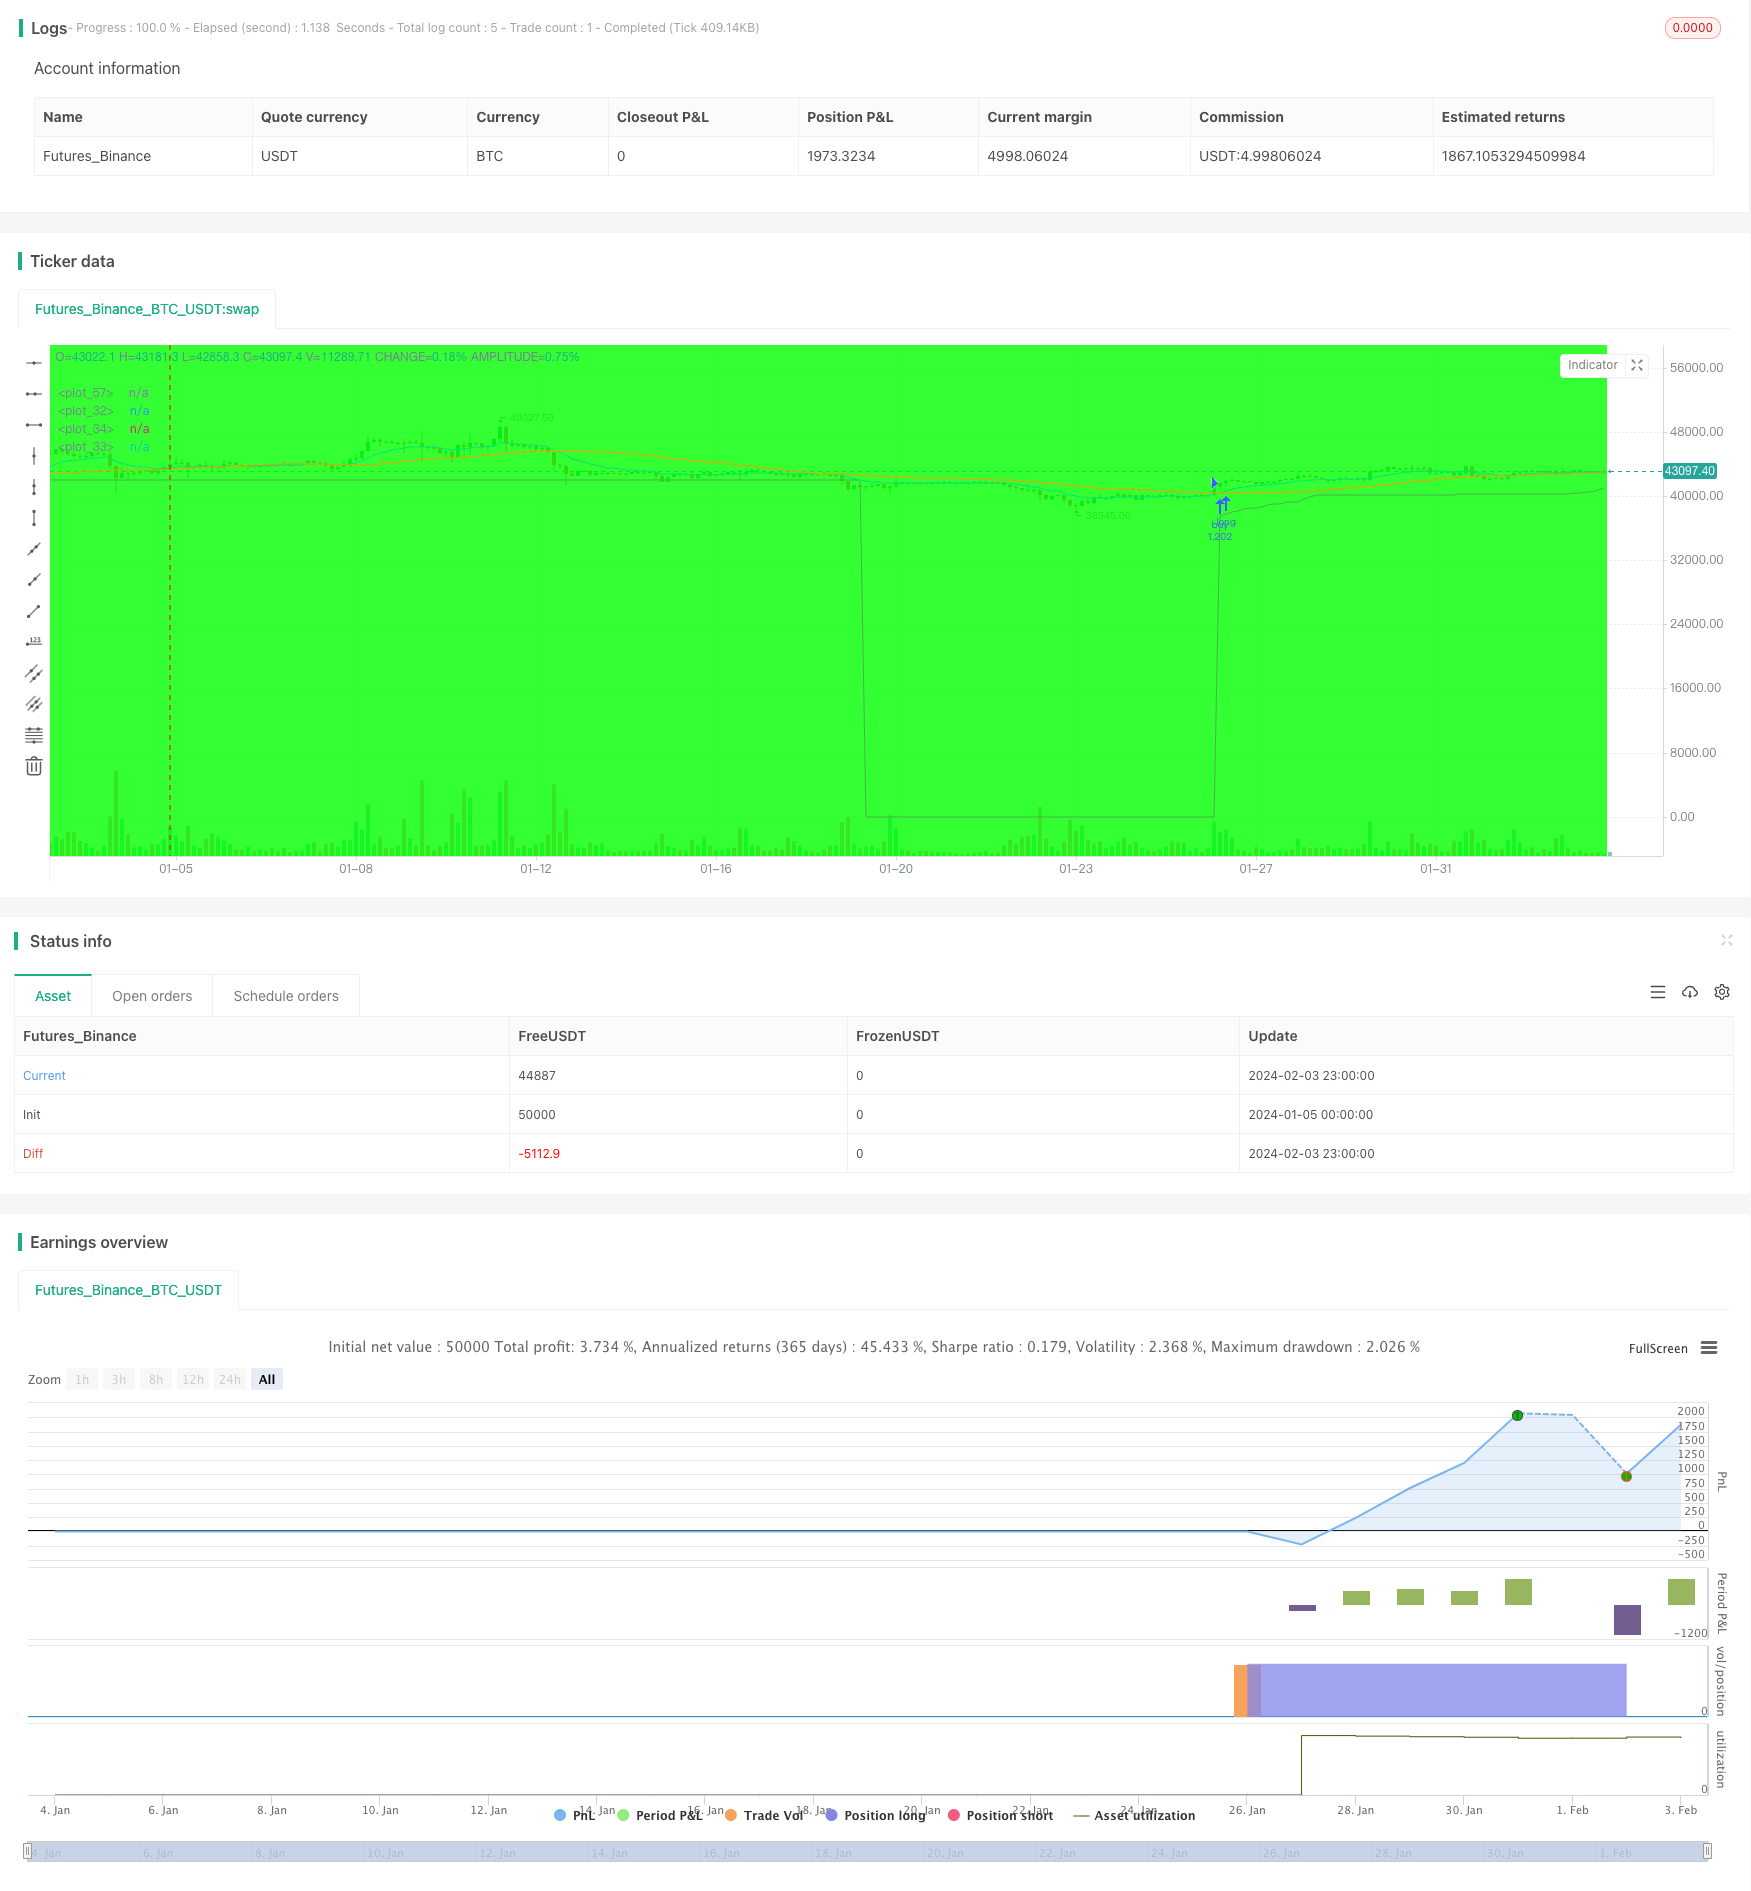
Overview
This strategy generates buy signals when the fast moving average crosses over the slow moving average. At the same time, it calculates the trailing stop loss price based on Average True Range to set sell signals. This strategy can effectively track market trends and cut losses in a timely manner when profit-taking.
Principles
- Fast Moving Average (EMA): 12-day Exponential Moving Average that responds quickly to price changes.
- Slow Moving Average (SMA): 45-day Simple Moving Average that depicts medium to long term trends.
- Buy signals are generated when the fast MA crosses over the slow MA.
- The 15-day Average True Range (ATR) is calculated as the benchmark for stop loss.
- Set the trailing stop loss amplitude based on ATR (e.g. 6 x ATR) and update stop price in real time.
- Sell signals are generated when price drops below the stop loss price.
This strategy combines the advantages of trend following and stop loss management. It can track medium to long term trends and control single trade loss through stop loss.
Advantage Analysis
- MA combos effectively identify trends and increase signal reliability.
- Dynamic trailing stop loss timely stops loss to avoid fund damages.
- ATR-based stop loss makes stop price reasonable and prevents oversensitivity.
- The strategy logic is simple and parameters are flexible.
Risk Analysis
- MAs have lags that may miss short-term chances.
- Excessive loose stop loss undermines profitability.
- Excessive tight stop loss increases trade frequency and commission fees.
- Changing volatility may influence ATR parameter stability.
Parameters can be optimized to balance stop loss amplitude. Other indicators can also be combined to improve entry timing.
Optimization Directions
- Test more parameter combinations to find the optimal MAs.
- Adjust ATR multiplier according to specific stock characteristics.
- Add filtering conditions like volume indicators to avoid unnecessary trades.
- Accumulate more historical data to test parameter stability.
Conclusion
This strategy successfully combines MA's trend following ability and ATR's dynamic trailing stop loss. Parameters can be optimized to adapt to different stocks. It forms clear buy and sell boundaries, making logic simple and clear. In conclusion, this dual MA tracking stop loss strategy features stability, simplicity and ease of optimization. It works well as a fundamental strategy for stock trading.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 2005 | Start Year |
| v_input_2 | true | Start Month |
| v_input_3 | true | Start Day |
| v_input_4 | 2050 | Stop Year |
| v_input_5 | 12 | Stop Month |
| v_input_6 | 31 | Stop Day |
| v_input_7 | true | Background |
| v_input_8 | 12 | Exponential MA |
| v_input_9 | 45 | Simple MA |
| v_input_10 | 12 | Stop EMA |
| v_input_11 | 6 | Trailing Stop #ATR |
Source Pine Script
/*backtest
start: 2024-01-05 00:00:00
end: 2024-02-04 00:00:00
period: 3h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=2
//created by XPloRR 24-02-2018

strategy("XPloRR MA-Buy ATR-MA-Trailing-Stop Strategy",overlay=true, initial_capital=1000,default_qty_type=strategy.percent_of_equity,default_qty_value=100)

testStartYear = input(2005, "Start Year")
testStartMonth = input(1, "Start Month")
testStartDay = input(1, "Start Day")
testPeriodStart = timestamp(testStartYear,testStartMonth,testStartDay,0,0)

testStopYear = input(2050, "Stop Year")
testStopMonth = input(12, "Stop Month")
testStopDay = input(31, "Stop Day")
testPeriodStop = timestamp(testStopYear,testStopMonth,testStopDay,0,0)

testPeriodBackground = input(title="Background", type=bool, defval=true)
testPeriodBackgroundColor = testPeriodBackground and (time >= testPeriodStart) and (time <= testPeriodStop) ? #00FF00 : na
bgcolor(testPeriodBackgroundColor, transp=97)

emaPeriod = input(12, "Exponential MA")
smaPeriod = input(45, "Simple MA")
stopPeriod = input(12, "Stop EMA")
delta = input(6, "Trailing Stop #ATR")

testPeriod() => true

emaval=ema(close,emaPeriod)
smaval=sma(close,smaPeriod)
stopval=ema(close,stopPeriod)
atr=sma((high-low),15)

plot(emaval, color=blue,linewidth=1)
plot(smaval, color=orange,linewidth=1)
plot(stopval, color=lime,linewidth=1)

long=crossover(emaval,smaval)
short=crossunder(emaval,smaval)

//buy-sell signal
stop=0
inlong=0
if testPeriod()
    if (long and (not inlong[1]))
        strategy.entry("buy",strategy.long)
        inlong:=1
        stop:=emaval-delta*atr
    else
        stop:=iff((nz(emaval)>(nz(stop[1])+delta*atr))and(inlong[1]),emaval-delta*atr,nz(stop[1]))
        inlong:=nz(inlong[1])
        if ((stopval<stop) and (inlong[1]))
            strategy.close("buy")
            inlong:=0
            stop:=0
else
    inlong:=0
    stop:=0
plot(stop,color=green,linewidth=1)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-05. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-Moving-Average-Tracking-Stop-Loss-Strategy-441073.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dual MA Crossover Trend Tracking StrategyPine Script · Trend following · 1h
- Dual Mode Adaptive Trend Trading Strategy EMA Crossover with ATR Volatility Based Risk Management SystemPine Script · Trend following · 1d
- Dual Moving Average Crossover Dynamic Position Optimization Strategy with EMA Cross Signal SystemPine Script · Trend following · 1h