Strategy vault / Trend following
Dual track Trend Capturing Fusion Strategy
This strategy fuses the 123 Reversal and SMA Ergodic Oscillator sub-strategies to form a trend tracking strategy with dual-track signal filtering. The 123 Reversal strategy judges potential turning points through…
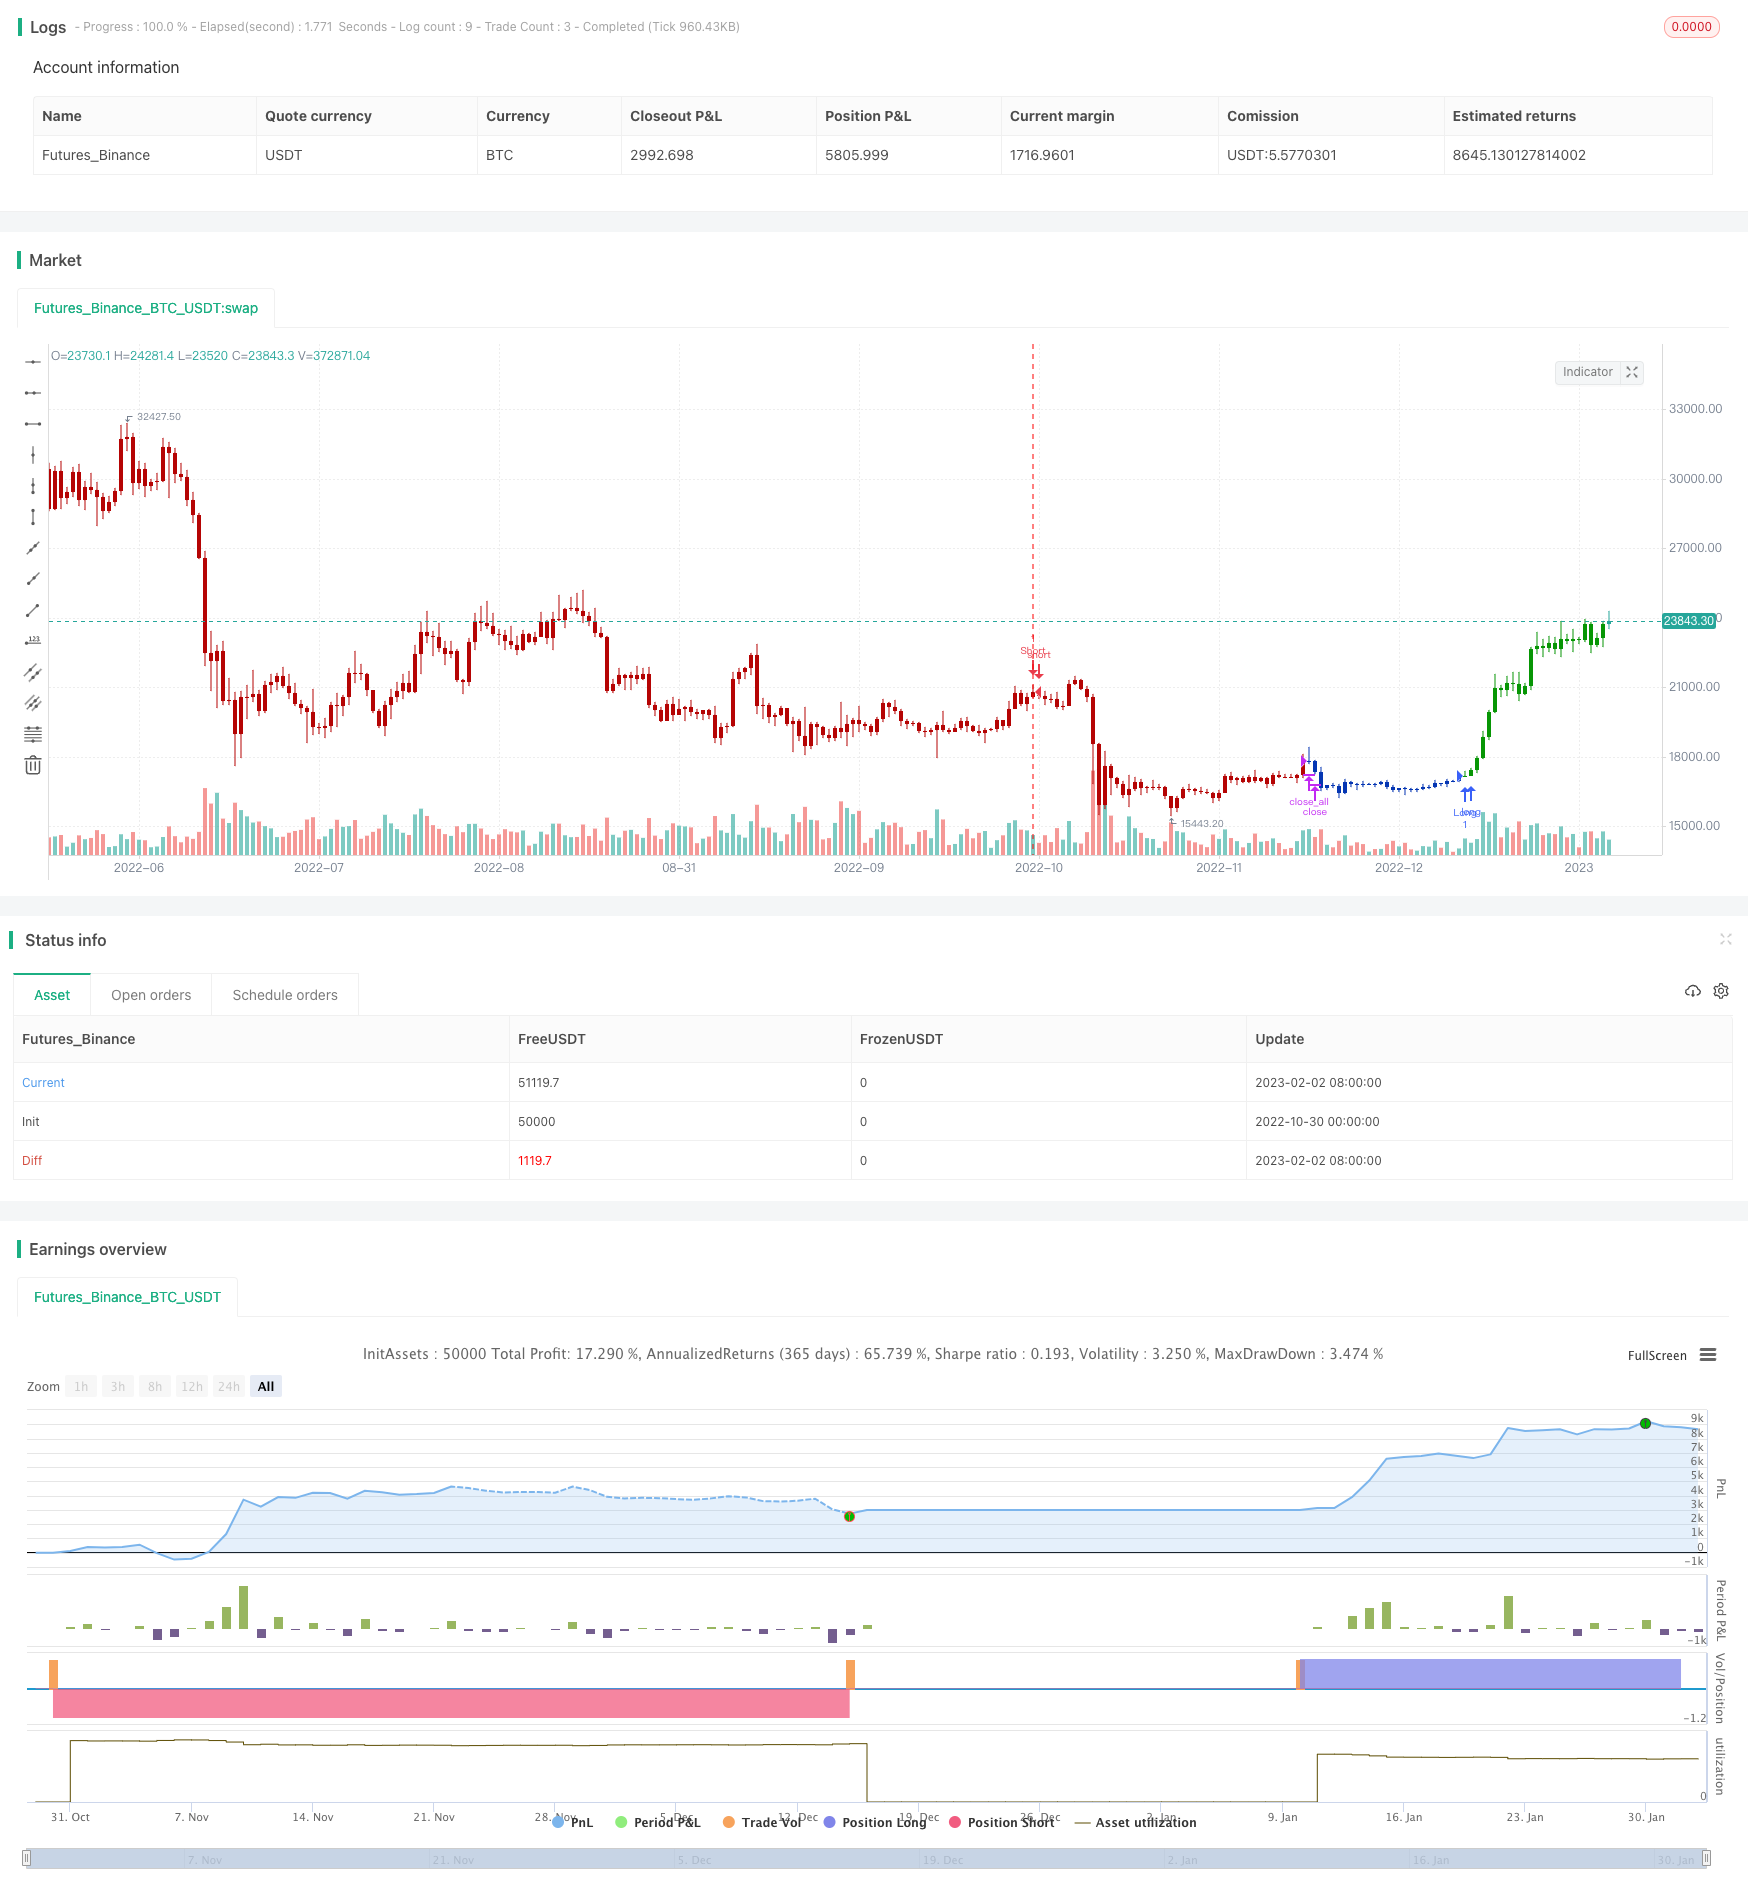
Overview
This strategy fuses the 123 Reversal and SMA Ergodic Oscillator sub-strategies to form a trend tracking strategy with dual-track signal filtering. The 123 Reversal strategy judges potential turning points through candlestick patterns; the SMA Ergodic Oscillator determines trend direction using moving averages. They verify each other to form a dual confirmation mechanism, which can effectively filter out false signals and capture relatively strong trend directions for trend tracking trading.
Strategy Logic
- 123 Reversal Strategy
This strategy is from the system on p183 of Ulf Jensen's book "How I Tripled My Money in the Futures Market". It belongs to the reversal type. When the closing price is higher than the previous close for 2 consecutive days, and the slow line of the 9-day stochastic is below 50, go long; when the closing price is lower than the previous close for 2 consecutive days, and the fast line of 9-day stochastic is above 50, go short.
- SMA Ergodic Oscillator
This indicator is similar to the TSI developed by William Blau, except that SMA oscillator contains a signal line. The SMA Ergodic Indicator uses double moving averages of price minus previous price, and plots an EMA of SMI as signal line to trigger trading signals. The parameters are adjustable for optimization.
Dual confirmation: open positions only when 123 Reversal and SMA Ergodic give signals in the same direction. Keep flat when the signal directions are inconsistent.
Advantages
Integration of multiple indicators forms dual confirmation mechanism, which can effectively filter out false signals.
123 Reversal strategy judges potential reversal points through candlestick patterns. SMA Ergodic Oscillator issues signals based on trend judgment. They complement each other to overcome the limitations of single indicators.
The parameters of SMA Ergodic Oscillator are adjustable for optimization on different products and timeframes. It is flexible.
As a whole trend tracking strategy, it can follow the trend continuously to capture strong momentum.
Risks
The integration and balance between reversal and trend strategies needs continuous optimization, otherwise it may miss turning points or cause huge losses.
Reversal strategies have inherent false trading risks. Parameters need to be adjusted to reduce failure rate.
Pure trend following strategies cannot judge reversals. There are potential loss risks. Position size should be reduced in time to avoid risks.
Parameters need iterative optimization and testing for different products and timeframes. Do not directly apply them.
Enhancements
Adjust parameters of 123 Reversal to reduce false trading frequency.
Adjust parameters of SMA Ergodic Oscillator to optimize indicator sensitivity.
Add stop loss strategy to limit per trade loss.
Incorporate other indicators to judge potential reversals and reduce position size in time.
Test parameters on different products to improve robustness.
Summary
This strategy integrates the advantages of reversal and trend strategies through dual confirmation mechanism, forming strong trend tracking effect. It can effectively filter out noise, follow the trend, and continuously capture high quality trend opportunities. Meanwhile, certain drawdown risks exist. Parameters need continuous optimization and risk control using stop loss. The key is balancing reversal and trend, plus stop loss. It may work better for long term tracking. Overall, this strategy has practical value, and can be used as part of strategy portfolio, or independently.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | ---- 123 Reversal ---- |
| v_input_2 | 14 | Length |
| v_input_3 | true | KSmoothing |
| v_input_4 | 3 | DLength |
| v_input_5 | 50 | Level |
| v_input_6 | true | ---- SMI Ergodic Oscillator ---- |
| v_input_7 | 4 | fastPeriod |
| v_input_8 | 8 | slowPeriod |
| v_input_9 | 3 | SmthLen |
| v_input_10 | 0.5 | TopBand |
| v_input_11 | -0.5 | LowBand |
| v_input_12 | false | Trade reverse |
Source Pine Script
/*backtest
start: 2022-10-30 00:00:00
end: 2023-02-03 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
////////////////////////////////////////////////////////////
//  Copyright by HPotter v1.0 14/07/2021
// This is combo strategies for get a cumulative signal.
//
// First strategy
// This System was created from the Book "How I Tripled My Money In The
// Futures Market" by Ulf Jensen, Page 183. This is reverse type of strategies.
// The strategy buys at market, if close price is higher than the previous close
// during 2 days and the meaning of 9-days Stochastic Slow Oscillator is lower than 50.
// The strategy sells at market, if close price is lower than the previous close price
// during 2 days and the meaning of 9-days Stochastic Fast Oscillator is higher than 50.
//
// Second strategy
// The SMI Ergodic Indicator is the same as the True Strength Index (TSI) developed by
// William Blau, except the SMI includes a signal line. The SMI uses double moving averages
// of price minus previous price over 2 time frames. The signal line, which is an EMA of the
// SMI, is plotted to help trigger trading signals. Adjustable guides are also given to fine
// tune these signals. The user may change the input (close), method (EMA), period lengths
// and guide values.
//
// WARNING:
// - For purpose educate only
// - This script to change bars colors.
////////////////////////////////////////////////////////////
Reversal123(Length, KSmoothing, DLength, Level) =>
    vFast = sma(stoch(close, high, low, Length), KSmoothing)
    vSlow = sma(vFast, DLength)
    pos = 0.0
    pos := iff(close[2] < close[1] and close > close[1] and vFast < vSlow and vFast > Level, 1,
	         iff(close[2] > close[1] and close < close[1] and vFast > vSlow and vFast < Level, -1, nz(pos[1], 0)))
	pos


SMI_Erg(fastPeriod, slowPeriod,SmthLen, TopBand,LowBand) =>
    pos = 0.0
    xPrice = close
    xPrice1 = xPrice - xPrice[1]
    xPrice2 = abs(xPrice - xPrice[1])
    xSMA_R = ema(ema(xPrice1,fastPeriod),slowPeriod)
    xSMA_aR = ema(ema(xPrice2, fastPeriod),slowPeriod)
    xSMI = xSMA_R / xSMA_aR
    xEMA_SMI = ema(xSMI, SmthLen)
    pos:= iff(xEMA_SMI < LowBand, -1,
    	   iff(xEMA_SMI > TopBand, 1, nz(pos[1], 0)))
    pos

strategy(title="Combo Backtest 123 Reversal & SMI Ergodic Oscillator", shorttitle="Combo", overlay = true)
line1 = input(true, "---- 123 Reversal ----")
Length = input(14, minval=1)
KSmoothing = input(1, minval=1)
DLength = input(3, minval=1)
Level = input(50, minval=1)
//-------------------------
line2 = input(true, "---- SMI Ergodic Oscillator ----")
fastPeriod = input(4, minval=1)
slowPeriod = input(8, minval=1)
SmthLen = input(3, minval=1)
TopBand = input(0.5, step=0.1)
LowBand = input(-0.5, step=0.1)
reverse = input(false, title="Trade reverse")
posReversal123 = Reversal123(Length, KSmoothing, DLength, Level)
posSMI_Erg = SMI_Erg(fastPeriod, slowPeriod,SmthLen, TopBand,LowBand )
pos = iff(posReversal123 == 1 and posSMI_Erg == 1 , 1,
	   iff(posReversal123 == -1 and posSMI_Erg == -1, -1, 0))
possig = iff(reverse and pos == 1, -1,
          iff(reverse and pos == -1 , 1, pos))
if (possig == 1 )
    strategy.entry("Long", strategy.long)
if (possig == -1 )
    strategy.entry("Short", strategy.short)
if (possig == 0)
    strategy.close_all()
barcolor(possig == -1 ? #b50404: possig == 1 ? #079605 : #0536b3 )Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-06. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-track-Trend-Capturing-Fusion-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- EMA AROON ASHPine Script · Trend following · 3m
- EMA SMA Multi Indicator Comprehensive Trend Following StrategyPine Script · Trend following · 1h
- EMA200 and Stochastic RSI StrategyPine Script · Trend following · 1h
- Intraday Stochastic Oscillator with Double Moving Average Crossover StrategyPine Script · Trend following · 1d
- Multi Indicator Trend Divergence Quantitative Trading StrategyPine Script · Trend following · 1d
- Multifactor Driven Trend Trading StrategyPine Script · Trend following · 1m