Dynamic Envelope Moving Average Strategy
This strategy is based on moving average and dynamic envelope lines to implement both long and short trading. It tracks price breakouts beyond envelope lines to establish positions and closes positions when price…
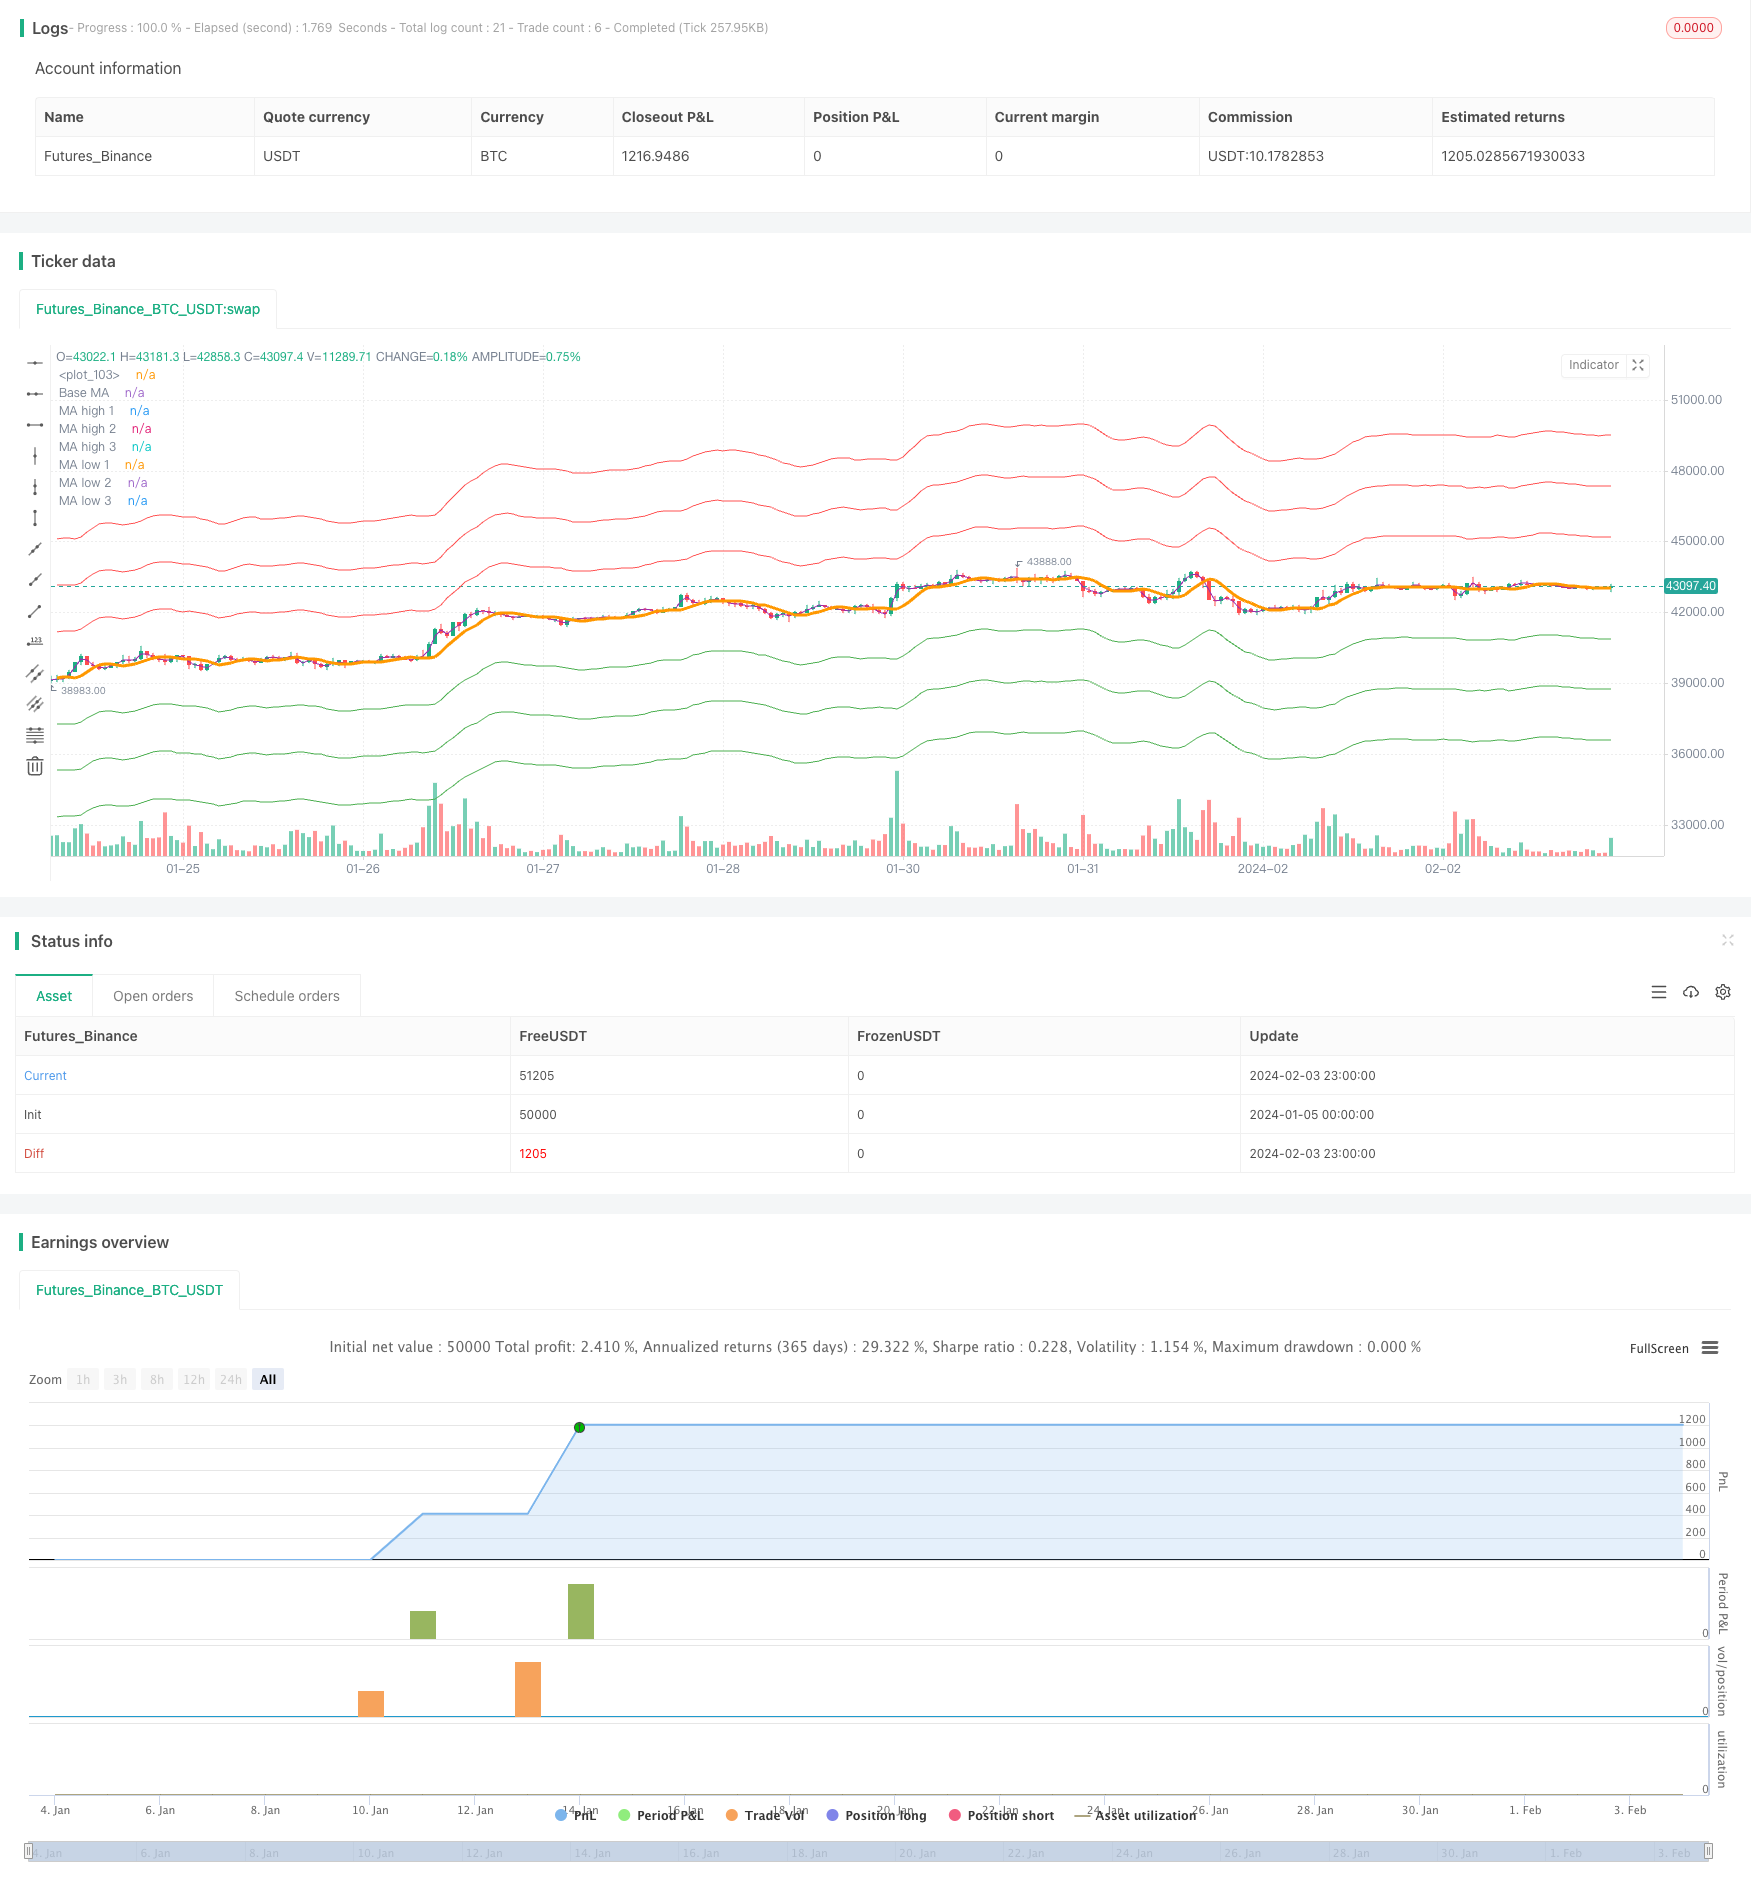
Overview
This strategy is based on moving average and dynamic envelope lines to implement both long and short trading. It tracks price breakouts beyond envelope lines to establish positions and closes positions when price breaks back below the baseline moving average. This strategy works well for stocks and cryptocurrencies with obvious trends.
Strategy Logic
Firstly, this strategy calculates the baseline moving average based on user-defined moving average type and length. Common moving averages include SMA, EMA etc.
Then, it calculates the upper and lower envelope lines based on user-defined percentage parameters. For example, 5% means establishing positions when price fluctuates 5% beyond baseline moving average. The number of envelope lines can be customized.
Regarding entry rules, go long when price breaks below lower envelope line, go short when price breaks above upper envelope line. The rules are simple and straightforward.
Lastly, close all positions when price breaks back below the baseline moving average. This is an exit point to trail the trend.
Notably, this strategy implements partial position establishment. If multiple envelope lines exist, capital will be allocated proportionately. This prevents the risk of one-sided bets.
Advantage Analysis
The biggest pros of this strategy:
Automatical trend following. Using moving average to determine trend direction is a well-established method.
Filtering out some noise with envelope lines, preventing excessive sensitive trading. Reasonable parameter setting can greatly improve strategy profitability.
Partial position establishment enhances strategy resilience. Even if one side fails, the other side can keep running well. This optimizes overall risk-reward ratio.
Customizable moving average and envelope line number. This increases flexibility for parameter tuning based on different products.
Risk Analysis
The main risks of this strategy:
Moving average system is not sensitive to golden cross signals. It may miss some opportunities if no obvious trend exists.
Too wide envelope line setting may increase trading frequency and slippage risk. Too narrow setting may miss larger moves. Finding the balance requires thorough testing.
This strategy likely encounters more whipsaws in ranging markets. So trending products are preferable.
Partial position establishment limits per trade profit. If seeking one-sided bets, further optimization is needed.
Optimization Directions
The main directions to optimize this strategy:
Replace with other entry/exit indicators like KDJ etc. Or add filters with multiple indicators.
Add stop profit/loss logic. This locks in some profit and actively mitigates some risks.
Optimize parameters to find the best moving average and envelope combinations. Requires extensive backtesting and optimization.
Incorporate deep learning etc. for smart parameter tuning. Constantly learn and update over time.
Consider product and market differences, set multiple parameter sets suiting different trading environments. This greatly improves strategy robustness.
Conclusion
In conclusion, this dynamic envelope moving average strategy works very well for trend trading. It is simple, efficient, easy to understand and optimize. As a basic strategy, it has great plasticity and extensibility. When combined with more complex systems, it can be further enhanced for higher returns and better risk-adjusted metrics. So it serves as an excellent foundation for quantitative trading strategies.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_bool_1 | true | Long Positions |
| v_input_bool_2 | true | Short Positions |
| v_input_1_ohlc4 | 0 | (?Base MA)Source: ohlc4 | high | low | open | hl2 | hlc3 | hlcc4 | close |
| v_input_int_1 | 5 | Base Mooving Average Window |
| v_input_string_1 | 0 | MA Type: 1. SMA | 2. PCMA | 3. EMA | 4. WMA | 5. DEMA | 6. ZLEMA | 7. HMA |
| v_input_float_1 | 0.05 | (?Envelopes)Envelope 1 |
| v_input_float_2 | 0.1 | Envelope 2 |
| v_input_float_3 | 0.15 | Envelope 3 |
| v_input_float_4 | false | Envelope 4 |
| v_input_float_5 | false | Envelope 5 |
Source Pine Script
/*backtest
start: 2024-01-05 00:00:00
end: 2024-02-04 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Envelope Strategy", overlay=true, default_qty_type=strategy.percent_of_equity, default_qty_value=100, initial_capital=1000, pyramiding = 5, commission_type=strategy.commission.percent, commission_value=0.0)

// CopyRight Crypto Robot

src = input(ohlc4, title="Source", group = "Base MA")
ma_base_window = input.int(5, "Base Mooving Average Window", step = 1, group = "Base MA")
ma_type = input.string(defval='1. SMA', options=['1. SMA', '2. PCMA', '3. EMA', '4. WMA', '5. DEMA', '6. ZLEMA', '7. HMA'], title='MA Type', group = "Base MA")


envelope_1_pct = input.float(0.05, "Envelope 1", step = 0.01, group = "Envelopes")
envelope_2_pct = input.float(0.10, "Envelope 2", step = 0.01, group = "Envelopes")
envelope_3_pct = input.float(0.15, "Envelope 3", step = 0.01, group = "Envelopes")
envelope_4_pct = input.float(0.0, "Envelope 4", step = 0.01, group = "Envelopes")
envelope_5_pct = input.float(0.0, "Envelope 5", step = 0.01, group = "Envelopes")

use_longs = input.bool(true, 'Long Positions')
use_short = input.bool(true, 'Short Positions')

total_envelope = 0
if envelope_1_pct > 0
    total_envelope := total_envelope + 1
if envelope_2_pct > 0
    total_envelope := total_envelope + 1
if envelope_3_pct > 0
    total_envelope := total_envelope + 1
if envelope_4_pct > 0
    total_envelope := total_envelope + 1
if envelope_5_pct > 0
    total_envelope := total_envelope + 1

// ---------------------------------------------
// -------------- INDICATORS -------------------
ma_function(MA_type, MA_length) =>
    zlema_lag = (MA_length - 1) / 2
    hma_src = MA_type == '7. HMA' ? 2 * ta.wma(src, math.floor(MA_length / 2)) - ta.wma(src, MA_length) : na
    MA_type == '1. SMA' ? ta.sma(src, MA_length) : MA_type == '2. PCMA' ? (ta.highest(high, MA_length) + ta.lowest(low, MA_length)) / 2 : MA_type == '3. EMA' ? ta.ema(src, MA_length) : MA_type == '4. WMA' ? ta.wma(src, MA_length) : MA_type == '5. DEMA' ? 2 * ta.ema(src, MA_length) - ta.ema(ta.ema(src, MA_length), MA_length) : MA_type == '6. ZLEMA' ? ta.ema(src + src - src[zlema_lag], MA_length) : MA_type == '7. HMA' ? ta.wma(hma_src, math.floor(math.sqrt(MA_length))) : na


ma_base = ma_function(ma_type, ma_base_window)

ma_high_1 = envelope_1_pct > 0 ? ma_base * (1 + envelope_1_pct) : na
ma_high_2 = envelope_2_pct > 0 ? ma_base * (1 + envelope_2_pct) : na
ma_high_3 = envelope_3_pct > 0 ? ma_base * (1 + envelope_3_pct) : na
ma_high_4 = envelope_4_pct > 0 ? ma_base * (1 + envelope_4_pct) : na
ma_high_5 = envelope_5_pct > 0 ? ma_base * (1 + envelope_5_pct) : na

ma_low_1 = envelope_1_pct > 0 ? ma_base * (1 - envelope_1_pct) : na
ma_low_2 = envelope_2_pct > 0 ? ma_base * (1 - envelope_2_pct) : na
ma_low_3 = envelope_3_pct > 0 ? ma_base * (1 - envelope_3_pct) : na
ma_low_4 = envelope_4_pct > 0 ? ma_base * (1 - envelope_4_pct) : na
ma_low_5 = envelope_5_pct > 0 ? ma_base * (1 - envelope_5_pct) : na

// ---------------------------------------------
// --------------- STRATEGY --------------------
if use_longs
    if envelope_1_pct > 0 and strategy.opentrades < 1
        strategy.entry('long 1', strategy.long, limit=ma_low_1, qty=(strategy.equity / ma_low_1) * (1 / total_envelope))
    if envelope_2_pct > 0 and strategy.opentrades < 2
        strategy.entry('long 2', strategy.long, limit=ma_low_2, qty=(strategy.equity / ma_low_2) * (1 / total_envelope))
    if envelope_3_pct > 0 and strategy.opentrades < 3
        strategy.entry('long 3', strategy.long, limit=ma_low_3, qty=(strategy.equity / ma_low_3) * (1 / total_envelope))
    if envelope_4_pct > 0 and strategy.opentrades < 4
        strategy.entry('long 4', strategy.long, limit=ma_low_4, qty=(strategy.equity / ma_low_4) * (1 / total_envelope))
    if envelope_5_pct > 0 and strategy.opentrades < 5
        strategy.entry('long 5', strategy.long, limit=ma_low_5, qty=(strategy.equity / ma_low_5) * (1 / total_envelope))


if use_short
    if envelope_1_pct > 0 and strategy.opentrades < 1
        strategy.entry('short 1', strategy.short, limit=ma_high_1, qty=(strategy.equity / ma_high_1) * (1 / total_envelope))
    if envelope_2_pct > 0 and strategy.opentrades < 2
        strategy.entry('short 2', strategy.short, limit=ma_high_2, qty=(strategy.equity / ma_high_2) * (1 / total_envelope))
    if envelope_3_pct > 0 and strategy.opentrades < 3
        strategy.entry('short 3', strategy.short, limit=ma_high_3, qty=(strategy.equity / ma_high_3) * (1 / total_envelope))
    if envelope_4_pct > 0 and strategy.opentrades < 4
        strategy.entry('short 4', strategy.short, limit=ma_high_4, qty=(strategy.equity / ma_high_4) * (1 / total_envelope))
    if envelope_5_pct > 0 and strategy.opentrades < 5
        strategy.entry('short 5', strategy.short, limit=ma_high_5, qty=(strategy.equity / ma_high_5) * (1 / total_envelope))


strategy.exit('close', limit=ma_base)


// ---------------------------------------------
// ------------------ PLOT ---------------------

ma_base_plot = plot(ma_base, title = "Base MA", color = color.orange, linewidth = 3, offset = 1)

ma_high_1_plot = plot(ma_high_1, title = "MA high 1", color = color.red, offset = 1)
ma_high_2_plot = plot(ma_high_2, title = "MA high 2", color = color.red, offset = 1)
ma_high_3_plot = plot(ma_high_3, title = "MA high 3", color = color.red, offset = 1)
ma_high_4_plot = plot(ma_high_4, title = "MA high 4", color = color.red, offset = 1)
ma_high_5_plot = plot(ma_high_5, title = "MA high 5", color = color.red, offset = 1)

ma_low_1_plot = plot(ma_low_1, title = "MA low 1", color = color.green, offset = 1)
ma_low_2_plot = plot(ma_low_2, title = "MA low 2", color = color.green, offset = 1)
ma_low_3_plot = plot(ma_low_3, title = "MA low 3", color = color.green, offset = 1)
ma_low_4_plot = plot(ma_low_4, title = "MA low 4", color = color.green, offset = 1)
ma_low_5_plot = plot(ma_low_5, title = "MA low 5", color = color.green, offset = 1)

plot(ohlc4, color=color.purple)

// use_period = input.bool(false, "Période spécifique ?", group="periode")
// startDate = input.time(timestamp("01 Jan 2020"), "Date de début", group="periode")
// endDate = input.time(timestamp("01 Jan 2025"), "Date de fin", group="periode")


//------------------------------------------
//-------------Indicateurs------------------

// inDateRange = use_period ? ((time >= startDate) and (time < endDate)) : true

// //--------------Backtest-------------------

// strategy_pnl = strategy.netprofit + strategy.openprofit
// bnh_strategy_pnl_pcnt = (strategy_pnl / strategy.initial_capital) * 100

// float bnh_start_bar = na
// bnh_start_bar := na(bnh_start_bar[1]) or inDateRange != true? close : bnh_start_bar[1]
// float bnl_buy_hold_equity = na
// bnl_buy_hold_equity :=  inDateRange == true ? ((close - bnh_start_bar)/bnh_start_bar) * 100 : bnl_buy_hold_equity[1]

// bnh_vs_diff = bnh_strategy_pnl_pcnt - bnl_buy_hold_equity
// bnh_diff_color = bnh_vs_diff > 0 ? color.new(color.green, inDateRange ? 60 : 100) : color.new(color.red, inDateRange ? 60 : 100)

// var Table = table.new(position.top_right, columns = 2, rows = 4, border_width = 1, bgcolor = color.black, border_color = color.gray)
// table.cell(table_id = Table, column = 0, row = 0, text_color=(bnh_strategy_pnl_pcnt>bnl_buy_hold_equity)?color.gray:color.green, text_size = size.normal, text = "Buy & hold profit")
// table.cell(table_id = Table, column = 1, row = 0, text_color=(bnh_strategy_pnl_pcnt>bnl_buy_hold_equity)?color.gray:color.green, text_size = size.normal, text = str.tostring(bnl_buy_hold_equity, '#.##') + ' %')
// table.cell(table_id = Table, column = 0, row = 1, text_color=(bnh_strategy_pnl_pcnt<bnl_buy_hold_equity)?color.gray:color.green, text_size = size.normal, text = "Strategy profit")
// table.cell(table_id = Table, column = 1, row = 1, text_color=(bnh_strategy_pnl_pcnt<bnl_buy_hold_equity)?color.gray:color.green, text_size = size.normal, text = str.tostring(bnh_strategy_pnl_pcnt, '#.##') + ' %')
// table.cell(table_id = Table, column = 0, row = 2, text_color=color.yellow, text_size = size.normal, text = "Date de début")
// table.cell(table_id = Table, column = 1, row = 2, text_color=color.yellow, text_size = size.normal, text = str.format("{0,date,dd-MM-YYYY}",strategy.closedtrades.entry_time(1)))Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-05. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dynamic-Envelope-Moving-Average-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive Multi Period Trading Strategy Based on Wave Trend Momentum BreakoutPine Script · Breakout · 2h
- BB Breakout StrategyPine Script · Breakout · 1d
- BMSB Breakout Strategy BMSBPine Script · Breakout · 1h
- Bollinger Band T3 Moving Average StrategyPine Script · Breakout · 10m
- Bollinger Bands Dual track Breakthrough StrategyPine Script · Breakout · 30m
- Bollinger Breakout StrategyPine Script · Breakout · 30m