Dynamic Moving EMAs Combination Quant Strategy
This strategy is a dynamic moving average combination strategy that works on multiple timeframes. It usesExponential Moving Averages (EMAs) of different lengths for trend judgment and entry/exit signals. The "MAX" in…
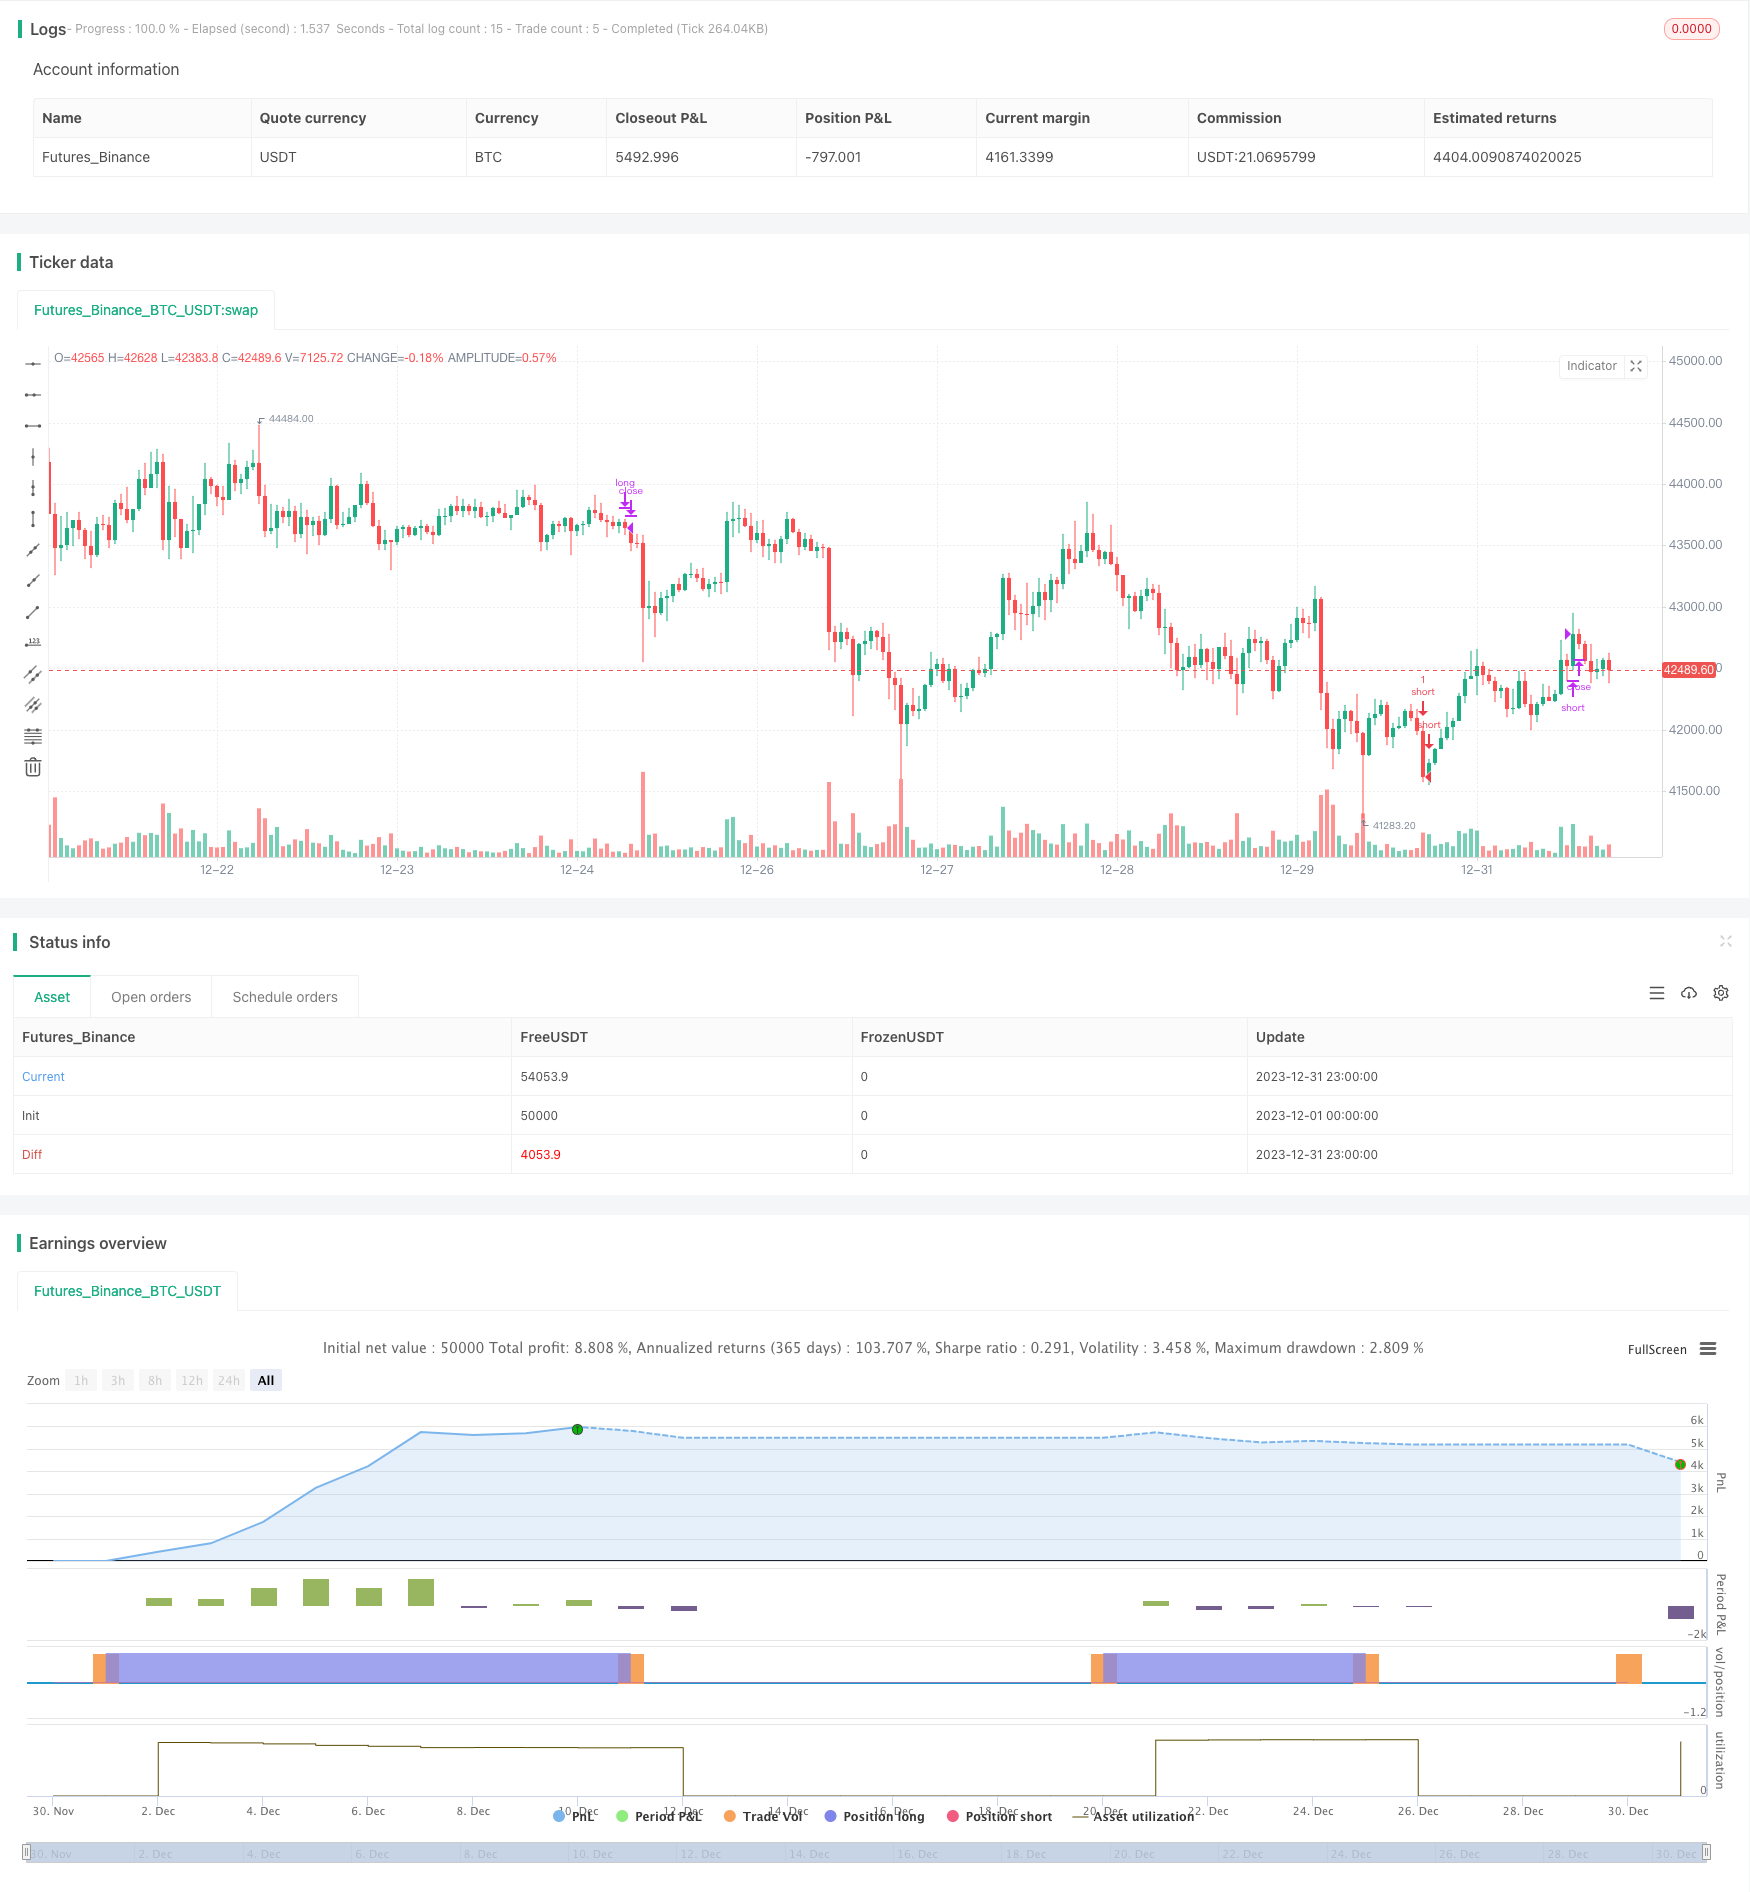
Overview
This strategy is a dynamic moving average combination strategy that works on multiple timeframes. It usesExponential Moving Averages (EMAs) of different lengths for trend judgment and entry/exit signals. The "MAX" in the strategy name stands for multiple EMAs, and "Dynamic" means the EMA lengths are adjustable.
Strategy Logic
The strategy employs 7 EMAs moving at different speeds, from the fastest to the slowest: 3-period EMA, 15-period EMA, 19-period EMA, 50-period EMA, 100-period EMA, 150-period EMA and 200-period EMA. These 7 EMAs are arranged in a trapezoidal formation. To generate long and short signals, the close price needs to break through these EMAs successively to ensure a strong post-reversal trend entry.
In addition, the strategy also incorporates price breaking recent high and close price crossing historical highs to confirm long signals, and uses breaking recent low and close price crossing historical lows to confirm short signals. This helps avoid false breakouts.
The exit rules require the close price to break the faster EMAs successively towards the slower EMAs, indicating a trend reversal. Alternatively, if the latest bar's low/high breaks more than 4 EMAs, it is also an exit signal for that position.
Advantage Analysis
- Using 7 EMAs of different speeds forming a trapezoid shape can identify trend reversal points more precisely
- Incorporating new high/low and historical highs/lows avoids false breakout signals
- The strict dual exit rules allow timely stop loss
Risk Analysis
- No stop loss mechanism leads to huge loss potential
- The dual exit rules may cause premature exit
- Too many faster EMAs generate more noise and increase trading frequency and commission cost
Solutions:
- Add fixed percentage stop loss and trailing stop loss
- Adjust exit EMA lengths to lower the strictness of dual exit rules
- Increase EMA lengths to reduce trading frequency
Optimization Directions
- Add stop loss mechanisms like fixed percentage stop loss, trailing stop loss etc
- Optimize EMA parameters to find the best combination
- Add other indicators like MACD, ATR, KDJ etc to filter signals
- Combine with range/channel strategies to catch secondary moves in trends
- Consider adding position sizing rules
Conclusion
The strategy has a clear logic of using 7 EMAs of different speeds to determine trends and dual exit rules to detect reversals. But there is no stop loss mechanism leading to huge loss risk, and it may exit prematurely. Improvements can be made in aspects like adding stop loss, parameter tuning, indicator filtering to turn it into a solid trading system.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 3 | Length |
| v_input_2 | 15 | Length2 |
| v_input_3 | 19 | Length3 |
| v_input_4 | 50 | Length4 |
| v_input_5 | 100 | Length44 |
| v_input_6 | 150 | Length5 |
| v_input_7 | 171 | Length6 |
| v_input_8 | 172 | Length66 |
| v_input_9_close | 0 | xPrice: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_10 | true | From Day |
| v_input_11 | true | From Month |
| v_input_12 | 2000 | From Year |
| v_input_13 | 31 | To Day |
| v_input_14 | 12 | To Month |
| v_input_15 | 2020 | To Year |
Source Pine Script
/*backtest
start: 2023-12-01 00:00:00
end: 2023-12-31 23:59:59
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy(title="Crypto MAX Trend", shorttitle="Crypto MAX", overlay = true  )
Length = input(3, minval=1)
Length2 = input(15, minval=1)
Length3 = input(19, minval=1)
//Length33 = input(25, minval=1)
Length4 = input(50, minval=1)
Length44 = input(100, minval=1)
Length5 = input(150, minval=1)
Length6 = input(171, minval=1)
Length66 = input(172, minval=1)

xPrice = input(close)

xEMA1 = ema(xPrice, Length)
xEMA2 = ema(xPrice, Length2)
xEMA3 = ema(xPrice, Length3)
//xEMA33 = ema(xPrice, Length33)
xEMA4 = ema(xPrice, Length4)
xEMA44 = ema(xPrice, Length44)
xEMA5 = ema(xPrice, Length5)
xEMA6 = ema(xPrice, Length6)
xEMA66 = ema(xPrice, Length66)

// plot(xEMA1, color=color.white)
// plot(xEMA2, color=color.red)
// plot(xEMA3, color=color.green)
// plot(xEMA4, color=color.purple)
// plot(xEMA44, color=color.gray)
// plot(xEMA5, color=color.maroon)
// plot(xEMA6, color=color.blue)
// plot(xEMA66, color=color.orange)


fromDay = input(defval = 1, title = "From Day", minval = 1, maxval = 31)
fromMonth = input(defval = 1, title = "From Month", minval = 1, maxval = 12)
fromYear = input(defval = 2000, title = "From Year", minval = 1970)
 //monday and session
// To Date Inputs
toDay = input(defval = 31, title = "To Day", minval = 1, maxval = 31)
toMonth = input(defval = 12, title = "To Month", minval = 1, maxval = 12)
toYear = input(defval = 2020, title = "To Year", minval = 1970)

startDate = timestamp(fromYear, fromMonth, fromDay, 00, 00)
finishDate = timestamp(toYear, toMonth, toDay, 00, 00)
time_cond = true


long = close >  xEMA1 and xEMA1 > xEMA2 and xEMA2 > xEMA3  and xEMA3 > xEMA4  and xEMA4 > xEMA44 and xEMA44 > xEMA5 and xEMA5> xEMA6  and xEMA6> xEMA66  and close > high[1] and high[1] > high[2] and close > high[3] and close > high[4] and close > high[5] and high[5] > high[6] and time_cond
short = close < xEMA1 and xEMA1 < xEMA2 and xEMA2 < xEMA3  and xEMA3 < xEMA4  and xEMA4 < xEMA44 and xEMA44 < xEMA5 and xEMA5< xEMA6 and  xEMA6< xEMA66 and close < low[1] and low[1] < low[2] and close < low[3] and close < low[4] and close< low[5] and low[5] < low[6] and time_cond

notlong = close < xEMA1
strategy.entry("long",1,when=long)
strategy.entry("short",0,when=short)


exitlong1 = xEMA1 < xEMA2 and xEMA2 < xEMA3 and xEMA3 < xEMA4
exitlong2 = crossunder(low,xEMA1) and crossunder(low,xEMA2) and crossunder(low,xEMA3) and crossunder(low,xEMA4)
exitshort1 = xEMA1 > xEMA2 and xEMA2 > xEMA3 and xEMA3 > xEMA4
exitshort2 = crossover(high,xEMA1) and crossover(high,xEMA2) and crossover(high,xEMA3) and crossover(high,xEMA4)

strategy.close("long", when = exitlong1 or exitlong2)
strategy.close("short", when= exitshort1 or exitshort2)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-22. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dynamic-Moving-EMAs-Combination-Quant-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Dual Breakout Volatility Channel StrategyPine Script · Breakout · 1h
- Kana Candle Breakout Strategy Based on Moving Average and Support ResistancePine Script · Breakout · 1h
- MA Trendline Breakthrough StrategyPine Script · Breakout · 1d
- Momentum Breakout Moving Average StrategyPine Script · Breakout · 1d
- Momentum Breakout Trading Strategy 440964Pine Script · Breakout · 5m
- Moving Average Crossover and Upper Rail Breakthrough Impulse StrategyPine Script · Breakout · 1m