Gamma Weighted Momentum Based Bitcoin Futures Intelligent Trading Strategy
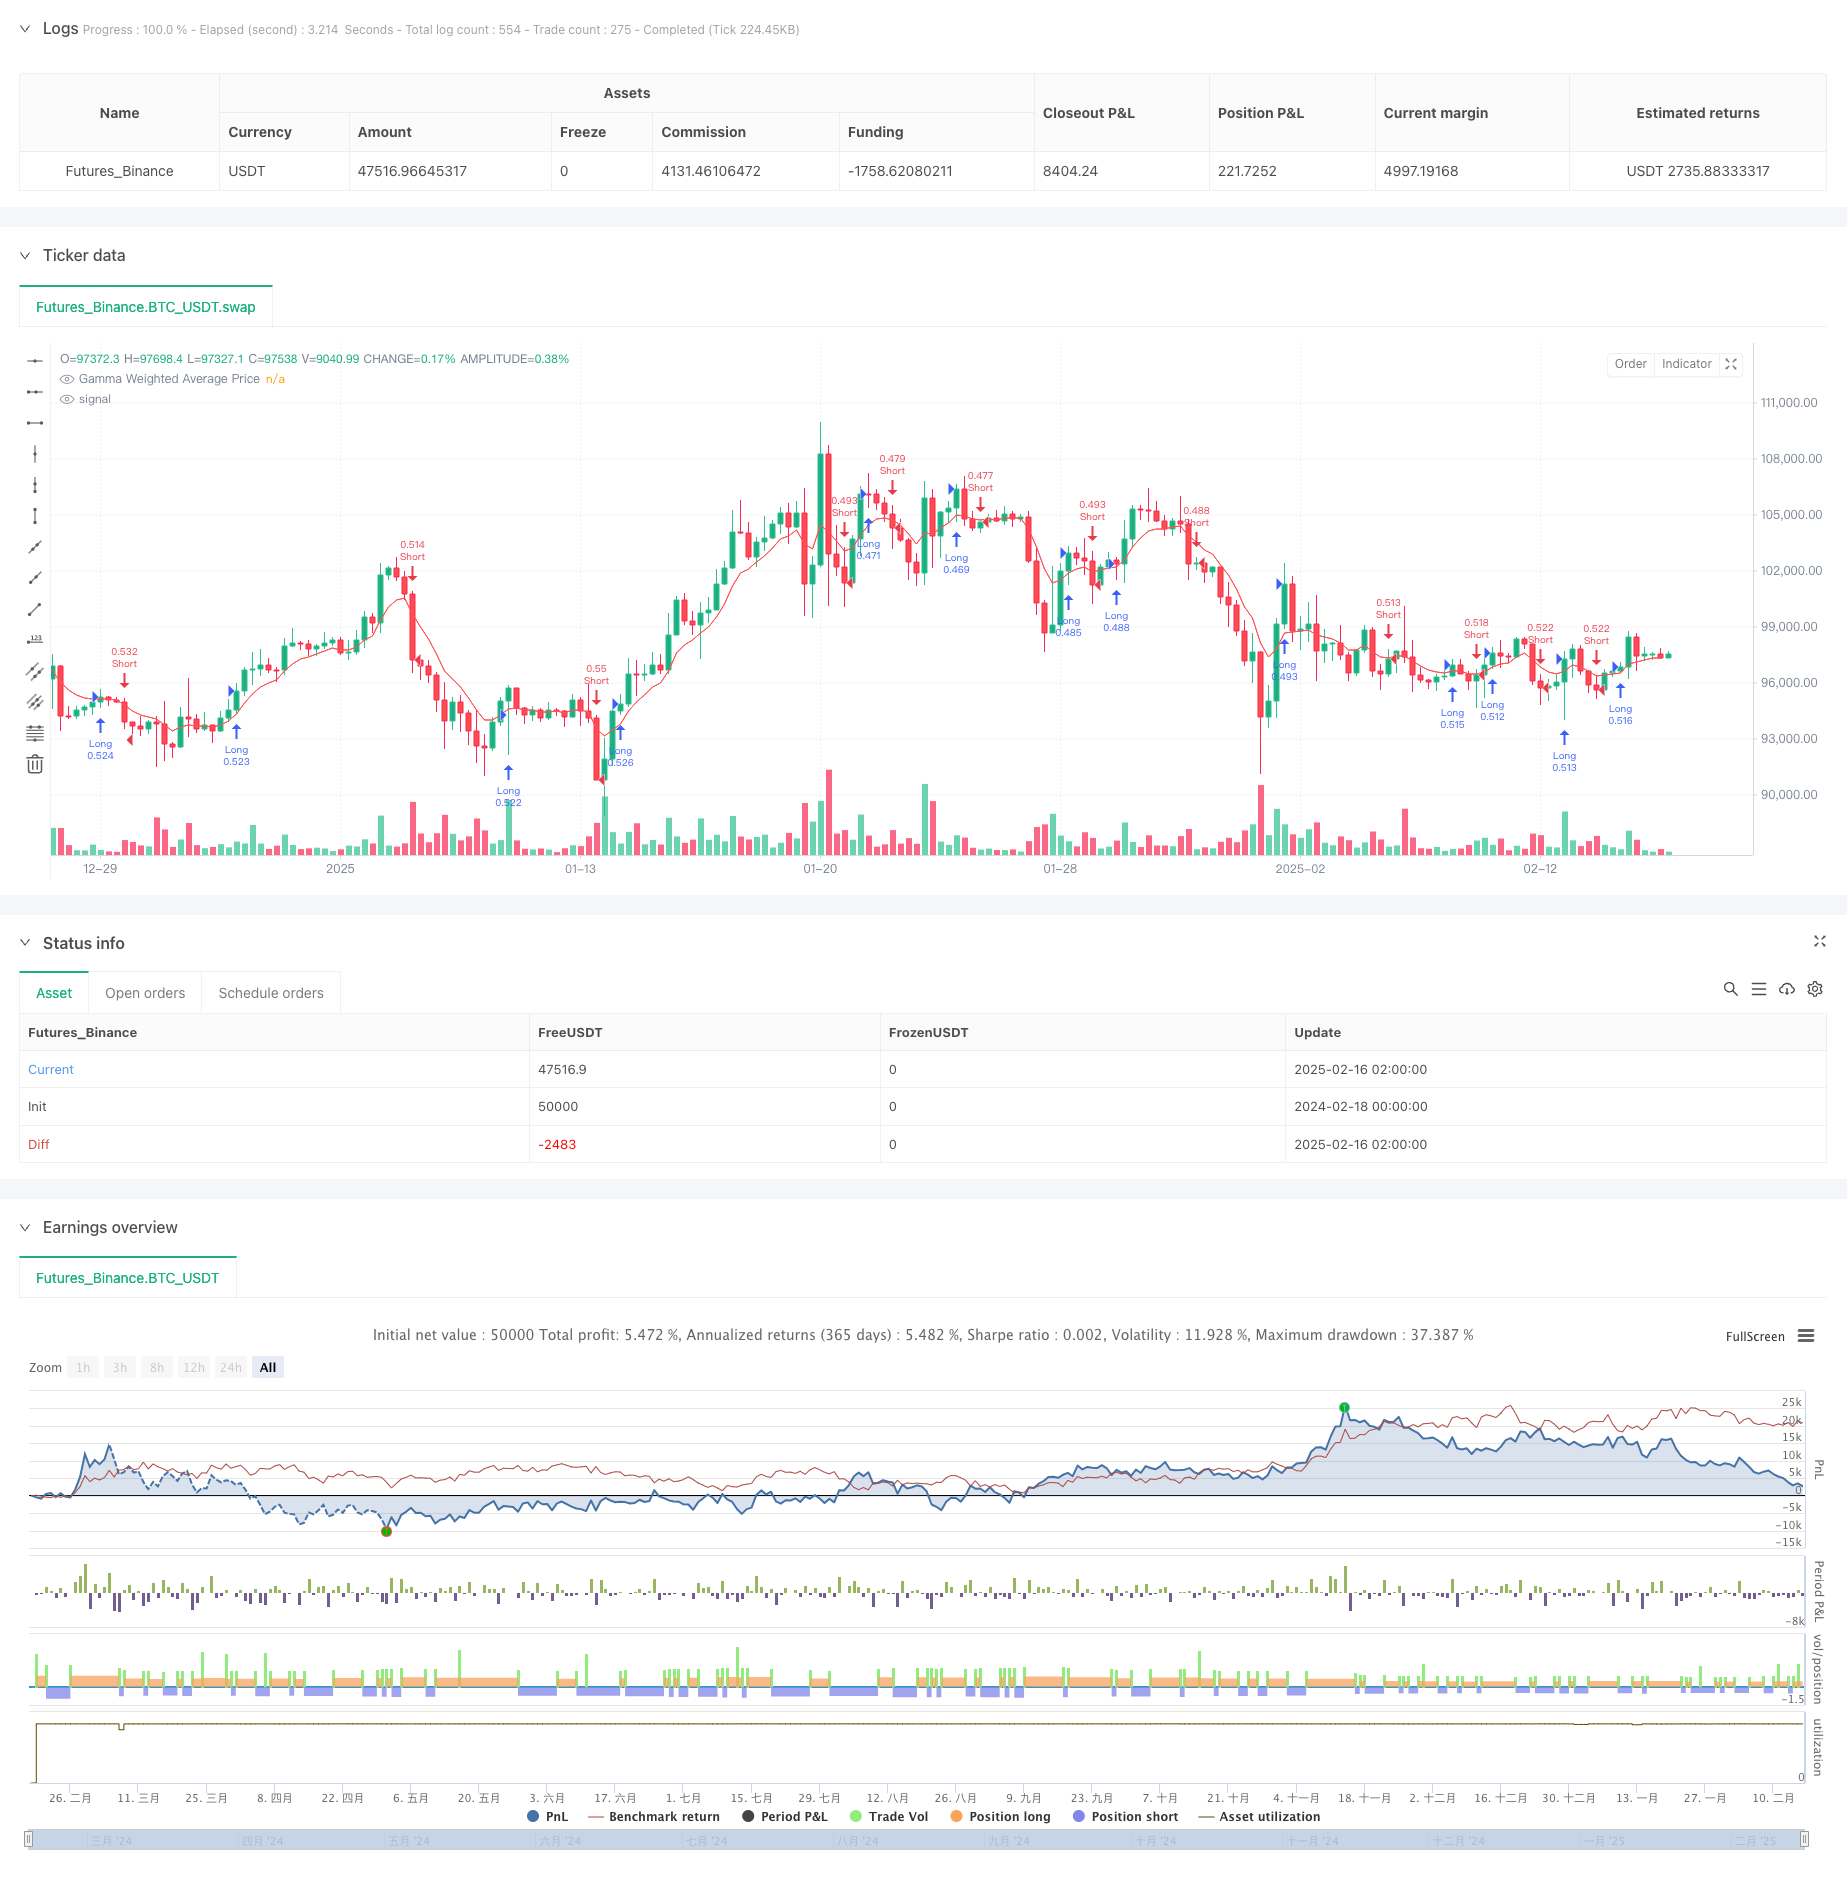
This strategy is a quantitative trading system that combines Gamma-Weighted Average Price (GWAP) and momentum analysis. It predicts price movements by applying gamma weighting to historical price data and…
Overview
This strategy is a quantitative trading system that combines Gamma-Weighted Average Price (GWAP) and momentum analysis. It predicts price movements by applying gamma weighting to historical price data and incorporating short-term momentum indicators. The core concept lies in assigning higher weights to recent prices through the gamma factor, thereby increasing sensitivity to recent market trends.
Strategy Principle
The strategy is based on two core theories: momentum effect and gamma-weighted pricing. For momentum, it leverages the tendency of price trends to persist in financial markets. For weighting, it applies exponential decay weighting to historical prices through a gamma factor (range 0.5-1.5). In implementation, the strategy calculates GWAP as a benchmark price, initiating long positions when prices are above GWAP with three consecutive periods of upward trend, and short positions under opposite conditions.
Strategy Advantages
- Strong adaptability: The gamma weighting mechanism can dynamically adjust weights assigned to historical data based on market conditions.
- Comprehensive risk control: GWAP serves as a reliable benchmark price for trading decisions.
- High computational efficiency: The strategy employs array storage and loop calculations to optimize performance.
- Good parameter adjustability: Key parameters like gamma factor and calculation period can be flexibly adjusted according to market conditions.
Strategy Risks
- Market volatility risk: May generate frequent false signals in choppy markets.
- Parameter sensitivity: Strategy performance is highly dependent on gamma factor selection, requiring continuous optimization.
- Computational delay: Processing large amounts of historical data may lead to execution delays in live trading.
- Trend reversal risk: Strategy response may lag during sudden market trend reversals.
Strategy Optimization Directions
- Introduce volatility-adaptive mechanisms to dynamically adjust the gamma factor.
- Add multi-timeframe trend confirmation mechanisms.
- Optimize computational efficiency by reducing array operations.
- Incorporate market sentiment indicators to improve prediction accuracy.
- Implement dynamic stop-loss mechanisms to enhance risk control.
Summary
The strategy achieves intelligent market trend tracking by combining gamma weighting and momentum analysis. Its core advantage lies in the ability to dynamically adjust weight distribution according to market conditions while maintaining high computational efficiency. Although there are certain market risks and parameter sensitivity issues, the strategy shows good application prospects through continuous optimization and improvement.
Source Pine Script
/*backtest
start: 2024-02-18 00:00:00
end: 2025-02-16 08:00:00
period: 6h
basePeriod: 6h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=6
strategy("BTC Future Gamma-Weighted Momentum Model (BGMM)", shorttitle="BGMM", overlay=true,
         default_qty_type=strategy.cash, default_qty_value=50000,
         slippage=1, commission_value=0.01)

// Inputs
length = input.int(60, "Length for GWAP Calculation")
gamma_factor = input.float(0.75, "Gamma Weight Factor", minval=0.5, maxval=1.5, step=0.01)

// Helper Functions
var float cumulative_weighted_price = na
var float cumulative_weight = na

price = (high + low + close) / 3  // Typical price as a baseline

gamma_weights = array.new_float(length, 0.0)
price_series = array.new_float(length, na)

// Populate Arrays for Calculation
if bar_index >= length
    for i = 0 to length - 1
        weighted_gamma = math.pow(gamma_factor, i)
        array.set(gamma_weights, i, weighted_gamma)
        array.set(price_series, i, close[i])

// Compute GWAP
weighted_sum = 0.0
weight_total = 0.0
for i = 0 to length - 1
    w = array.get(gamma_weights, i)
    p = array.get(price_series, i)
    weighted_sum := weighted_sum + p * w
    weight_total := weight_total + w

GWAP = weight_total != 0 ? weighted_sum / weight_total : na

plot(GWAP, color=color.red, title="Gamma Weighted Average Price")

// Conditions for Trade Signals
long_condition = close > GWAP and close[1] > close[2] and close[2] > close[3]
short_condition = close < GWAP and close[1] < close[2] and close[2] < close[3]

// Strategy Logic
if long_condition
    strategy.entry("Long", strategy.long)

if short_condition
    strategy.entry("Short", strategy.short)
Published by ChaoZhang on the FMZ strategy square · last modified 2025-02-18. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Gamma-Weighted-Momentum-Based-Bitcoin-Futures-Intelligent-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX Momentum Trend StrategyPine Script · Momentum · 10m
- Adaptive Trend Following Strategy Based on Momentum OscillatorPine Script · Momentum · 1d
- Advanced Composite Moving Average and Market Momentum Trend Capture StrategyPine Script · Momentum
- Advanced Multi Indicator Trend Following and Momentum Quantitative Trading StrategyPine Script · Momentum · 1h
- Bollinger Bands Momentum Trend Following Quantitative StrategyPine Script · Momentum · 1d
- Confirmed SMA Crossover Momentum StrategyPine Script · Momentum · 1d