Gem Forest 1 Minute Breakout Strategy
The Gem Forest 1 Minute Breakout Strategy is a quantitative trading strategy that aims to capture breakout signals within a 1-minute timeframe to realize quick profits. This strategy incorporates multiple indicators…
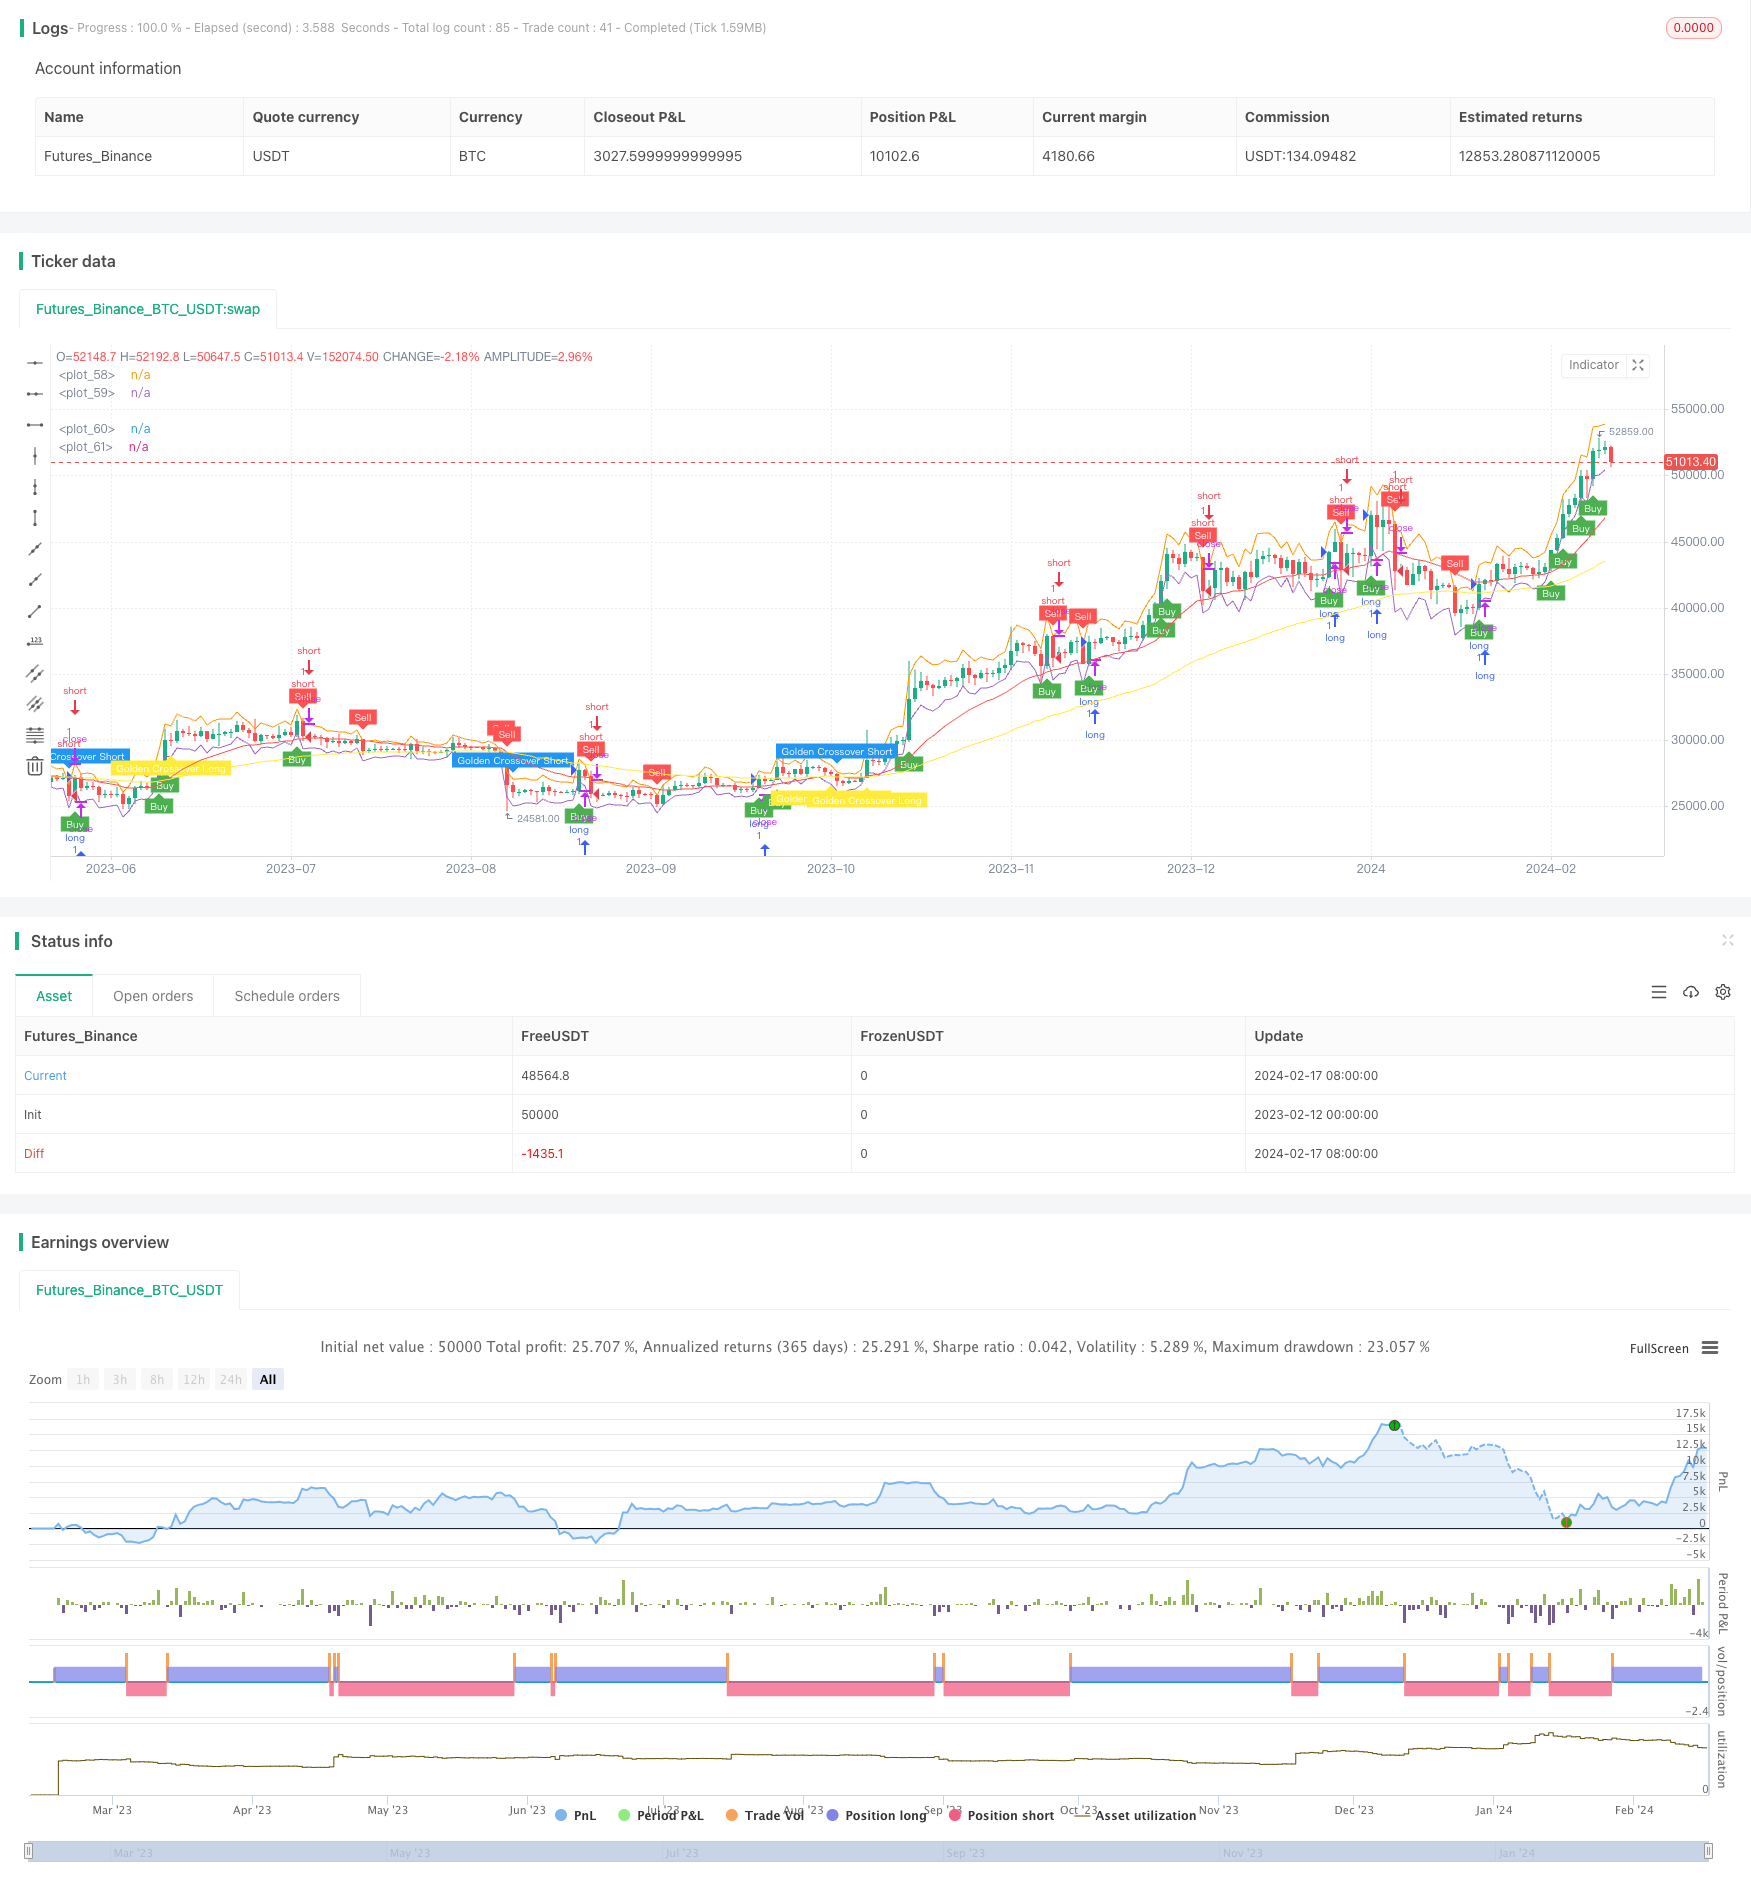
Overview
The Gem Forest 1 Minute Breakout Strategy is a quantitative trading strategy that aims to capture breakout signals within a 1-minute timeframe to realize quick profits. This strategy incorporates multiple indicators like moving averages, ATR, RSI to generate trading signals and achieve higher risk-reward ratios over short holding periods.
Strategy Logic
This strategy mainly uses the following elements to form trade signals:
- ATR Indicator - Calculates average true range to set price channels;
- Moving Average Indicators - Compute fast EMA and slow EMA to generate golden cross/dead cross signals;
- RSI Indicator - Calculate fast and slow RSI to determine overbought/oversold area;
- Price-Channel Relationship - Generates trade signals when price breaks out of the channels.
Specifically, the strategy computes N-period average of ATR, fast EMA, slow EMA, fast RSI and slow RSI. Combining the conditions of price breaking ATR channel, EMA golden cross, and RSI reaching extreme levels, the strategy sends out buy or sell signals.
Advantage Analysis
The main advantages of this strategy are:
- Captures short-term price trends;
- Responds swiftly, suitable for high frequency trading;
- More reliable with multiple filtered indicators;
- Parametric for users to optimize.
Risk Analysis
There are also some risks:
- High risks in short-term trading, strict stop loss needed;
- Improper parameter optimization leads to overfitting;
- High trading frequency increases costs.
To control risks, stop loss should be implemented, and parameters need proper backtests to avoid overfitting. Moreover, adjusting trade frequency to control costs.
Optimization Directions
The strategy can be optimized through:
Test parameters settings over shorter periods (5-min, 15-min);
Add more filtering indicators like volume to improve signal quality;
Optimize ATR channel and moving average parameters to find best parameter combinations.
Conclusion
The Gem Forest 1 Minute Breakout Strategy focuses on capturing short-term trends by filtering with multiple indicators, featuring fast response and high risk-reward characteristics. It can be adapted to users' risk preferences through parameter optimization for better results. However, users should control trading risks via strict stop loss, reasonable trade frequencies etc. Overall, this strategy suits investors with certain quant trading knowledge and risk tolerance for short-term trading.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_int_1 | 14 | ATR Period |
| v_input_float_1 | true | ATR Multi |
| v_input_string_1 | 0 | ATR Smoothing: WMA | SMA | EMA | RMA |
| v_input_int_2 | 21 | Fast EMA |
| v_input_int_3 | 65 | Slow EMA |
| v_input_int_4 | 25 | Fast RSI Length |
| v_input_int_5 | 100 | Slow RSI Length |
Source Pine Script
/*backtest
start: 2023-02-12 00:00:00
end: 2024-02-18 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Gem Forest 1 Dakika Scalp", overlay=true)

source = close
atrlen = input.int(14, "ATR Period")
mult = input.float(1, "ATR Multi", step=0.1)
smoothing = input.string(title="ATR Smoothing", defval="WMA", options=["RMA", "SMA", "EMA", "WMA"])

ma_function(source, atrlen) =>
    if smoothing == "RMA"
        ta.rma(source, atrlen)
    else
        if smoothing == "SMA"
            ta.sma(source, atrlen)
        else
            if smoothing == "EMA"
                ta.ema(source, atrlen)
            else
                ta.wma(source, atrlen)

atr_slen = ma_function(ta.tr(true), atrlen)
upper_band = atr_slen * mult + close
lower_band = close - atr_slen * mult

ShortEMAlen = input.int(21, "Fast EMA")
LongEMAlen = input.int(65, "Slow EMA")
shortSMA = ta.ema(close, ShortEMAlen)
longSMA = ta.ema(close, LongEMAlen)
RSILen1 = input.int(25, "Fast RSI Length")
RSILen2 = input.int(100, "Slow RSI Length")
rsi1 = ta.rsi(close, RSILen1)
rsi2 = ta.rsi(close, RSILen2)
atr = ta.atr(atrlen)

RSILong = rsi1 > rsi2
RSIShort = rsi1 < rsi2

longCondition = open < lower_band
shortCondition = open > upper_band
GoldenLong = ta.crossover(shortSMA,longSMA)
Goldenshort = ta.crossover(longSMA,shortSMA)

plotshape(shortCondition, title="Sell Label", text="Sell", location=location.abovebar, style=shape.labeldown, size=size.tiny, color=color.new(color.red, 0), textcolor=color.white)
plotshape(longCondition, title="Buy Label", text="Buy", location=location.belowbar, style=shape.labelup, size=size.tiny, color=color.new(color.green, 0), textcolor=color.white)
plotshape(Goldenshort, title="Golden Sell Label", text="Golden Crossover Short", location=location.abovebar, style=shape.labeldown, size=size.tiny, color=color.new(color.blue, 0), textcolor=color.white)
plotshape(GoldenLong, title="Golden Buy Label", text="Golden Crossover Long", location=location.belowbar, style=shape.labelup, size=size.tiny, color=color.new(color.yellow, 0), textcolor=color.white)

if (longCondition)
    stopLoss = low - atr * 2
    takeProfit = high + atr * 5
    strategy.entry("long", strategy.long)

if (shortCondition)
    stopLoss = high + atr * 2
    takeProfit = low - atr * 5
    strategy.entry("short", strategy.short)

plot(upper_band)
plot(lower_band)
plot(shortSMA, color = color.red)
plot(longSMA, color = color.yellow)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-19. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Gem-Forest-1-Minute-Breakout-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Dual MA Momentum Breakout StrategyPine Script · Breakout · 1h
- EMA and Bollinger Bands Breakout StrategyPine Script · Breakout · 1h
- Momentum Breakout Moving Average StrategyPine Script · Breakout · 1d
- Momentum Breakout Trading Strategy 440964Pine Script · Breakout · 5m
- Moving Average Crossover and Upper Rail Breakthrough Impulse StrategyPine Script · Breakout · 1m
- Multi Filter Trend Breakthrough Smart Moving Average Trading StrategyPine Script · Breakout · 1h