Linear Regression and Dual Moving Average Short Term Strategy
This strategy combines linear regression indicators and dual exponential moving averages to implement short-term tracking operations. The strategy establishes short positions when prices break through the upper and…
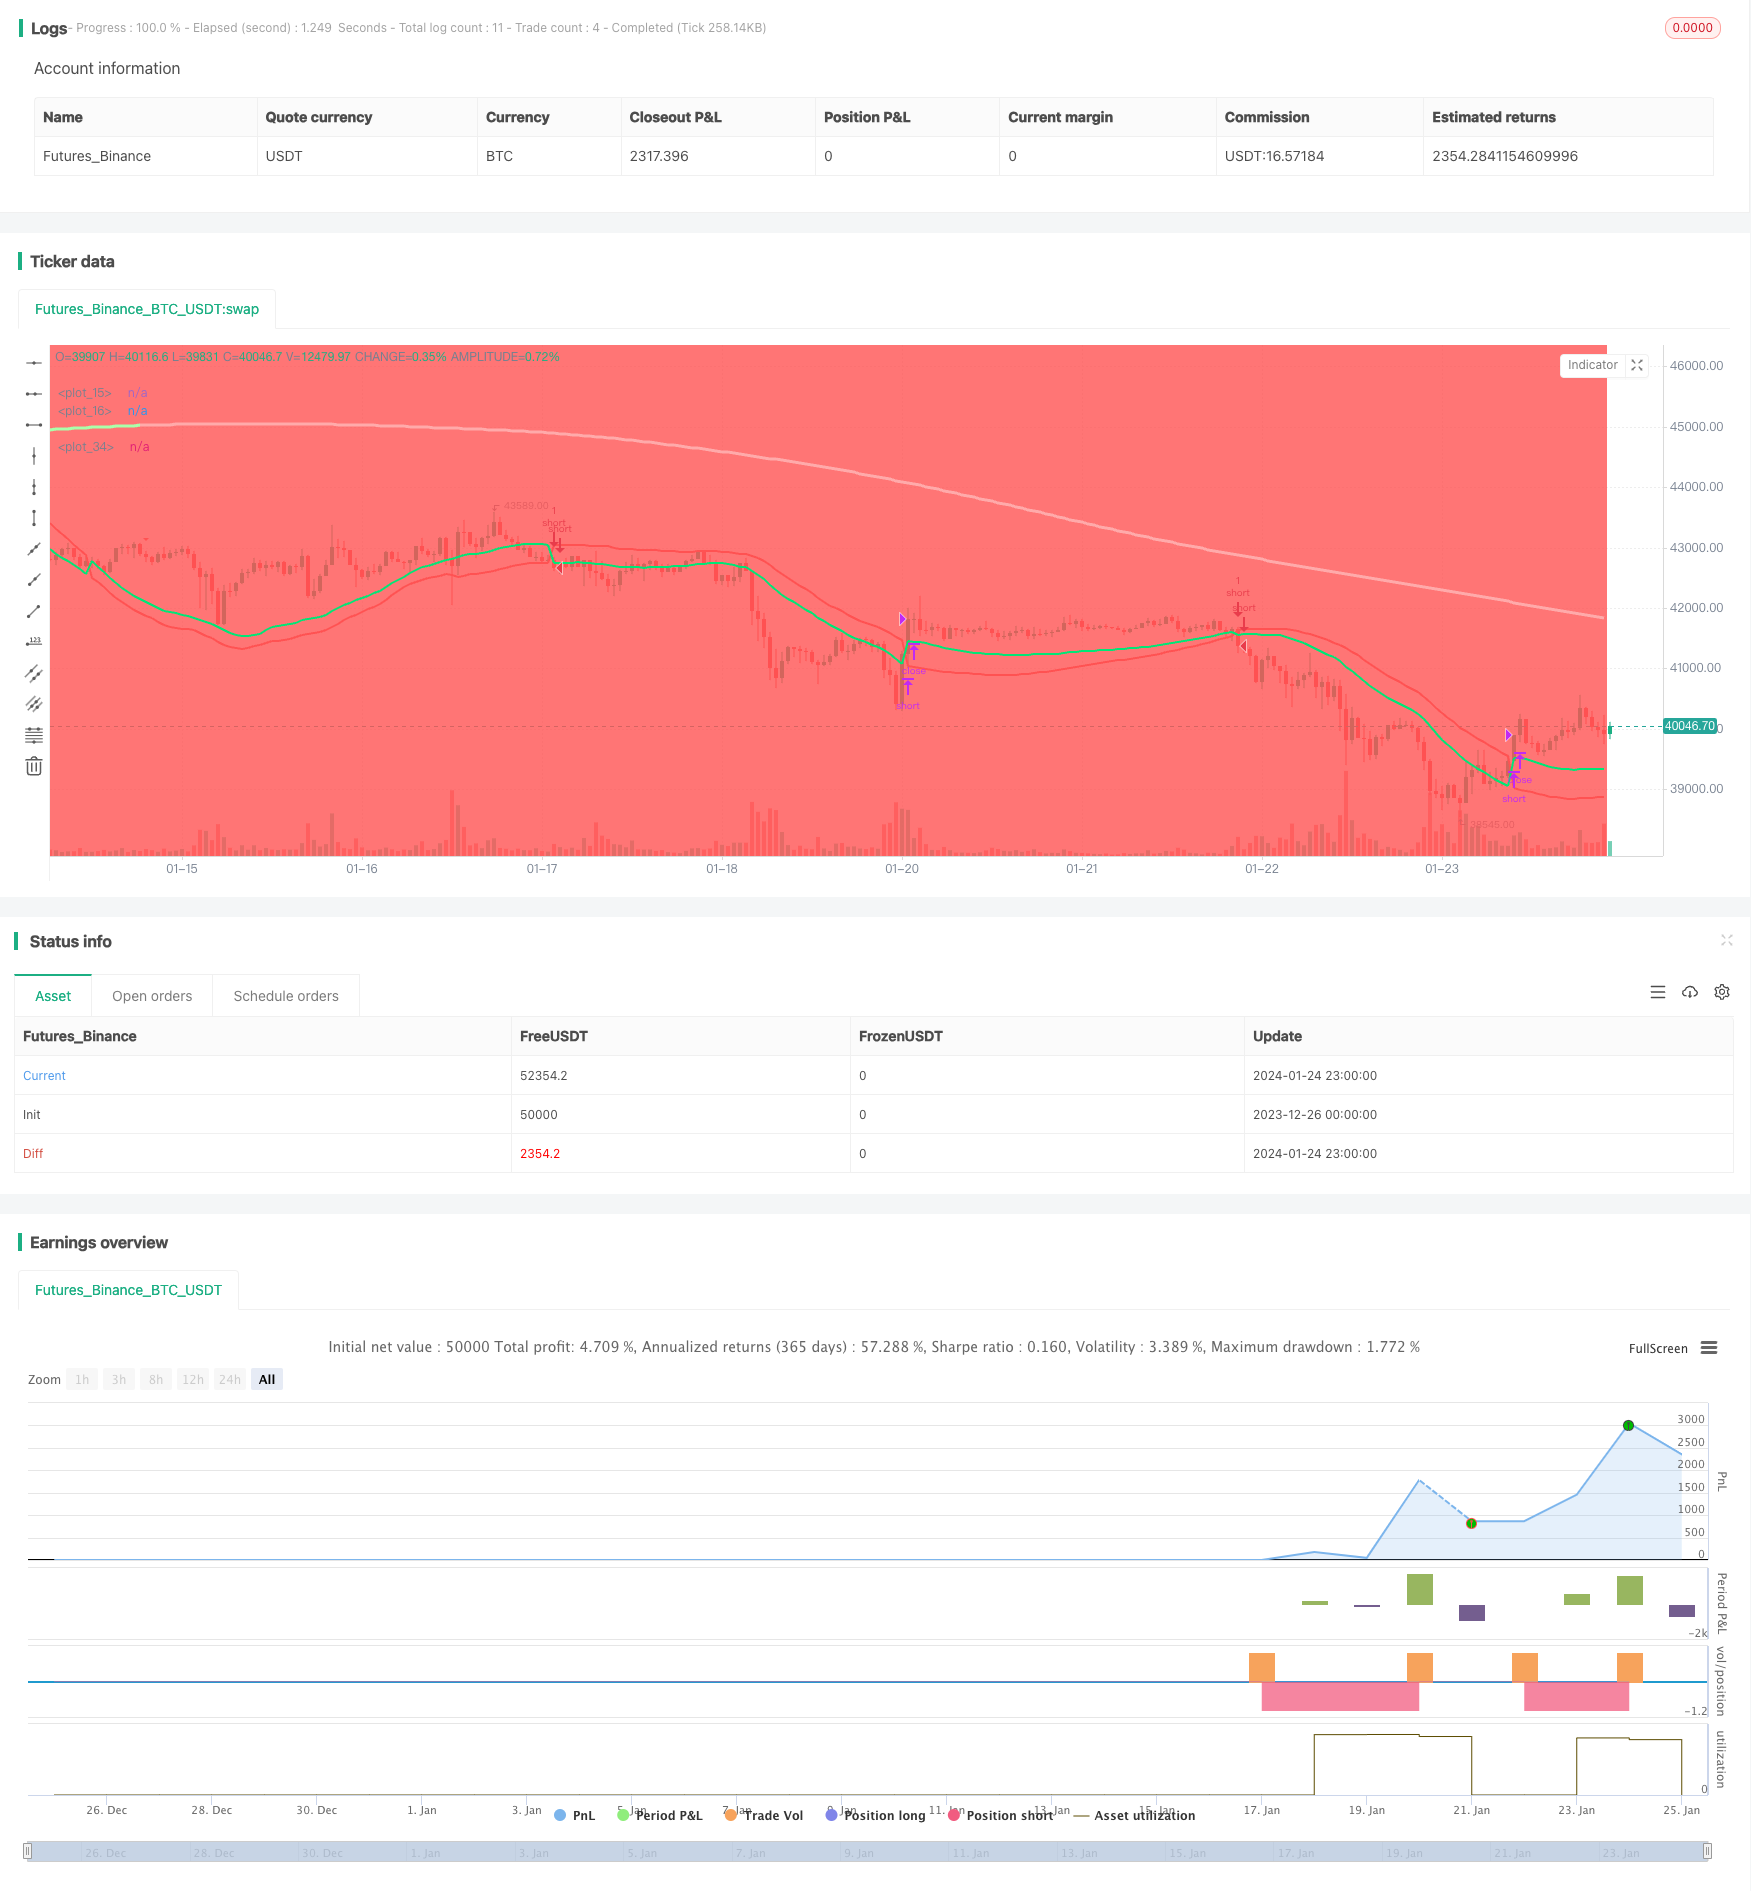
Overview
This strategy combines linear regression indicators and dual exponential moving averages to implement short-term tracking operations. The strategy establishes short positions when prices break through the upper and lower rails, and closes positions when prices break through again. At the same time, this strategy also uses dual exponential moving averages to determine price trends as an auxiliary condition for establishing positions.
Strategy Principle
This strategy mainly uses linear regression indicators to determine price breakouts. The linear regression indicator is calculated based on the highest and lowest prices over a certain period using linear regression to obtain upper and lower rails. When prices break down from the upper rail or break up from the lower rail, we believe it is a trading signal.
In addition, this strategy also introduces dual exponential moving averages to determine the interim trend. Dual exponential moving averages can respond faster to price changes. When prices break down from the upper rail, if the dual exponential moving average is already above the price at this time, it indicates that it is currently in a downward trend. We will establish short positions. When prices break through the upper rail again or break through the dual exponential moving average, we will flatten positions.
Specifically, the main points of the strategy include:
- Calculate linear regression upper and lower rails
- Calculate dual exponential moving average
- When the price breaks down from the upper rail and the dual exponential moving average is above the price, establish short positions
- When prices break through the upper rail again or are above the dual exponential moving average, flatten short positions
Advantage Analysis
Compared with traditional moving average and other indicators, this strategy has the following advantages:
- Linear regression indicators can capture price changes faster and are more effective as entry signals
- Dual exponential moving averages determine trends more sensitively and can avoid false breakouts
- Combining dual indicators and conditions can filter out some noise and make trading more stable
Risk Analysis
This strategy also has some risks to note:
- Linear regression indicators are sensitive to parameters and different cycles may produce different results
- Dual exponential moving averages may deviate and judge wrongly
- Breakthrough strategies may increase slippage risks
- Frequent opening and closing of positions may occur in volatile markets
For the above risks, we can solve them by parameter optimization, strict stop loss, appropriately relaxing the breakthrough amplitude, etc.
Optimization Directions
This strategy can also be optimized in the following aspects:
- Optimize linear regression cycle and dual exponential moving average cycle to find the best parameter combination
- Add price volatility judgment to avoid errors caused by slight price breakthroughs
- Increase auxiliary conditions such as trading volume to ensure the effectiveness of breakthroughs
- Set stop loss levels to reduce single loss
- Adjust parameters for specific varieties
Summary
This strategy comprehensively uses linear regression indicators and dual exponential moving averages, which has certain advantages in theory and practice. Further improvements in stability and strategy results can be achieved through continuous optimization and adjustment. This strategy is suitable for short-term operations and can bring good alpha to quantitative traders.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 2017 | Start Year |
| v_input_2 | 12 | Month |
| v_input_3 | 17 | Day |
| v_input_4 | 89 | Period |
| v_input_5 | 200 | DEMA |
Source Pine Script
/*backtest
start: 2023-12-26 00:00:00
end: 2024-01-25 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy('LR&SSL_Short', overlay=true)
startP = timestamp(input(2017, "Start Year"), input(12, "Month"), input(17, "Day"), 0, 0)
end   = timestamp(9999,1,1,0,0)
_testPeriod() => true

len = input(title="Period", defval=89)
smaHigh = linreg(high, len, 0)
smaLow = linreg(low, len, -1)
Hlv = 0.0
Hlv := close > smaHigh ? 1 : close < smaLow ? -1 : Hlv[1]
sslDown = Hlv < 0 ? smaHigh : smaLow
sslUp = Hlv < 0 ? smaLow : smaHigh

plot(sslDown, linewidth=2, color=color.red)
plot(sslUp, linewidth=2, color=color.lime)


length = input(200, title="DEMA")
d1 = ema(close, length)
d2 = 2 * d1 - ema(d1, length)
trendColour = d2 > d1 ? #AAFFAA : #FFAAAA
dema=sma(d2,length)

turnGreen = d2 > d1 and d2[1] <= d1[1]
turnRed   = d2 <= d1 and d2[1] > d1[1]

up =turnGreen
down=turnRed

plotshape(down, title="down", style=shape.triangledown,location=location.abovebar, color=color.red, transp=0, size=size.small)
plotshape(up,  title="up", style=shape.triangleup,location=location.belowbar, color=color.green, transp=0, size=size.small)
plot(dema, color = trendColour,linewidth=3 ,transp = 0)
bgcolor(close > dema ? color.green : color.red)

strategy.entry("short", strategy.short, when= crossunder(sslUp, sslDown) and dema > close and _testPeriod())
strategy.close("short", when = crossover(sslUp, sslDown) or crossover(close, dema))
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-26. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Linear-Regression-and-Dual-Moving-Average-Short-Term-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive Multi Period Trading Strategy Based on Wave Trend Momentum BreakoutPine Script · Breakout · 2h
- BB Breakout StrategyPine Script · Breakout · 1d
- BMSB Breakout Strategy BMSBPine Script · Breakout · 1h
- Bollinger Band T3 Moving Average StrategyPine Script · Breakout · 10m
- Bollinger Bands Dual track Breakthrough StrategyPine Script · Breakout · 30m
- Bollinger Breakout StrategyPine Script · Breakout · 30m