Strategy vault / Trend following
MilleMachine
Hello traders, I hereby present to you the second stage of my journey to finding a reliable, profitable trading strategy. The "Millemachine" is based on the "Millebot", my previous published strategy. This means the…
Hello traders,
I hereby present to you the second stage of my journey to finding a reliable, profitable trading strategy. The "Millemachine" is based on the "Millebot", my previous published strategy. This means the backbone of the strategy is still the same: a trend following system. Instead of using a fixed TP and SL, a trailing stoploss is now used. To limit the losses when the trend weakens, the trailing stoploss automatically gets smaller, as it is based on the ATR. A new utility is you can now easily switch between indicators on which the decision making is based. This allows the user to discover which indicators work best for entry, long/short switching and stoploss configuration.
The strategy has been proven to be very profitable in trending markets, but can suffer losses during ranging market. To make the system more robust, the strategy cannot solely rely on a trending system. Other systems must be added. I believe that a good trading bot must consist of more than 4 different strategies, based on different systems. This is what I am currently working on.
My goal for publishing this strategy is to help other traders build their own. In my journey I found it difficult to find a good strategy that employs a decent risk management, which is truly essential for having good, consistent results. Also, a realistic commission needs to be defined to have a realistic performance prediction. This weighs on the profitability and therefore is often set at 0 by authors of other strategies, which I find misleading.
If you have found this strategy informative or useful, please leave a comment.
Greetings Michael
backtest
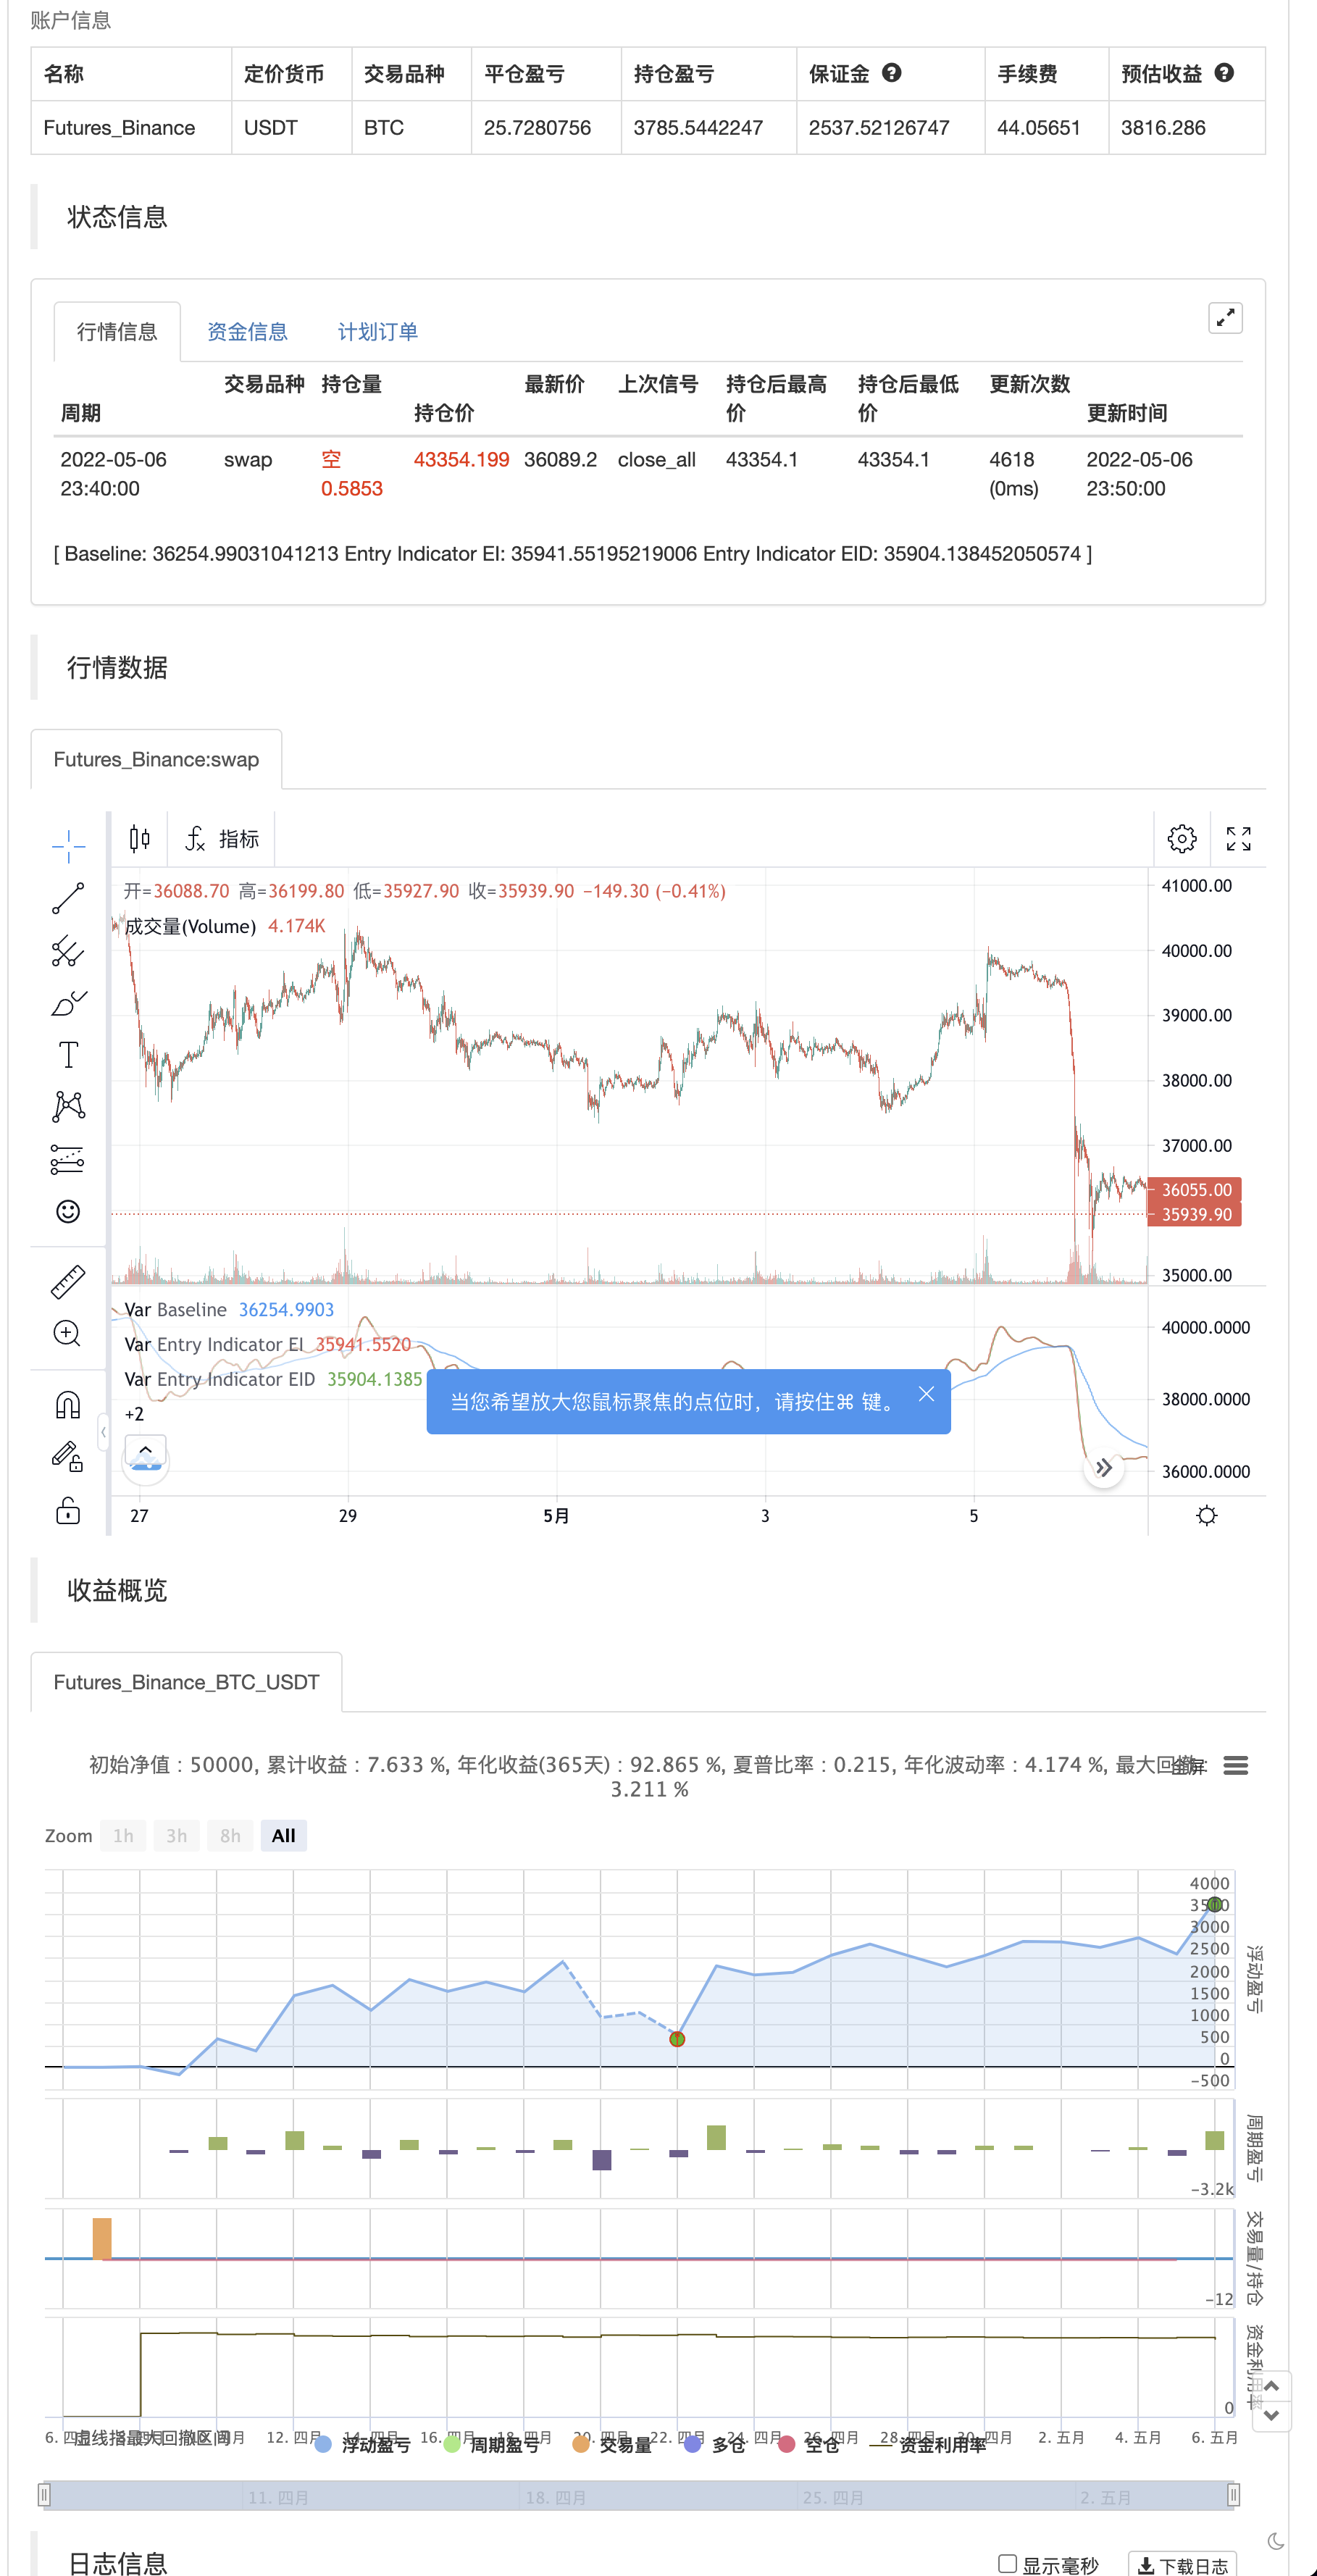
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 0 | Mode: LongShort | OnlyLong | OnlyShort | Indicator Mode |
| v_input_2 | true | % Risk |
| v_input_3 | 2 | ATR Multiplier |
| v_input_4 | true | ====== Activate Baseline - Switch L/S ====== |
| v_input_5 | 0 | Baseline Type: McGinley | HMA | EHMA | THMA | SMA | EMA | DEMA | TEMA | WMA | VWMA | SMMA | RMA | LSMA | ALMA | Kijun | WWSA |
| v_input_6_close | 0 | BL source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_7 | 50 | BL length |
| v_input_8 | false | ===== Activate Confirmation indicator ===== |
| v_input_9 | 0 | C1 Entry indicator: SMA | HMA | EHMA | THMA | McGinley | EMA | DEMA | TEMA | WMA | VWMA | SMMA | RMA | LSMA | ALMA | Kijun | WWSA |
| v_input_10_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_11 | 5 | Length |
| v_input_12 | true | ====== ENTRY indicator ======= |
| v_input_13 | 0 | EI Entry indicator: HMA | McGinley | EHMA | THMA | SMA | EMA | DEMA | TEMA | WMA | VWMA | SMMA | RMA | LSMA | ALMA | Kijun | WWSA |
| v_input_14_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_15 | 46 | Length |
| v_input_16 | true | ===== Activate Trailing Stop ===== |
| v_input_17 | 0 | TS Traling Stop Type: EMA | HMA | EHMA | THMA | SMA | McGinley | DEMA | TEMA | WMA | VWMA | SMMA | RMA | LSMA | ALMA | Kijun | WWSA |
| v_input_18 | 5 | Smoothing Trail Long EMA |
| v_input_19 | 2 | Smoothing Trail Short EMA |
Source Pine Script
// © Milleman
//@version=4
//strategy("MilleMachine", overlay=true, default_qty_type = strategy.percent_of_equity, default_qty_value = 100, initial_capital=10000, commission_type=strategy.commission.percent, commission_value=0.06)


// Additional settings
Mode = input(title="Mode", defval="LongShort", options=["LongShort", "OnlyLong", "OnlyShort","Indicator Mode"])
UseTP = false                               //input(false, title="Use Take Profit?")
QuickSwitch = true                          //input(true, title="Quickswitch")
UseTC = true                                //input(true, title="Use Trendchange?")

// Risk management settings
//Spacer2 = input(false, title="======= Risk management settings =======")
Risk = input(1.0, title="% Risk",minval=0)/100
RRR = 2                                     //input(2,title="Risk Reward Ratio",step=0.1,minval=0,maxval=20)
SL_Mode = false                             // input(true, title="ON = Fixed SL / OFF = Dynamic SL (ATR)")
SL_Fix = 3                                  //input(3,title="StopLoss %",step=0.25, minval=0)/100
ATR = atr(14)                               //input(14,title="Periode ATR"))
Mul = input(2,title="ATR Multiplier",step=0.1)
xATR = ATR * Mul
SL = SL_Mode ? SL_Fix : (1 - close/(close+xATR))

// INDICATORS  //////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////
Ind(type, src, len) =>
    float result = 0
    if type=="McGinley"
        result := na(result[1]) ? ema(src, len) : result[1] + (src - result[1]) / (len * pow(src/result[1], 4))
    if type=="HMA"
        result := wma(2*wma(src, len/2)-wma(src, len), round(sqrt(len)))
    if type=="EHMA"
        result := ema(2*ema(src, len/2)-ema(src, len), round(sqrt(len)))
    if type=="THMA"
        lend = len/2
        result := wma(wma(src, lend/3)*3-wma(src, lend/2)-wma(src,lend), lend)
    if type=="SMA" // Simple
        result := sma(src, len)
    if type=="EMA" // Exponential
        result := ema(src, len)
    if type=="DEMA" // Double Exponential
        e = ema(src, len)
        result := 2 * e - ema(e, len)
    if type=="TEMA" // Triple Exponential
        e = ema(src, len)
        result := 3 * (e - ema(e, len)) + ema(ema(e, len), len)
    if type=="WMA" // Weighted
        result := wma(src, len)
    if type=="VWMA" // Volume Weighted
        result := vwma(src, len)
    if type=="SMMA" // Smoothed
        w = wma(src, len)
        result := (w[1] * (len - 1) + src) / len
    if type == "RMA"
        result := rma(src, len)
    if type=="LSMA" // Least Squares
        result := linreg(src, len, 0)
    if type=="ALMA" // Arnaud Legoux
        result := alma(src, len, 0.85, 6)
    if type=="Kijun" //Kijun-sen
        kijun = avg(lowest(len), highest(len))
        result :=kijun
    if type=="WWSA" // Welles Wilder Smoothed Moving Average
        result := nz(result[1]) + (close -nz(result[1]))/len
    result

// Baseline : Switch from Long to Short and vice versa
BL_Act = input(true, title="====== Activate Baseline - Switch L/S ======")
BL_type = input(title="Baseline Type", defval="McGinley", options=["McGinley","HMA","EHMA","THMA","SMA","EMA","DEMA","TEMA","WMA","VWMA","SMMA","RMA","LSMA","ALMA","Kijun","WWSA"])
BL_src = input(close, title="BL source")
BL_len = input(50, title="BL length", minval=1)
BL = Ind(BL_type,BL_src, BL_len)

// Confirmation indicator
C1_Act = input(false, title="===== Activate Confirmation indicator =====")
C1_type = input(title="C1 Entry indicator", defval="SMA", options=["McGinley","HMA","EHMA","THMA","SMA","EMA","DEMA","TEMA","WMA","VWMA","SMMA","RMA","LSMA","ALMA","Kijun","WWSA"])
C1_src = input(close, title="Source")
C1_len = input(5,title="Length", minval=1)
C1 = Ind(C1_type,C1_src,C1_len)

// Entry indicator : Hull Moving Average
Spacer5 = input(true, title="====== ENTRY indicator =======")
EI_type = input(title="EI Entry indicator", defval="HMA", options=["McGinley","HMA","EHMA","THMA","SMA","EMA","DEMA","TEMA","WMA","VWMA","SMMA","RMA","LSMA","ALMA","Kijun","WWSA"])
EI_src = input(close, title="Source")
EI_Len = input(46,title="Length", minval=1)
EI = Ind(EI_type,EI_src,EI_Len)

// Trail stop settings
TrailActivation = input(true, title="===== Activate Trailing Stop =====")
TS_type = input(title="TS Traling Stop Type", defval="EMA", options=["McGinley","HMA","EHMA","THMA","SMA","EMA","DEMA","TEMA","WMA","VWMA","SMMA","RMA","LSMA","ALMA","Kijun","WWSA"])
TrailSLScaling = 1 //input(100, title="SL Scaling", minval=0, step=5)/100
TrailingSourceLong = Ind(TS_type,low,input(5,"Smoothing Trail Long EMA", minval=1))
TrailingSourceShort = Ind(TS_type,high,input(2,"Smoothing Trail Short EMA", minval=1))

//VARIABLES MANAGEMENT
TriggerPrice = 0.0, TriggerPrice := TriggerPrice[1]
TriggerSL = 0.0, TriggerSL := TriggerSL[1]
SLPrice = 0.0, SLPrice := SLPrice[1], TPPrice = 0.0, TPPrice := TPPrice[1]
isLong = false, isLong := isLong[1], isShort = false, isShort := isShort[1]

//LOGIC
GoLong = crossover(EI,EI[1]) and (strategy.position_size == 0.0 and QuickSwitch) and (not BL_Act or BL/BL[1] > 1) and (not C1_Act or C1>C1[1]) and (Mode == "LongShort" or Mode == "OnlyLong")
GoShort = crossunder(EI,EI[1]) and (strategy.position_size == 0.0 and QuickSwitch) and (not BL_Act or BL/BL[1] < 1) and (not C1_Act or C1<C1[1]) and (Mode == "LongShort" or Mode == "OnlyShort")
ExitLong = isLong and crossunder(EI,EI[1]) and UseTC
ExitShort = isShort and crossover(EI,EI[1]) and UseTC

//FRAMEWORK
//Reset Long-Short memory
if isLong and strategy.position_size == 0.0
    isLong := false
if isShort and strategy.position_size == 0.0
    isShort := false
//Long
if GoLong
    isLong := true, TriggerPrice := close, TriggerSL := SL
    TPPrice := UseTP? TriggerPrice * (1 + (TriggerSL * RRR)) : na
    SLPrice := TriggerPrice * (1-TriggerSL)
    Entry_Contracts = strategy.equity * Risk / ((TriggerPrice-SLPrice)/TriggerPrice) / TriggerPrice
    strategy.entry("Long", strategy.long, comment=str.tostring(math.round((TriggerSL/TriggerPrice)*1000)), qty=Entry_Contracts)
    strategy.exit("TPSL","Long", limit=TPPrice, stop=SLPrice)
if isLong
    NewValSL = TrailingSourceLong * (1 - (SL*TrailSLScaling))
    if TrailActivation and NewValSL > SLPrice
        SLPrice := NewValSL
    strategy.exit("TPSL","Long", limit=TPPrice, stop=SLPrice)
if ExitLong
    strategy.close_all(comment="TrendChange")
    isLong := false

//Short
if GoShort
    isShort := true, TriggerPrice := close, TriggerSL := SL
    TPPrice := UseTP? TriggerPrice * (1 - (TriggerSL * RRR)) : na
    SLPrice := TriggerPrice * (1 + TriggerSL)
    Entry_Contracts = strategy.equity * Risk / ((SLPrice-TriggerPrice)/TriggerPrice) / TriggerPrice
    strategy.entry("Short", strategy.short, comment=str.tostring(math.round((TriggerSL/TriggerPrice)*1000)), qty=Entry_Contracts)
    strategy.exit("TPSL","Short", limit=TPPrice, stop=SLPrice)
if isShort
    NewValSL = TrailingSourceShort * (1 + (SL*TrailSLScaling))
    if TrailActivation and NewValSL < SLPrice
        SLPrice := NewValSL
    strategy.exit("TPSL","Short", limit=TPPrice, stop=SLPrice)
if ExitShort
    strategy.close_all(comment="TrendChange")
    isShort := false

//VISUALISATION
plot(BL_Act?BL:na, color=color.blue,title="Baseline")
plot(C1_Act?C1:na, color=color.yellow,title="confirmation Indicator")
EIColor = EI>EI[1] ? color.green : color.red
Fill_EI = plot(EI, color=EIColor, linewidth=1, transp=40, title="Entry Indicator EI")
Fill_EID = plot(EI[1], color=EIColor, linewidth=1, transp=40, title="Entry Indicator EID")


plot(strategy.position_size != 0.0 and (isLong or isShort) ? TriggerPrice : na, title="TriggerPrice", color=color.yellow, style=plot.style_linebr)
plot(strategy.position_size != 0.0 and (isLong or isShort) ? TPPrice : na, title="TakeProfit", color=color.green, style=plot.style_linebr)
plot(strategy.position_size != 0.0 and (isLong or isShort) ? SLPrice : na, title="StopLoss", color=color.red, style=plot.style_linebr)
Published by ChaoZhang on the FMZ strategy square · last modified 2022-05-08. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/MilleMachine.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dual MA Crossover Trend Tracking StrategyPine Script · Trend following · 1h
- Dual Mode Adaptive Trend Trading Strategy EMA Crossover with ATR Volatility Based Risk Management SystemPine Script · Trend following · 1d
- Dual Moving Average Crossover Dynamic Position Optimization Strategy with EMA Cross Signal SystemPine Script · Trend following · 1h