Momentum Combined with Trend Judgment Multi factor Quantitative Trading Strategy
This strategy is a multi-factor judged quantitative trading strategy that combines momentum indicators and trend indicators. The strategy judges the overall trend and momentum direction of the market by calculating…
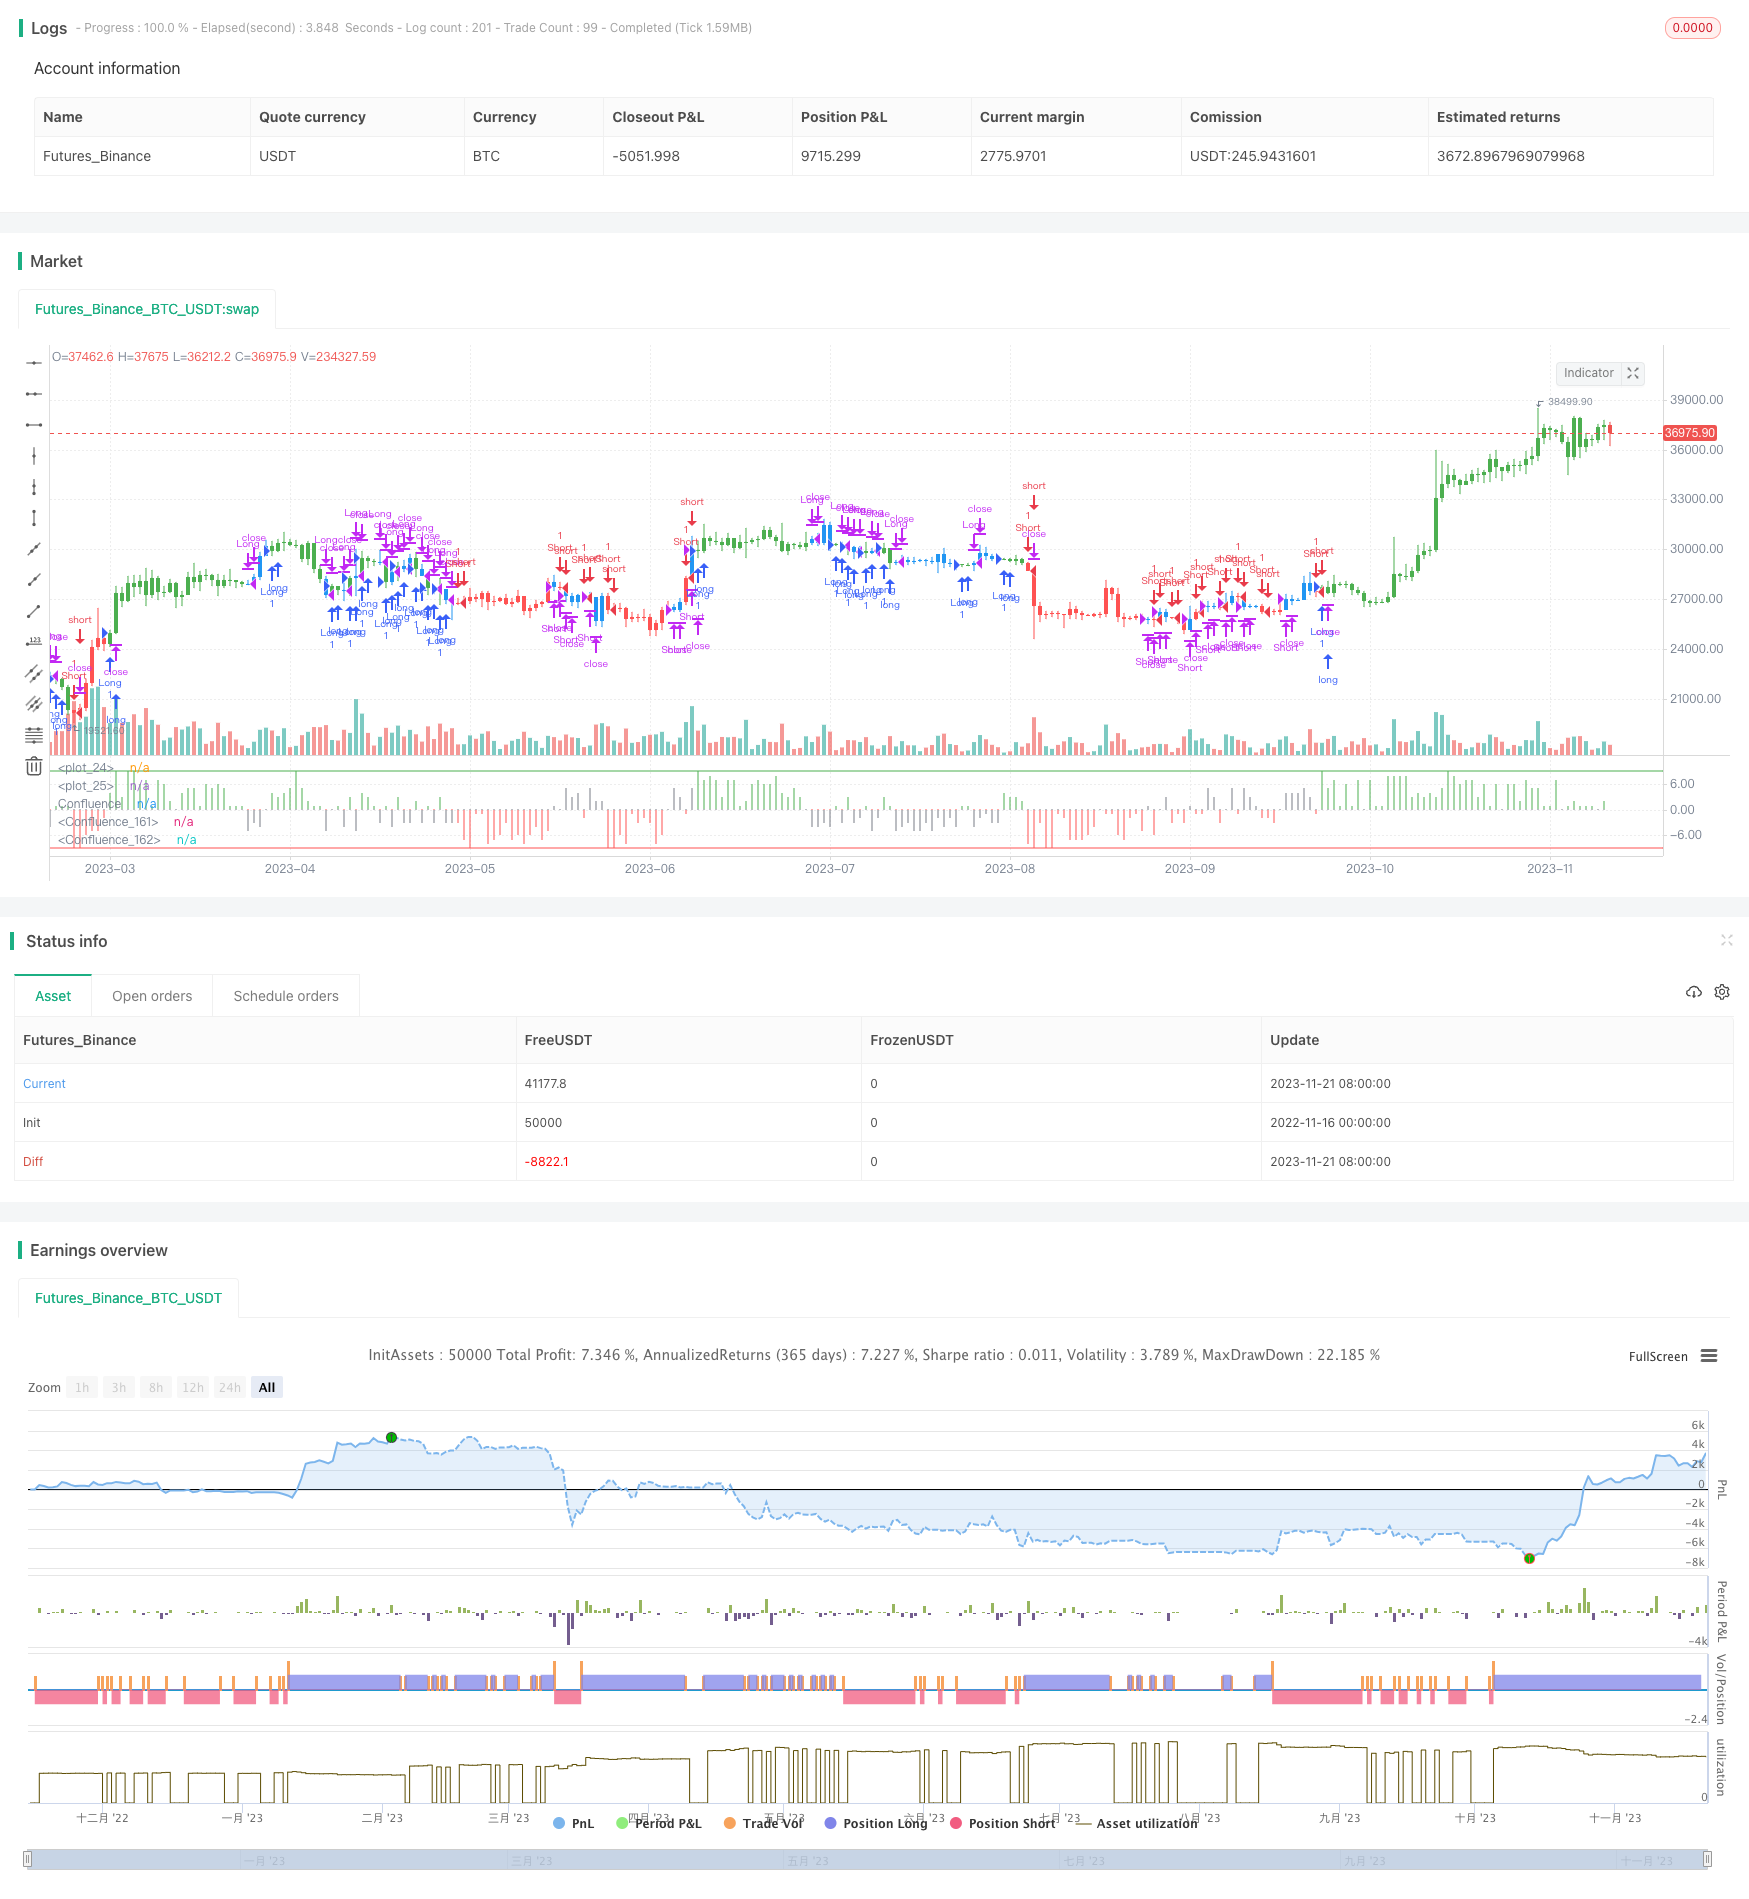
Overview
This strategy is a multi-factor judged quantitative trading strategy that combines momentum indicators and trend indicators. The strategy judges the overall trend and momentum direction of the market by calculating mathematical combinations of multiple moving averages, and generates trading signals based on threshold conditions.
Strategy Principle
- Calculate multiple moving averages and momentum indicators
- Calculate Harmonics moving average, short-term moving average, medium-term moving average, long-term moving average and other multiple moving averages
- Calculate the difference between each moving average to reflect the trend of price changes
- Calculate the first order derivative of each moving average to reflect the momentum of price changes
- Calculate the sine and cosine indicators to determine the trend direction
- Comprehensively judge trading signals
- Weighted calculation of momentum indicators, trend indicators and other multi-factors
- Judge the current market state according to the distance between the result value and the threshold
- Issue long and short trading signals
Advantage Analysis
- Multi-factor judgment improves signal accuracy
- Comprehensively consider price, trend, momentum and other factors
- Different factors can be configured with different weights
- Adjustable parameters, adaptable to different markets
- Parameters of moving averages, boundary of trading range can be customized
- Can adapt to different cycles and market environments
- Clear code structure, easy to understand
- Naming specifications, complete comments
- Easy to secondary development and optimization
Risk Analysis
- Difficulty in parameter optimization is high
- Requires a lot of historical data backtesting to find the optimal parameters
- Trading frequency may be too high
- Multi-factor combination judgment may result in too many transactions
- High correlation with market
- Trend judgment strategies are prone to irrational behavior
Optimization Directions
- Add stop loss logic
- Avoid major losses caused by irrational behaviors
- Optimize parameter settings
- Find optimal parameter combinations to improve strategy stability
- Increase machine learning elements
- Use deep learning to judge current market state and assist strategy decisions
Summary
This strategy judges the market state through the multi-factor combination of momentum indicators and trend indicators, and issues trading signals based on set thresholds. The advantages of the strategy are strong configurability, adaptability to different market environments, and easy understanding; the disadvantages are the difficulty in parameter optimization, possibly too high trading frequency, and high correlation with the market. Future optimizations can be made by adding stop loss, parameter optimization and machine learning.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 10 | Harmonic |
| v_input_2 | 9 | BuyBand |
| v_input_3 | -9 | SellBand |
| v_input_4 | false | Trade reverse |
Source Pine Script
/*backtest
start: 2022-11-16 00:00:00
end: 2023-11-22 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=2
////////////////////////////////////////////////////////////
//  Copyright by HPotter v1.0 14/03/2017
// This is modified version of Dale Legan's "Confluence" indicator written by Gary Fritz.
// ================================================================
// Here is Gary`s commentary:
// Since the Confluence indicator returned several "states" (bull, bear, grey, and zero),
// he modified the return value a bit:
// -9 to -1 = Bearish
// -0.9 to 0.9 = "grey" (and zero)
// 1 to 9 = Bullish
// The "grey" range corresponds to the "grey" values plotted by Dale's indicator, but
// they're divided by 10.
//
// You can change long to short in the Input Settings
// Please, use it only for learning or paper trading. Do not for real trading.
////////////////////////////////////////////////////////////

strategy(title="Confluence", shorttitle="Confluence")
Harmonic = input(10, minval=1)
BuyBand = input(9)
SellBand = input(-9)
reverse = input(false, title="Trade reverse")
hline(SellBand, color=red, linestyle=line)
hline(BuyBand, color=green, linestyle=line)

Price = close

STL = round((Harmonic * 2) - 1 - 0.5)
ITL = round((STL * 2) - 1 - 0.5)
LTL = round((ITL * 2) - 1 - 0.5)
HOFF = round(Harmonic / 2 - 0.5)
SOFF = round(STL / 2 - 0.5)
IOFF = round(ITL / 2 - 0.5)

xHavg = sma(Price, Harmonic)
xSavg = sma(Price, STL)
xIavg = sma(Price, ITL)
xLavg = sma(Price, LTL)

xvalue2 = xSavg - xHavg[HOFF]
xvalue3 = xIavg - xSavg[SOFF]
xvalue12 = xLavg - xIavg[IOFF]

xmomsig = xvalue2 + xvalue3 + xvalue12

xLavgOHLC = sma(ohlc4, LTL - 1)

xH2 = sma(Price, Harmonic - 1)
xS2 = sma(Price, STL - 1)
xI2 = sma(Price, ITL - 1)
xL2 = sma(Price, LTL - 1)

DerivH = (xHavg * 2) - xHavg[1]
DerivS = (xSavg * 2) - xSavg[1]
DerivI = (xIavg * 2) - xIavg[1]
DerivL = (xLavg * 2) - xLavg[1]
SumDH = Harmonic * DerivH
SumDS = STL * DerivS
SumDI = ITL * DerivI
SumDL = LTL * DerivL

LengH = Harmonic - 1
LengS = STL - 1
LengI = ITL - 1
LengL = LTL - 1

N1H = xH2 * LengH
N1S = xS2 * LengS
N1I = xI2 * LengI
N1L = xL2 * LengL

DRH = SumDH - N1H
DRS = SumDS - N1S
DRI = SumDI - N1I
DRL = SumDL - N1L

SumH = xH2 * (Harmonic - 1)
SumS = xS2 * (STL - 1)
SumI = xI2 * (ITL - 1)
SumL = xLavgOHLC * (LTL - 1)

xvalue5 = (SumH + DRH) / Harmonic
xvalue6 = (SumS + DRS) / STL
xvalue7 = (SumI + DRI) / ITL
xvalue13 = (SumL + DRL) / LTL

value9 = xvalue6 - xvalue5[HOFF]
value10 = xvalue7 - xvalue6[SOFF]
value14 = xvalue13 - xvalue7[IOFF]
xmom = value9 + value10 + value14

HT = sin(xvalue5 * 2 * 3.14 / 360) + cos(xvalue5 * 2 * 3.14 / 360)
HTA = sin(xHavg * 2 * 3.14 / 360) + cos(xHavg * 2 * 3.14 / 360)
ST = sin(xvalue6 * 2 * 3.14 / 360) + cos(xvalue6 * 2 * 3.14 / 360)
STA = sin(xSavg * 2 * 3.14 / 360) + cos(xSavg * 2 * 3.14 / 360)
IT = sin(xvalue7 * 2 * 3.14 / 360) + cos(xvalue7 * 2 * 3.14 / 360)
ITA = sin(xIavg * 2 * 3.14 / 360) + cos(xIavg * 2 * 3.14 / 360)

xSum = HT + ST + IT
xErr = HTA + STA + ITA

Condition2 = (((xSum > xSum[SOFF]) and (xHavg < xHavg[SOFF])) or ((xSum < xSum[SOFF]) and (xHavg > xHavg[SOFF])))
Phase = iff(Condition2 , -1 , 1)
xErrSum = (xSum - xErr) * Phase
xErrSig = sma(xErrSum, SOFF)

xvalue70 = xvalue5 - xvalue13
xvalue71 = sma(xvalue70, Harmonic)


ErrNum = iff (xErrSum > 0 and xErrSum < xErrSum[1] and xErrSum < xErrSig, 1,
          iff (xErrSum > 0 and xErrSum < xErrSum[1] and xErrSum > xErrSig, 2,
           iff (xErrSum > 0 and xErrSum > xErrSum[1] and xErrSum < xErrSig, 2,
             iff (xErrSum > 0 and xErrSum > xErrSum[1] and xErrSum > xErrSig, 3,
              iff (xErrSum < 0 and xErrSum > xErrSum[1] and xErrSum > xErrSig, -1,
               iff (xErrSum < 0 and xErrSum < xErrSum[1] and xErrSum > xErrSig, -2,
                 iff (xErrSum < 0 and xErrSum > xErrSum[1] and xErrSum < xErrSig, -2,
                  iff (xErrSum < 0 and xErrSum < xErrSum[1] and xErrSum < xErrSig, -3, 0))))))))


momNum = iff (xmom > 0 and xmom < xmom[1] and xmom < xmomsig , 1,
          iff (xmom > 0 and xmom < xmom[1] and xmom > xmomsig, 2,
           iff (xmom > 0 and xmom > xmom[1] and xmom < xmomsig, 2,
             iff (xmom > 0 and xmom > xmom[1] and xmom > xmomsig, 3,
              iff (xmom < 0 and xmom > xmom[1] and xmom > xmomsig, -1,
               iff (xmom < 0 and xmom < xmom[1] and xmom > xmomsig, -2,
                 iff (xmom < 0 and xmom > xmom[1] and xmom < xmomsig, -2,
                  iff (xmom < 0 and xmom < xmom[1] and xmom < xmomsig, -3, 0))))))))

TCNum =  iff (xvalue70 > 0 and xvalue70 < xvalue70[1] and xvalue70 < xvalue71, 1,
          iff (xvalue70 > 0 and xvalue70 < xvalue70[1] and xvalue70 > xvalue71, 2,
           iff (xvalue70 > 0 and xvalue70 > xvalue70[1] and xvalue70 < xvalue71, 2,
             iff (xvalue70 > 0 and xvalue70 > xvalue70[1] and xvalue70 > xvalue71, 3,
              iff (xvalue70 < 0 and xvalue70 > xvalue70[1] and xvalue70 > xvalue71, -1,
               iff (xvalue70 < 0 and xvalue70 < xvalue70[1] and xvalue70 > xvalue71, -2,
                 iff (xvalue70 < 0 and xvalue70 > xvalue70[1] and xvalue70 < xvalue71, -2,
                  iff (xvalue70 < 0 and xvalue70 < xvalue70[1] and xvalue70 < xvalue71, -3,0))))))))

value42 = ErrNum + momNum + TCNum
Confluence = iff (value42 > 0 and xvalue70 > 0, value42,
              iff (value42 < 0 and xvalue70 < 0, value42,
               iff ((value42 > 0 and xvalue70 < 0) or (value42 < 0 and xvalue70 > 0), value42 / 10, 0)))
Res1 = iff (Confluence >= 1, Confluence, 0)
Res2 = iff (Confluence <= -1, Confluence, 0)
Res3 = iff (Confluence == 0, 0, iff (Confluence > -1 and Confluence < 1, 10 * Confluence, 0))
pos = iff(Res2 >= SellBand and Res2 != 0, -1,
	     iff(Res1 <= BuyBand and Res1 != 0, 1,
	       iff(Res3 != 0, 0, nz(pos[1], 0))))
possig = iff(reverse and pos == 1, -1,
          iff(reverse and pos == -1, 1, pos))
if (possig == 1)
    strategy.entry("Long", strategy.long)
if (possig == -1)
    strategy.entry("Short", strategy.short)
if (possig == 0)
    strategy.close("Long", when = possig == 0)
    strategy.close("Short", when = possig == 0)
barcolor(possig == -1 ? red: possig == 1 ? green : blue )
plot(Res1, color=green, title="Confluence", linewidth=3, style = histogram)
plot(Res2, color=red, title="Confluence", linewidth=3, style = histogram)
plot(Res3, color=gray, title="Confluence",  linewidth=3, style = histogram)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-23. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Momentum-Combined-with-Trend-Judgment-Multi-factor-Quantitative-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX Momentum Trend StrategyPine Script · Momentum · 10m
- Adaptive Trend Following Strategy Based on Momentum OscillatorPine Script · Momentum · 1d
- Bollinger Bands Momentum Trend Following Quantitative StrategyPine Script · Momentum · 1d
- Confirmed SMA Crossover Momentum StrategyPine Script · Momentum · 1d
- Cross Momentum Trend Following Strategy SMA RSI Cross Momentum SystemPine Script · Momentum · 1h
- Dual Moving Average Momentum Trading Strategy Time Optimized Trend Following SystemPine Script · Momentum · 2m