Momentum Tracking Strategy 431672
This strategy is based on momentum indicators combined with moving averages to track market trends. It goes long when there is strong upside momentum and goes short when there is strong downside momentum. It belongs…
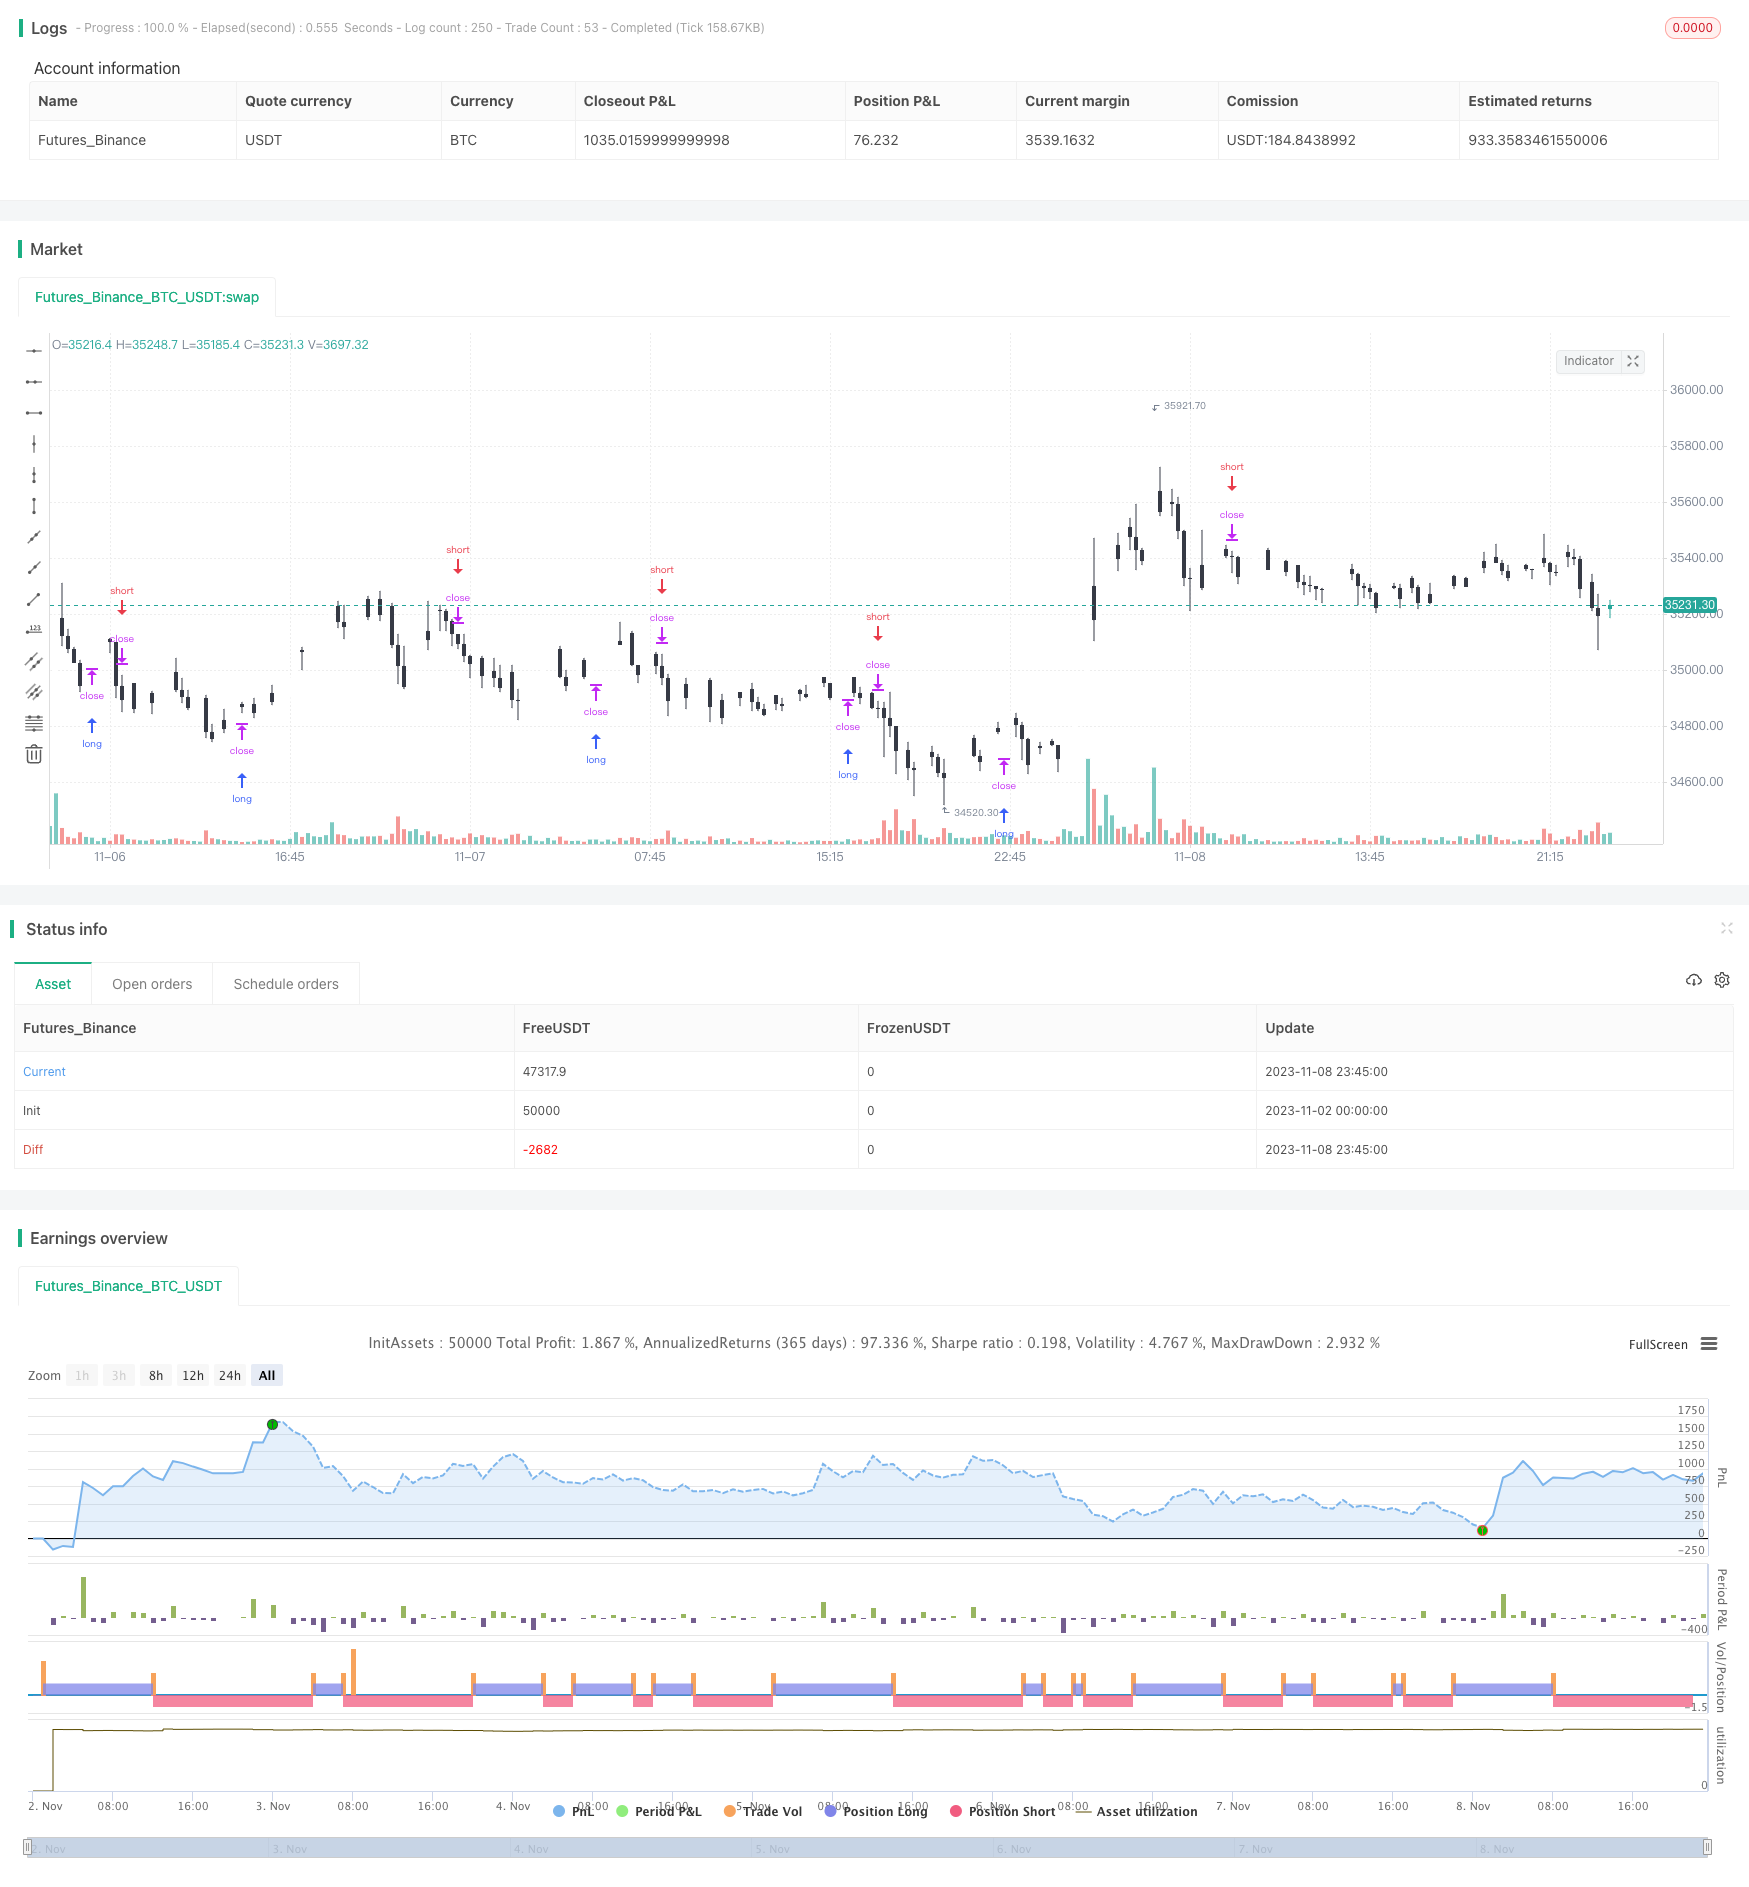
Overview
This strategy is based on momentum indicators combined with moving averages to track market trends. It goes long when there is strong upside momentum and goes short when there is strong downside momentum. It belongs to the category of trend following strategies.
Strategy Logic
Calculate the momentum of price as: (Current Price - Price N periods ago) / Price N periods ago
Calculate the moving average mid of price over N periods
Normalize the momentum value to the range of 0-1
When the normalized momentum is greater than 0.5 and price is above moving average, go long
When the normalized momentum is less than 0.5 and price is below moving average, go short
Use a moving stop loss mechanism with proper stop loss levels
The above covers the basic trading logic. When the market is trending, price will move persistently in one direction, generating large momentum values. The strategy judges the strength of the trend using the momentum and the direction using the moving average to decide on entry. Also, the stop loss is critical for controlling risks.
Advantage Analysis
This strategy has the following advantages:
Tracks market trends, with potentially large gains
Momentum is sensitive to price changes and responds quickly to trends
Moving averages filter out random noise and combine well with momentum
Stop loss mechanism limits loss on individual trades
Simple and clear logic, easy to implement and backtest
Flexible parameters can adapt to different periods and market regimes
Overall, this is a great strategy for trending markets. It can profit significantly from directional trends.
Risk Analysis
Despite the advantages, some risks need to be noted:
Breakout risk in uptrends when price reverses after breaking out
Reversal risk in downtrends when price bounces after breaking down
Whipsaw signals when price oscillates around moving average
Wrong signals if parameters are not properly set
Underperforms in rangebound choppy markets
Strict stop loss and movement required to prevent premature exit
To address these risks, stop loss strategy needs optimization, filter unnecessary signals with loose parameters, adjust parameters for different periods, and control position sizing.
Optimization Directions
Here are some ways the strategy can be further optimized:
Test different parameter combinations for best backtest results
Incorporate the Turtle Trading rules of exiting at 2N loss and 1N profit
Optimize stop loss with volatility indicators for adaptive stop loss
Add position sizing rules based on drawdown, time, etc
Test different momentum calculation methods like exponential moving average momentum
Add candlestick pattern filters for more robust signals
Utilize machine learning for parameter optimization, feature selection, etc
Incorporate some discretionary human input at key points
With these enhancements, the strategy may achieve better stability, adaptability, and profitability. But any optimization needs strict statistical validation to avoid overfitting.
Conclusion
The momentum tracking strategy is a simple and practical trend following approach. It can nimbly capture market trends and profit from riding bubbles and crashes. But curve fitting risks need to be managed with disciplined risk controls to maintain robustness. With parameter tuning and functionality extensions, the strategy can yield steady profits in more market regimes.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1_close | 0 | src: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_2 | 20 | lookback |
| v_input_3 | 0 | Bar color scheme: 1 | 2 |
Source Pine Script
/*backtest
start: 2023-11-02 00:00:00
end: 2023-11-09 00:00:00
period: 15m
basePeriod: 5m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
strategy("Momentum Strategy, rev.2", overlay=true)

//
// Data
//
src = input(close)
lookback = input(20)
cscheme=input(1, title="Bar color scheme", options=[1,2])

//
// Functions
//
momentum(ts, p) => (ts - ts[p]) / ts[p]

normalize(src, len) =>
    hi  = highest(src, len)
    lo  = lowest(src, len)
    res = (src - lo)/(hi - lo)

//
// Main
//
price = close
mid = sma(src, lookback)
mom = normalize(momentum(price, lookback),100)

//
// Bar Colors
//
clr1 = cscheme==1?black: red
clr2 = cscheme==1?white: green
barcolor(close < open ? clr1 : clr2)

//
// Strategy
//
if (mom > .5 and price > mid )
    strategy.entry("MomLE", strategy.long, stop=high+syminfo.mintick, comment="MomLE")
else
    strategy.cancel("MomLE")

if (mom < .5 and price < mid )
    strategy.entry("MomSE", strategy.short, stop=low-syminfo.mintick, comment="MomSE")
else
    strategy.cancel("MomSE")

//plot(strategy.equity, title="equity", color=red, linewidth=2, style=areabr)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-10. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Momentum-Tracking-Strategy-431672.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX Momentum Trend StrategyPine Script · Momentum · 10m
- Adaptive Trend Following Strategy Based on Momentum OscillatorPine Script · Momentum · 1d
- Bollinger Bands Momentum Trend Following Quantitative StrategyPine Script · Momentum · 1d
- Confirmed SMA Crossover Momentum StrategyPine Script · Momentum · 1d
- Cross Momentum Trend Following Strategy SMA RSI Cross Momentum SystemPine Script · Momentum · 1h
- Dual Moving Average Momentum Trading Strategy Time Optimized Trend Following SystemPine Script · Momentum · 2m