Strategy vault / Trend following
Moving Average Crossover Strategy 430064
This strategy is based on the moving average crossover principle. It goes long when the short-term moving average crosses above the long-term moving average from below, and goes short when the short-term moving…
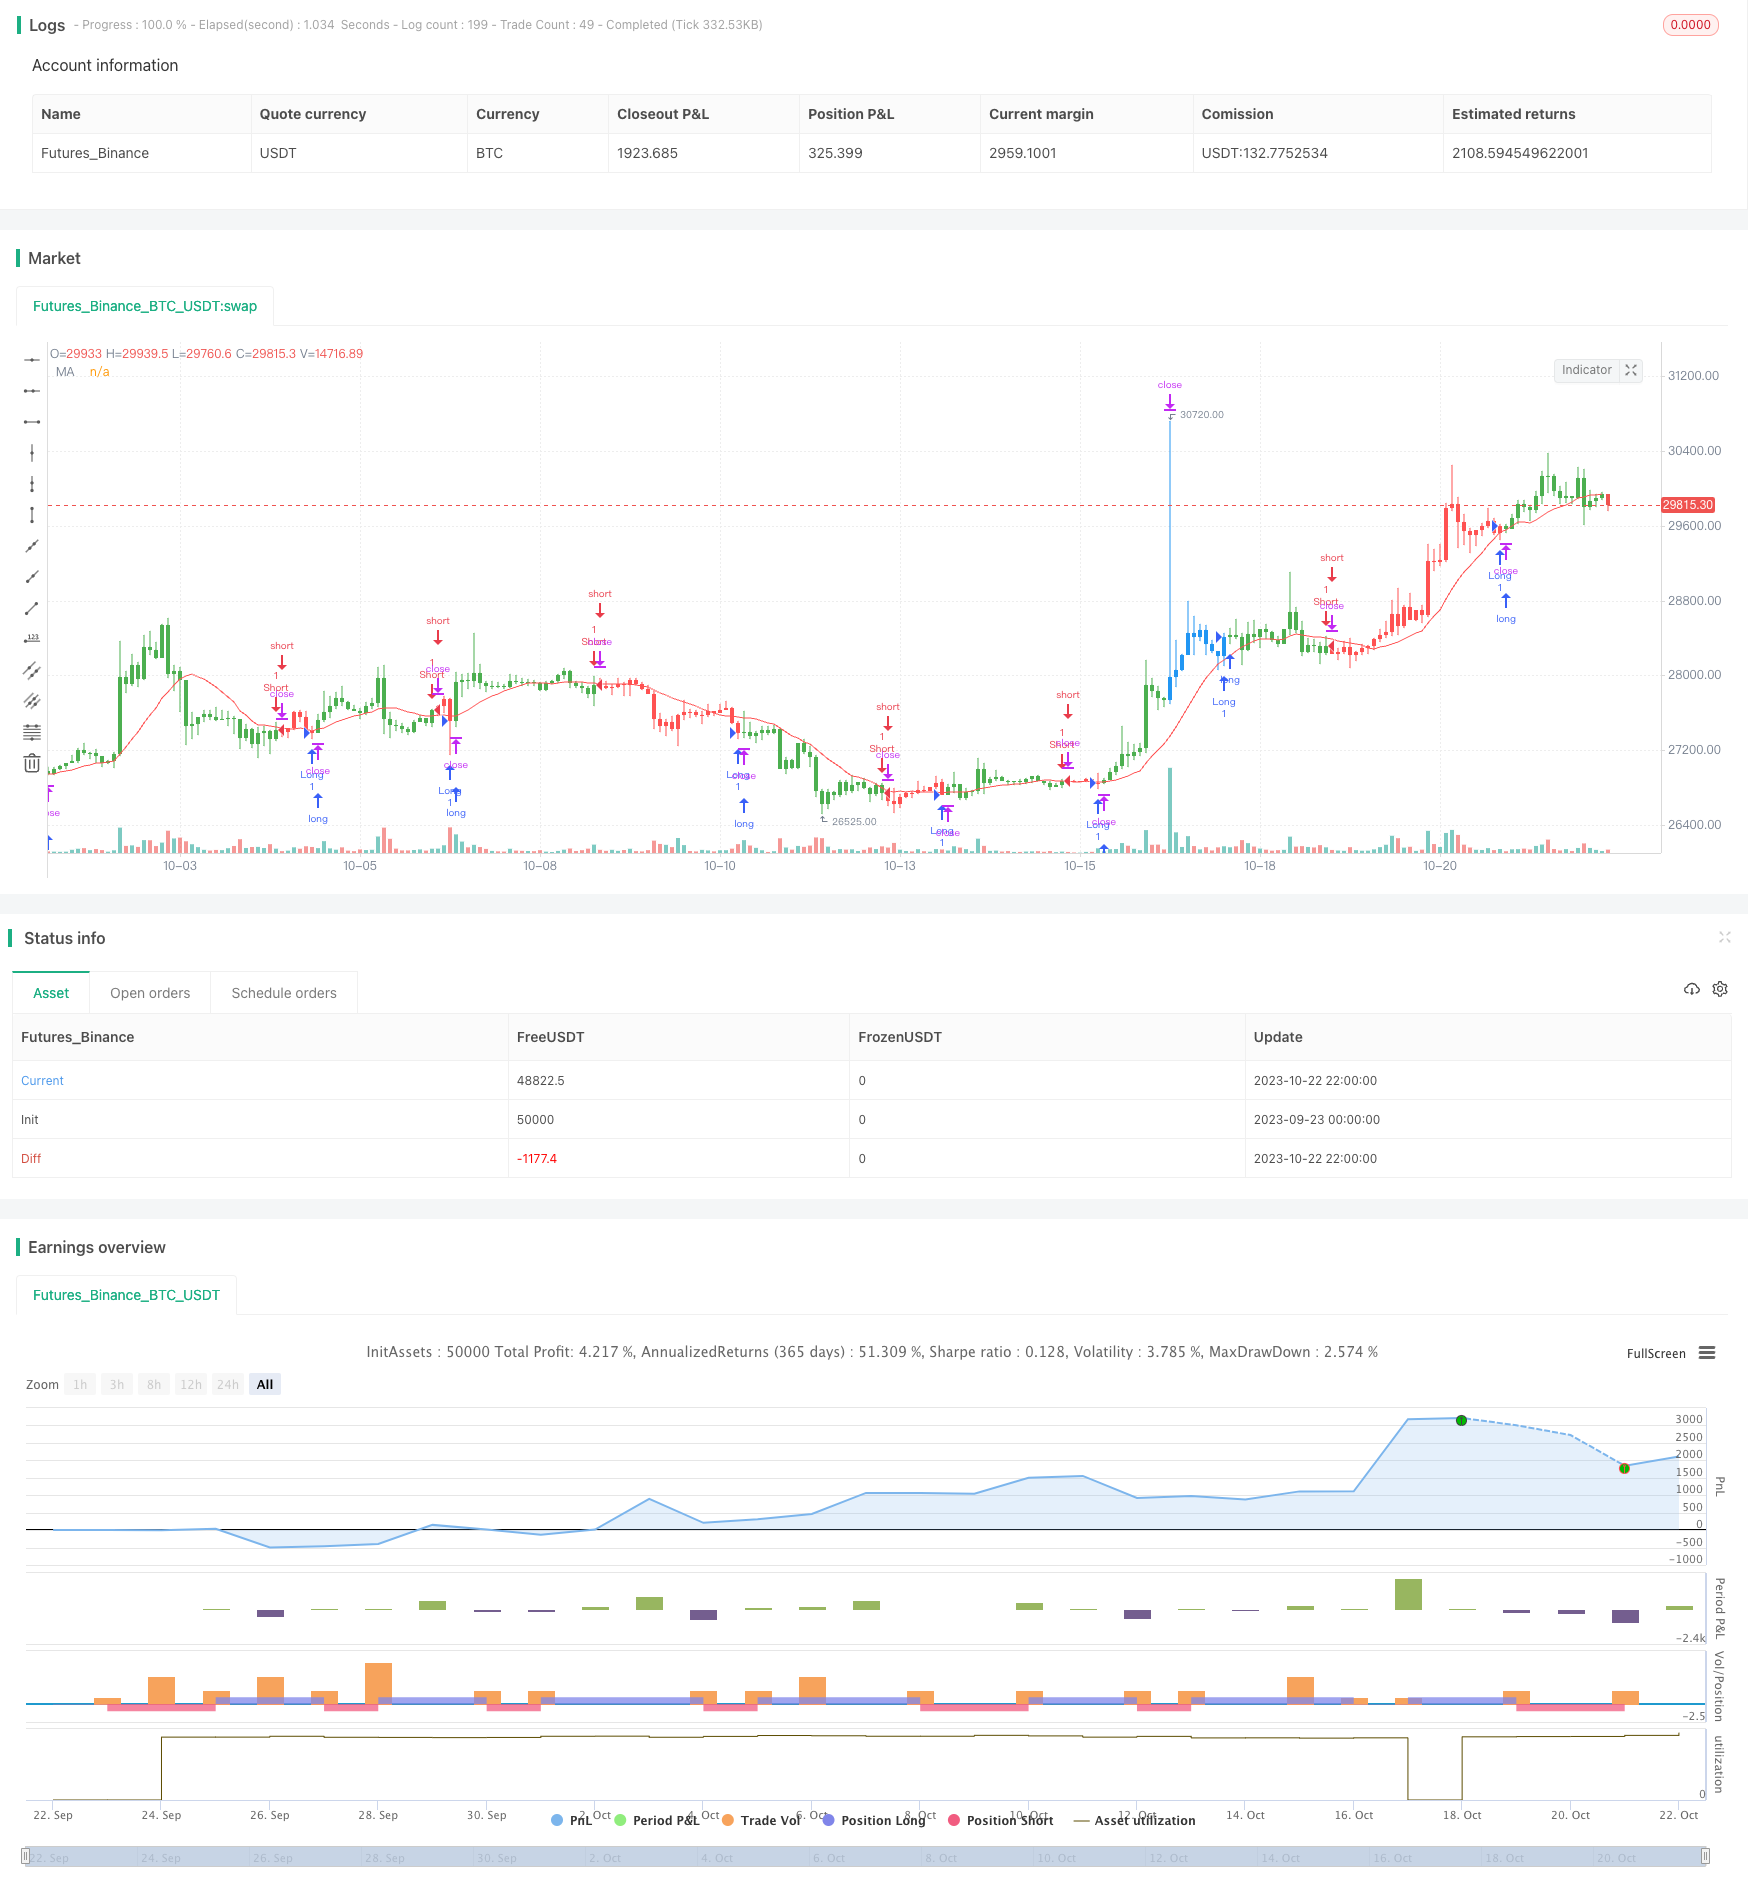
Overview
This strategy is based on the moving average crossover principle. It goes long when the short-term moving average crosses above the long-term moving average from below, and goes short when the short-term moving average crosses below the long-term moving average from above. It's a typical trend following strategy.
Strategy Logic
The strategy mainly calculates the short-term and long-term simple moving averages, and determines the trend direction based on their crossover.
Specifically, it first calculates the short-term moving average xMA and the long-term moving average, where the short-term period is Len, and the long-term period is 2*Len.
Then it checks if the short-term MA crosses above the long-term MA, and generates a long signal if the crossover happens. It also checks if the short-term MA crosses below the long-term MA, and generates a short signal if the crossover happens.
Upon receiving a long signal, it opens a long position at market price if there is no position. Upon receiving a short signal, it opens a short position at market price if there is no position.
In addition, stop loss and take profit points are configured. For long trades, the stop loss is set at entry price - stop loss percentage * entry price, and take profit at entry price + take profit percentage * entry price. For short trades, the stop loss is set at entry price + stop loss percentage * entry price, and take profit at entry price - take profit percentage * entry price.
Finally, the moving averages are plotted for visualization to assist with trend determination.
Advantages
Simple and easy to understand, suitable for beginners.
Can effectively track market trends based on moving average crossovers.
Risks are controlled by configuring stop loss and take profit.
Visualization of moving averages intuitively reflects trend changes.
Risks
Moving averages have lagging effects, which may cause missing the best entry points.
Improper stop loss configuration may result in stops being too wide or too tight.
Prices whipsawing may generate false signals.
Optimizing solely based on the moving average periods may lead to overfitting.
These risks can be reduced by using looser stops, optimizing moving average period combinations, adding filter indicators etc.
Optimization Directions
Add other indicators like MACD, KDJ for filtering to avoid false signals.
Optimize combinations of short and long moving average periods to find optimum parameters.
Test different stop loss/take profit strategies like trailing stops.
Add position sizing to optimize capital utilization.
Summary
The strategy has a clear and simple logic, can track trends effectively based on moving average crossovers, and has controllable risks. It is suitable for beginners to learn from. But relying solely on moving averages may generate false signals. There is still much room for optimizating it in various aspects to make it more robust.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_2 | 13 | Len |
| v_input_float_3 | 7 | Take Profit % |
| v_input_float_4 | 7 | Stop Loss % |
| v_input_1 | (?entry)Signal Token | |
| v_input_string_1 | 0 | Order Type: market | limit |
| v_input_float_1 | false | Order Price Offset |
| v_input_string_2 | 0 | Investment Type: percentage_balance | contract | margin | percentage_investment |
| v_input_float_2 | 100 | Amount |
Source Pine Script
/*backtest
start: 2023-09-23 00:00:00
end: 2023-10-23 00:00:00
period: 2h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
//@strategy_alert_message {{strategy.order.alert_message}}
////////////////////////////////////////////////////////////
//  Copyright by HPotter v2.0 19/09/2023
// MA Crossover Bot for OKX Exchange
////////////////////////////////////////////////////////////
var ALERTGRP_CRED = "entry"
signalToken = input("", "Signal Token", inline = "11", group = ALERTGRP_CRED)
OrderType = input.string("market", "Order Type", options = ["market", "limit"], inline = "21", group = ALERTGRP_CRED)
OrderPriceOffset = input.float(0, "Order Price Offset", minval = 0, maxval = 100, step = 0.01, inline = "21", group = ALERTGRP_CRED)
InvestmentType = input.string("percentage_balance", "Investment Type", options = ["margin", "contract", "percentage_balance", "percentage_investment"], inline = "31", group = ALERTGRP_CRED)
Amount = input.float(100, "Amount", minval = 0.01, inline = "31", group = ALERTGRP_CRED)

getAlertMsg(action, instrument, signalToken, orderType, orderPriceOffset, investmentType, amount) =>
    str = '{'
    str := str + '"action": "' + action + '", '
    str := str + '"instrument": "' + instrument + '", '
    str := str + '"signalToken": "' + signalToken + '", '
    //str := str + '"timestamp": "' + str.format_time(timenow, "yyyy-MM-dd'T'HH:mm:ssZ", "UTC+0") + '", '
    str := str + '"timestamp": "' + '{{timenow}}' + '", '
    str := str + '"orderType": "' + orderType + '", '
    str := str + '"orderPriceOffset": "' + str.tostring(orderPriceOffset) + '", '
    str := str + '"investmentType": "' + investmentType + '", '
    str := str + '"amount": "' + str.tostring(amount) + '"'
    str := str + '}'
    str

getOrderAlertMsgExit(action, instrument, signalToken) =>
    str = '{'
    str := str + '"action": "' + action + '", '
    str := str + '"instrument": "' + instrument + '", '
    str := str + '"signalToken": "' + signalToken + '", '
    str := str + '"timestamp": "' + '{{timenow}}' + '", '
    str := str + '}'
    str

strategy(title='OKX: MA Crossover', overlay=true)
Len = input(13)
Profit = input.float(7, title='Take Profit %', minval=0.01) / 100
Stop =  input.float(7, title='Stop Loss %', minval=0.01) / 100
xMA = ta.sma(close, Len)
//Robot State
isLong = strategy.position_size > 0
isShort = strategy.position_size < 0
isFlat = strategy.position_size == 0
//Current Signal
doLong = low < xMA[1] ? true : false
doShort =   high > xMA[1] ? true:  false
//Backtest Start Date
tm =  timestamp(2022, 01, 01, 09, 30)
//Entry and exit orders
if  doLong[2] == false and isLong == false and doLong and time > tm
    strategy.cancel_all()
    buyAlertMsgExit = getOrderAlertMsgExit(action = 'EXIT_LONG', instrument = syminfo.ticker, signalToken = signalToken)
    buyAlertMsg = getAlertMsg(action = 'ENTER_LONG', instrument = syminfo.ticker, signalToken = signalToken, orderType =  OrderType, orderPriceOffset =  OrderPriceOffset, investmentType =  InvestmentType, amount = Amount)
    strategy.entry('Long', strategy.long, limit = close, comment='Long', alert_message =buyAlertMsg)
    strategy.exit("ExitLong", 'Long', stop=close - close * Stop  , limit = close + close * Profit , qty_percent = 100, alert_message = buyAlertMsgExit)
if doShort[2] == false and isShort == false and doShort and time > tm
    strategy.cancel_all()
    sellAlertMsgExit = getOrderAlertMsgExit(action = 'EXIT_SHORT', instrument = syminfo.ticker, signalToken = signalToken)
    sellAlertMsg = getAlertMsg(action = 'ENTER_SHORT', instrument = syminfo.ticker, signalToken = signalToken, orderType =  OrderType, orderPriceOffset =  OrderPriceOffset, investmentType =  InvestmentType, amount = Amount)
    strategy.entry('Short', strategy.short, limit=close, comment='Short', alert_message = sellAlertMsg)
    strategy.exit("ExitShort", 'Short', stop=close + close * Stop  , limit = close - close * Profit  , qty_percent = 100, alert_message = sellAlertMsgExit)
//Visual
barcolor(isShort  ? color.red : isLong ? color.green : color.blue)
plot(xMA, color=color.new(color.red, 0), title='MA')Published by ChaoZhang on the FMZ strategy square · last modified 2023-10-24. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Moving-Average-Crossover-Strategy-430064.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dual MA Crossover Trend Tracking StrategyPine Script · Trend following · 1h
- Dual Moving Average Convergence Trend Tracking StrategyPine Script · Trend following · 1d
- Dual Moving Average Crossover Strategy with Stop Loss and Take ProfitPine Script · Trend following · 4h
- Dual SMA Crossover StrategyPine Script · Trend following · 5m