Strategy vault / Trend following
Multi Parameter Stochastic Intelligent Trend Trading Strategy
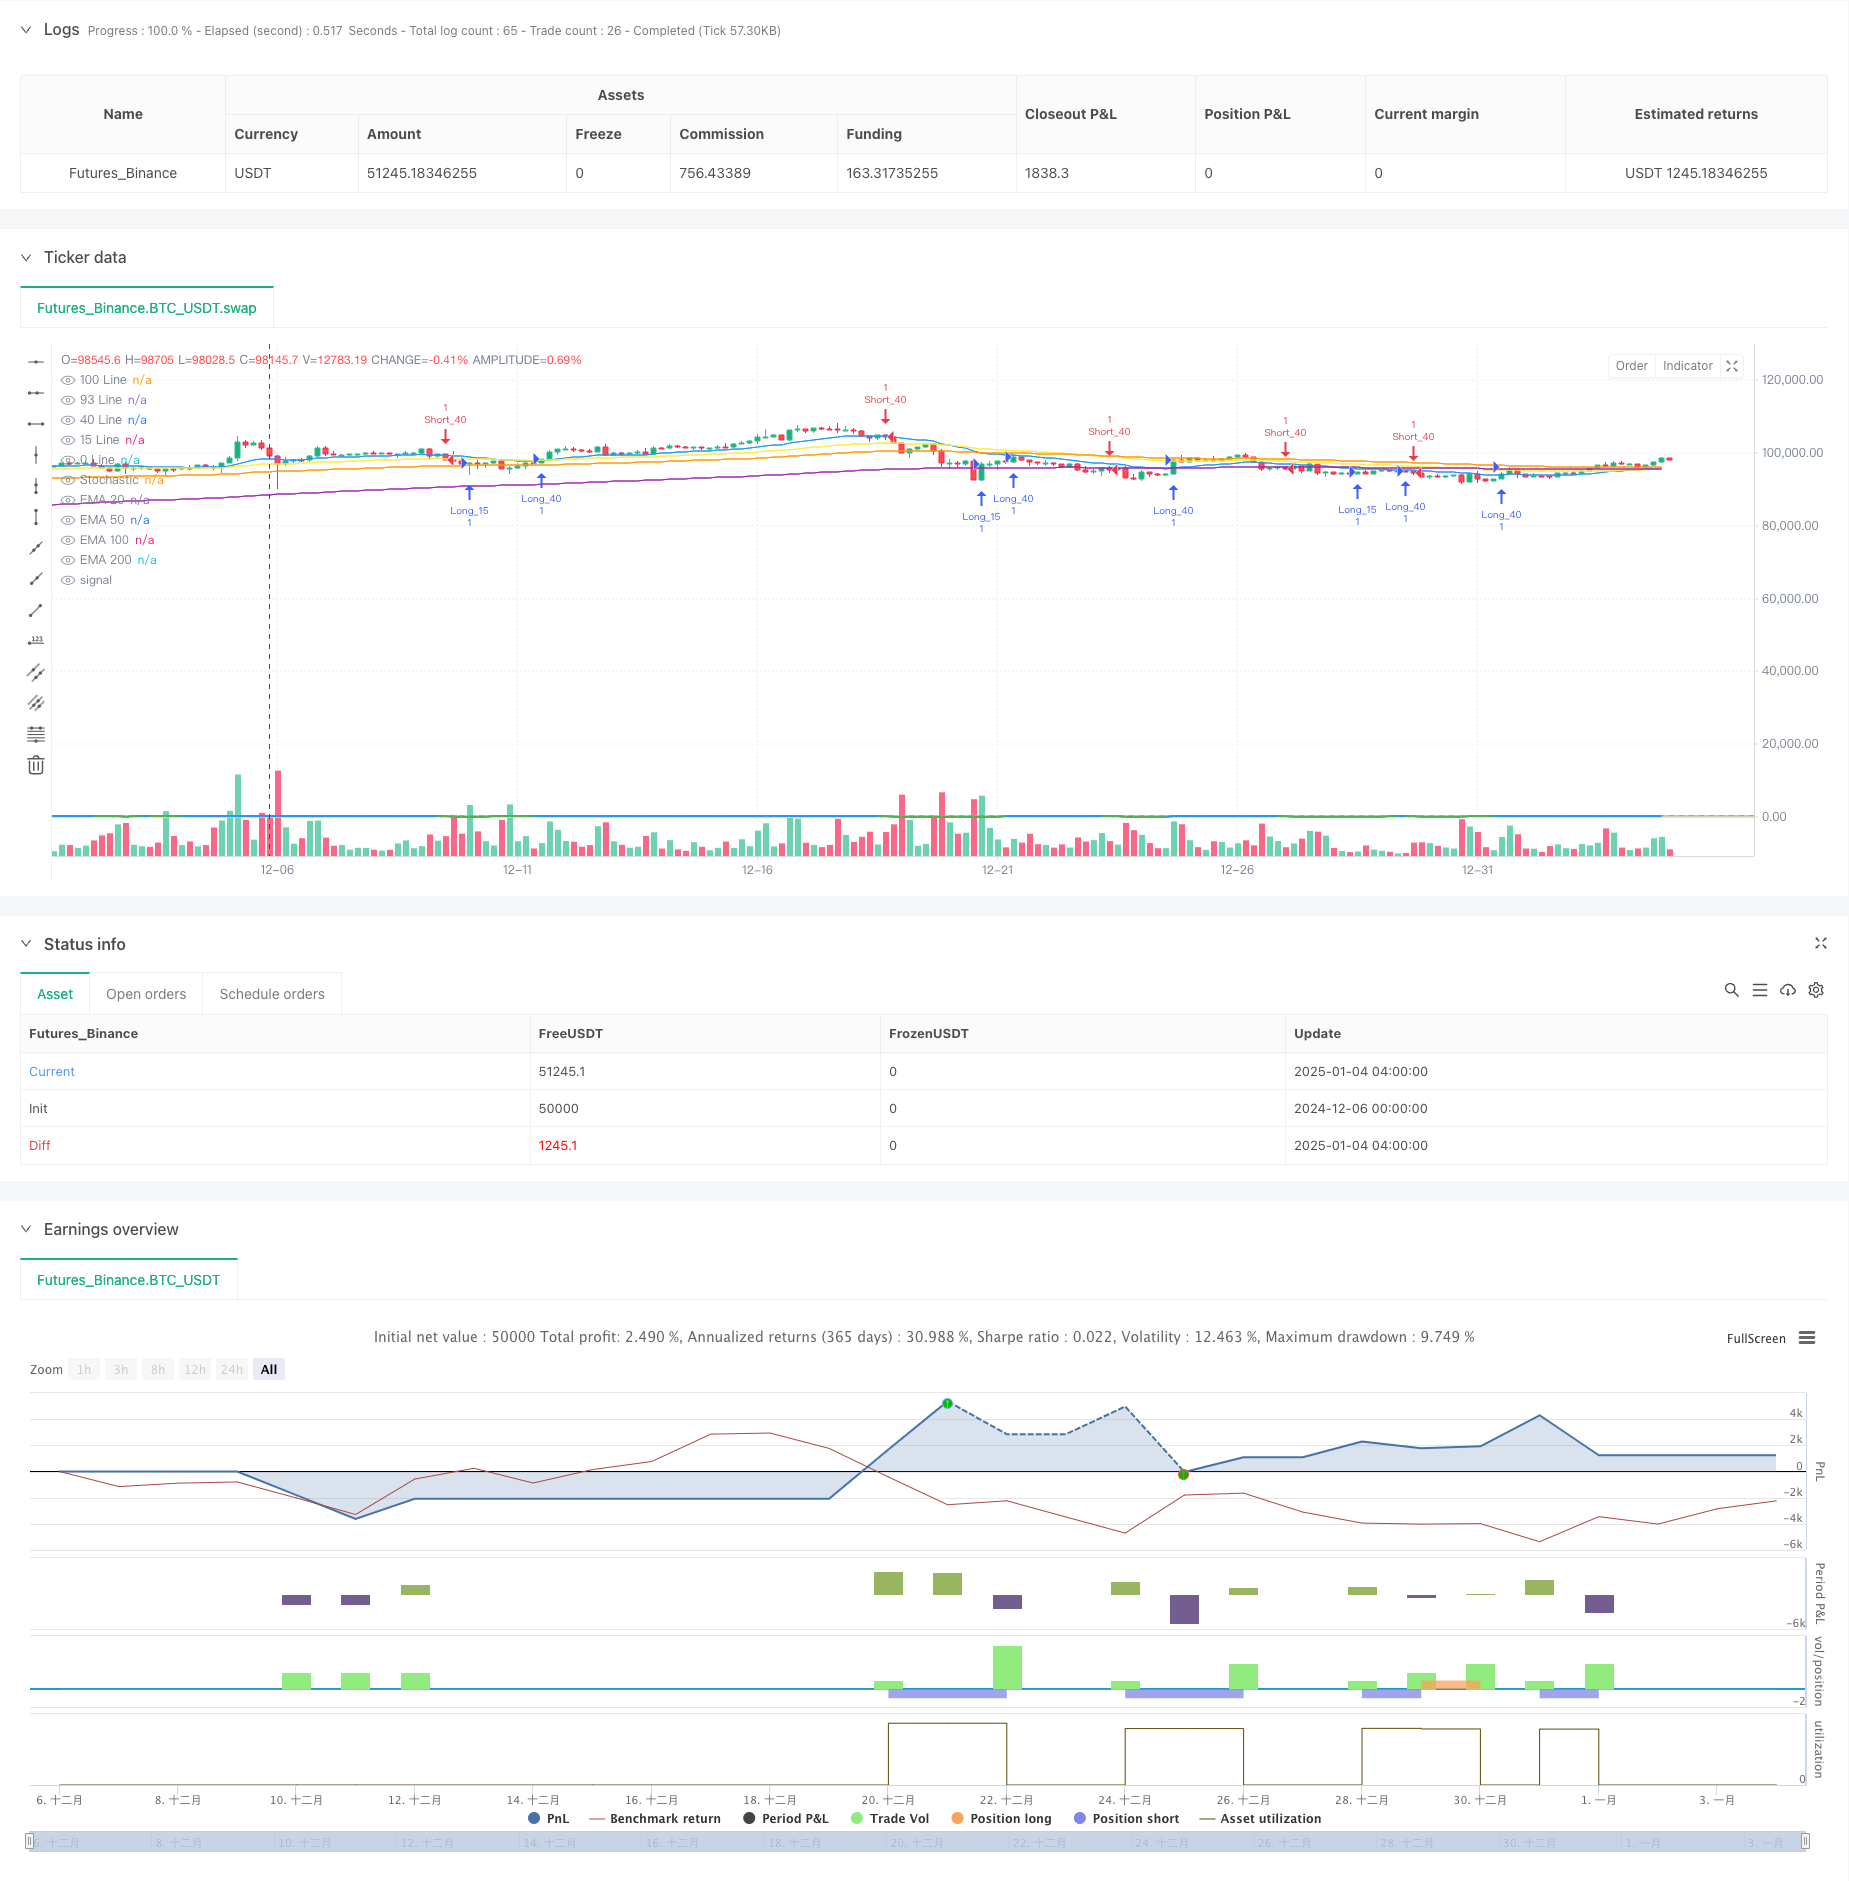
This strategy is an intelligent trading system based on the Stochastic Oscillator. It combines dynamic trend identification, multiple signal confirmation, and intelligent risk management capabilities to automatically…
Overview
This strategy is an intelligent trading system based on the Stochastic Oscillator. It combines dynamic trend identification, multiple signal confirmation, and intelligent risk management capabilities to automatically identify market overbought/oversold conditions and execute trades. The strategy uses a color-coding system to visually display market conditions, integrates multiple period moving averages (EMA) for trend confirmation, and provides flexible stop-loss and take-profit settings.
Strategy Principles
The core of the strategy is based on the combination of the Stochastic Oscillator and multiple moving average systems. Trading signals are generated when the K value breaks through preset overbought/oversold levels (93/15) or the middle level (40). The system visually displays market conditions through color changes (red indicates potential decline, green indicates potential rise, blue indicates neutral). It also incorporates 20, 50, 100, and 200-period exponential moving averages (EMA) for trend confirmation. The strategy includes an intelligent risk management system supporting different risk-reward ratios such as 1:1, 1:4, and 1:8.
Strategy Advantages
- Clear and intuitive signal system with color coding for quick market state identification
- Multiple signal confirmation mechanism reduces false signal risk
- Flexible risk management system supporting customizable risk-reward ratios
- Integration of multiple period moving averages for trend confirmation
- Automated stop-loss and take-profit settings reduce manual operation risk
- Clear code structure, easy to maintain and optimize
Strategy Risks
- May generate frequent trading signals in ranging markets
- Fixed overbought/oversold thresholds may not suit all market conditions
- Moving average system may lag in volatile markets
- Requires proper stop-loss settings for risk control Solutions include: adding signal filtering mechanisms, dynamic threshold adjustment, optimizing moving average parameters, strict stop-loss execution
Strategy Optimization Directions
- Introduce adaptive threshold system to dynamically adjust overbought/oversold levels based on market volatility
- Add volume indicators for signal confirmation
- Develop intelligent signal filtering mechanism to reduce false signals
- Optimize moving average parameters to improve trend judgment accuracy
- Introduce machine learning algorithms for parameter optimization
- Add drawdown control mechanism
Summary
The strategy builds a comprehensive trading system by combining the Stochastic Oscillator, moving average system, and intelligent risk management. The strategy design emphasizes practicality and operability, suitable for traders with different risk preferences. Through continuous optimization and improvement, the strategy has the potential to maintain stable performance across different market conditions.
Source Pine Script
/*backtest
start: 2024-12-06 00:00:00
end: 2025-01-04 08:00:00
period: 4h
basePeriod: 4h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This Pine Script™ code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © petrusvorenusperegrinus

//██████╗ ███████╗████████╗██████╗ ██╗   ██╗███████╗
//██╔══██╗██╔════╝╚══██╔══╝██╔══██╗██║   ██║██╔════╝
//██████╔╝█████╗     ██║   ██████╔╝██║   ██║███████╗
//██╔═══╝ ██╔══╝     ██║   ██╔══██╗██║   ██║╚════██║
//██║     ███████╗   ██║   ██║  ██║╚██████╔╝███████║
//╚═╝     ╚══════╝   ╚═╝   ╚═╝  ╚═╝ ╚═════╝ ╚══════╝

//██╗   ██╗ ██████╗ ██████╗ ███████╗███╗   ██╗██╗   ██╗███████╗
//██║   ██║██╔═══██╗██╔══██╗██╔════╝████╗  ██║██║   ██║██╔════╝
//██║   ██║██║   ██║██████╔╝█████╗  ██╔██╗ ██║██║   ██║███████╗
//╚██╗ ██╔╝██║   ██║██╔══██╗██╔══╝  ██║╚██╗██║██║   ██║╚════██║
// ╚████╔╝ ╚██████╔╝██║  ██║███████╗██║ ╚████║╚██████╔╝███████║
//  ╚═══╝   ╚═════╝ ╚═╝  ╚═╝╚══════╝╚═╝  ╚═══╝ ╚═════╝ ╚══════╝

//██████╗ ███████╗██████╗ ███████╗ ██████╗ ██████╗ ██╗███╗   ██╗██╗   ██╗███████╗
//██╔══██╗██╔════╝██╔══██╗██╔════╝██╔════╝ ██╔══██╗██║████╗  ██║██║   ██║██╔════╝
//██████╔╝█████╗  ██████╔╝█████╗  ██║  ███╗██████╔╝██║██╔██╗ ██║██║   ██║███████╗
//██╔═══╝ ██╔══╝  ██╔══██╗██╔══╝  ██║   ██║██╔══██╗██║██║╚██╗██║██║   ██║╚════██║
//██║     ███████╗██║  ██║███████╗╚██████╔╝██║  ██║██║██║ ╚████║╚██████╔╝███████║
//╚═╝     ╚══════╝╚═╝  ╚═╝╚══════╝ ╚═════╝ ╚═╝  ╚═╝╚═╝╚═╝  ╚═══╝ ╚═════╝ ╚══════╝

//@version=6
strategy("CM Stochastic POP Method 3", shorttitle="CM_Stochastic POP_M3", overlay=true)

// Stochastic Settings
length = input.int(14, "Stochastic Length", minval=1)
smoothK = input.int(5, "Smooth K", minval=1)

// Risk:Reward Settings
use_rr = input.bool(true, "Use Risk:Reward Ratio")
use_sl = input.bool(true, "Use Stop Loss")  // New input for Stop Loss toggle
rr_options = input.string("1:1", "Risk:Reward Ratio", options=["1:1", "1:4", "1:8"])
stop_percent = input.float(1.0, "Stop Loss (%)", minval=0.1, step=0.1)

// Convert selected R:R ratio to number
get_rr_multiplier(rr) =>
    switch rr
        "1:1" => 1.0
        "1:4" => 4.0
        "1:8" => 8.0
        => 1.0  // default case
rr_ratio = get_rr_multiplier(rr_options)

// Fixed Level Settings
upperLine = 93.0  // Fixed sell level
midLine = 40.0    // Buy/Sell level
lowerLine = 15.0  // Fixed buy level

// EMA Settings
ema20 = ta.ema(close, 20)
ema50 = ta.ema(close, 50)
ema100 = ta.ema(close, 100)
ema200 = ta.ema(close, 200)

// Calculate Stochastic with smoothing
k = ta.sma(ta.stoch(close, high, low, length), smoothK)

// Dynamic color based on K value
kColor = k >= upperLine ? color.red :    // Above 93 -> Red
         k <= lowerLine ? color.green :   // Below 15 -> Green
         k <= midLine ? color.green :     // Below 40 -> Green
         color.blue                       // Between 40-93 -> Blue

// Buy Signals:
longCondition1 = ta.crossover(k, lowerLine)   // Cross above 15
longCondition2 = ta.crossover(k, midLine)     // Cross above 40

// Sell Signals:
shortCondition1 = ta.crossunder(k, upperLine) // Cross below 93
shortCondition2 = ta.crossunder(k, midLine)   // Cross below 40

calc_tp_sl(entry_price, is_long) =>
    sl_distance = entry_price * (stop_percent / 100)
    sl = is_long ? entry_price - sl_distance : entry_price + sl_distance
    tp_distance = sl_distance * rr_ratio
    tp = is_long ? entry_price + tp_distance : entry_price - tp_distance
    [sl, tp]

// Long entries
if (longCondition1)
    if (use_rr)
        [sl, tp] = calc_tp_sl(close, true)
        strategy.entry("Long_15", strategy.long)
        if (use_sl)
            strategy.exit("Exit_15", "Long_15", stop=sl, limit=tp)
        else
            strategy.exit("Exit_15", "Long_15", limit=tp)
    else
        strategy.entry("Long_15", strategy.long)

if (longCondition2)
    if (use_rr)
        [sl, tp] = calc_tp_sl(close, true)
        strategy.entry("Long_40", strategy.long)
        if (use_sl)
            strategy.exit("Exit_40", "Long_40", stop=sl, limit=tp)
        else
            strategy.exit("Exit_40", "Long_40", limit=tp)
    else
        strategy.entry("Long_40", strategy.long)

// Short entries
if (shortCondition1)
    if (use_rr)
        [sl, tp] = calc_tp_sl(close, false)
        strategy.entry("Short_93", strategy.short)
        if (use_sl)
            strategy.exit("Exit_93", "Short_93", stop=sl, limit=tp)
        else
            strategy.exit("Exit_93", "Short_93", limit=tp)
    else
        strategy.entry("Short_93", strategy.short)

if (shortCondition2)
    if (use_rr)
        [sl, tp] = calc_tp_sl(close, false)
        strategy.entry("Short_40", strategy.short)
        if (use_sl)
            strategy.exit("Exit_40", "Short_40", stop=sl, limit=tp)
        else
            strategy.exit("Exit_40", "Short_40", limit=tp)
    else
        strategy.entry("Short_40", strategy.short)

// Plot EMAs
plot(ema20, title="EMA 20", color=color.blue, linewidth=1, force_overlay = true)
plot(ema50, title="EMA 50", color=color.yellow, linewidth=1, force_overlay = true)
plot(ema100, title="EMA 100", color=color.orange, linewidth=1, force_overlay = true)
plot(ema200, title="EMA 200", color=color.purple, linewidth=1, force_overlay = true)

// Plot Stochastic line
plot(k, title="Stochastic", color=kColor, linewidth=2)

// Plot reference lines
hline(100, title="100 Line", color=color.white, linestyle=hline.style_solid)
hline(upperLine, title="93 Line", color=color.red, linestyle=hline.style_solid)
hline(midLine, title="40 Line", color=color.green, linestyle=hline.style_dashed)
hline(lowerLine, title="15 Line", color=color.green, linestyle=hline.style_solid)
hline(0, title="0 Line", color=color.white, linestyle=hline.style_solid)Published by ChaoZhang on the FMZ strategy square · last modified 2025-01-06. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Multi-Parameter-Stochastic-Intelligent-Trend-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- EMA AROON ASHPine Script · Trend following · 3m
- EMA SMA Multi Indicator Comprehensive Trend Following StrategyPine Script · Trend following · 1h
- EMA200 and Stochastic RSI StrategyPine Script · Trend following · 1h
- Intraday Stochastic Oscillator with Double Moving Average Crossover StrategyPine Script · Trend following · 1d
- Multi Indicator Trend Divergence Quantitative Trading StrategyPine Script · Trend following · 1d
- Multifactor Driven Trend Trading StrategyPine Script · Trend following · 1m