Multi Period Bollinger Bands Trend Breakout Strategy with Volatility Risk Control Model
This strategy is a trend following system that combines Bollinger Bands, volatility metrics, and risk management. It captures trending opportunities by monitoring price breakouts beyond Bollinger Bands while…
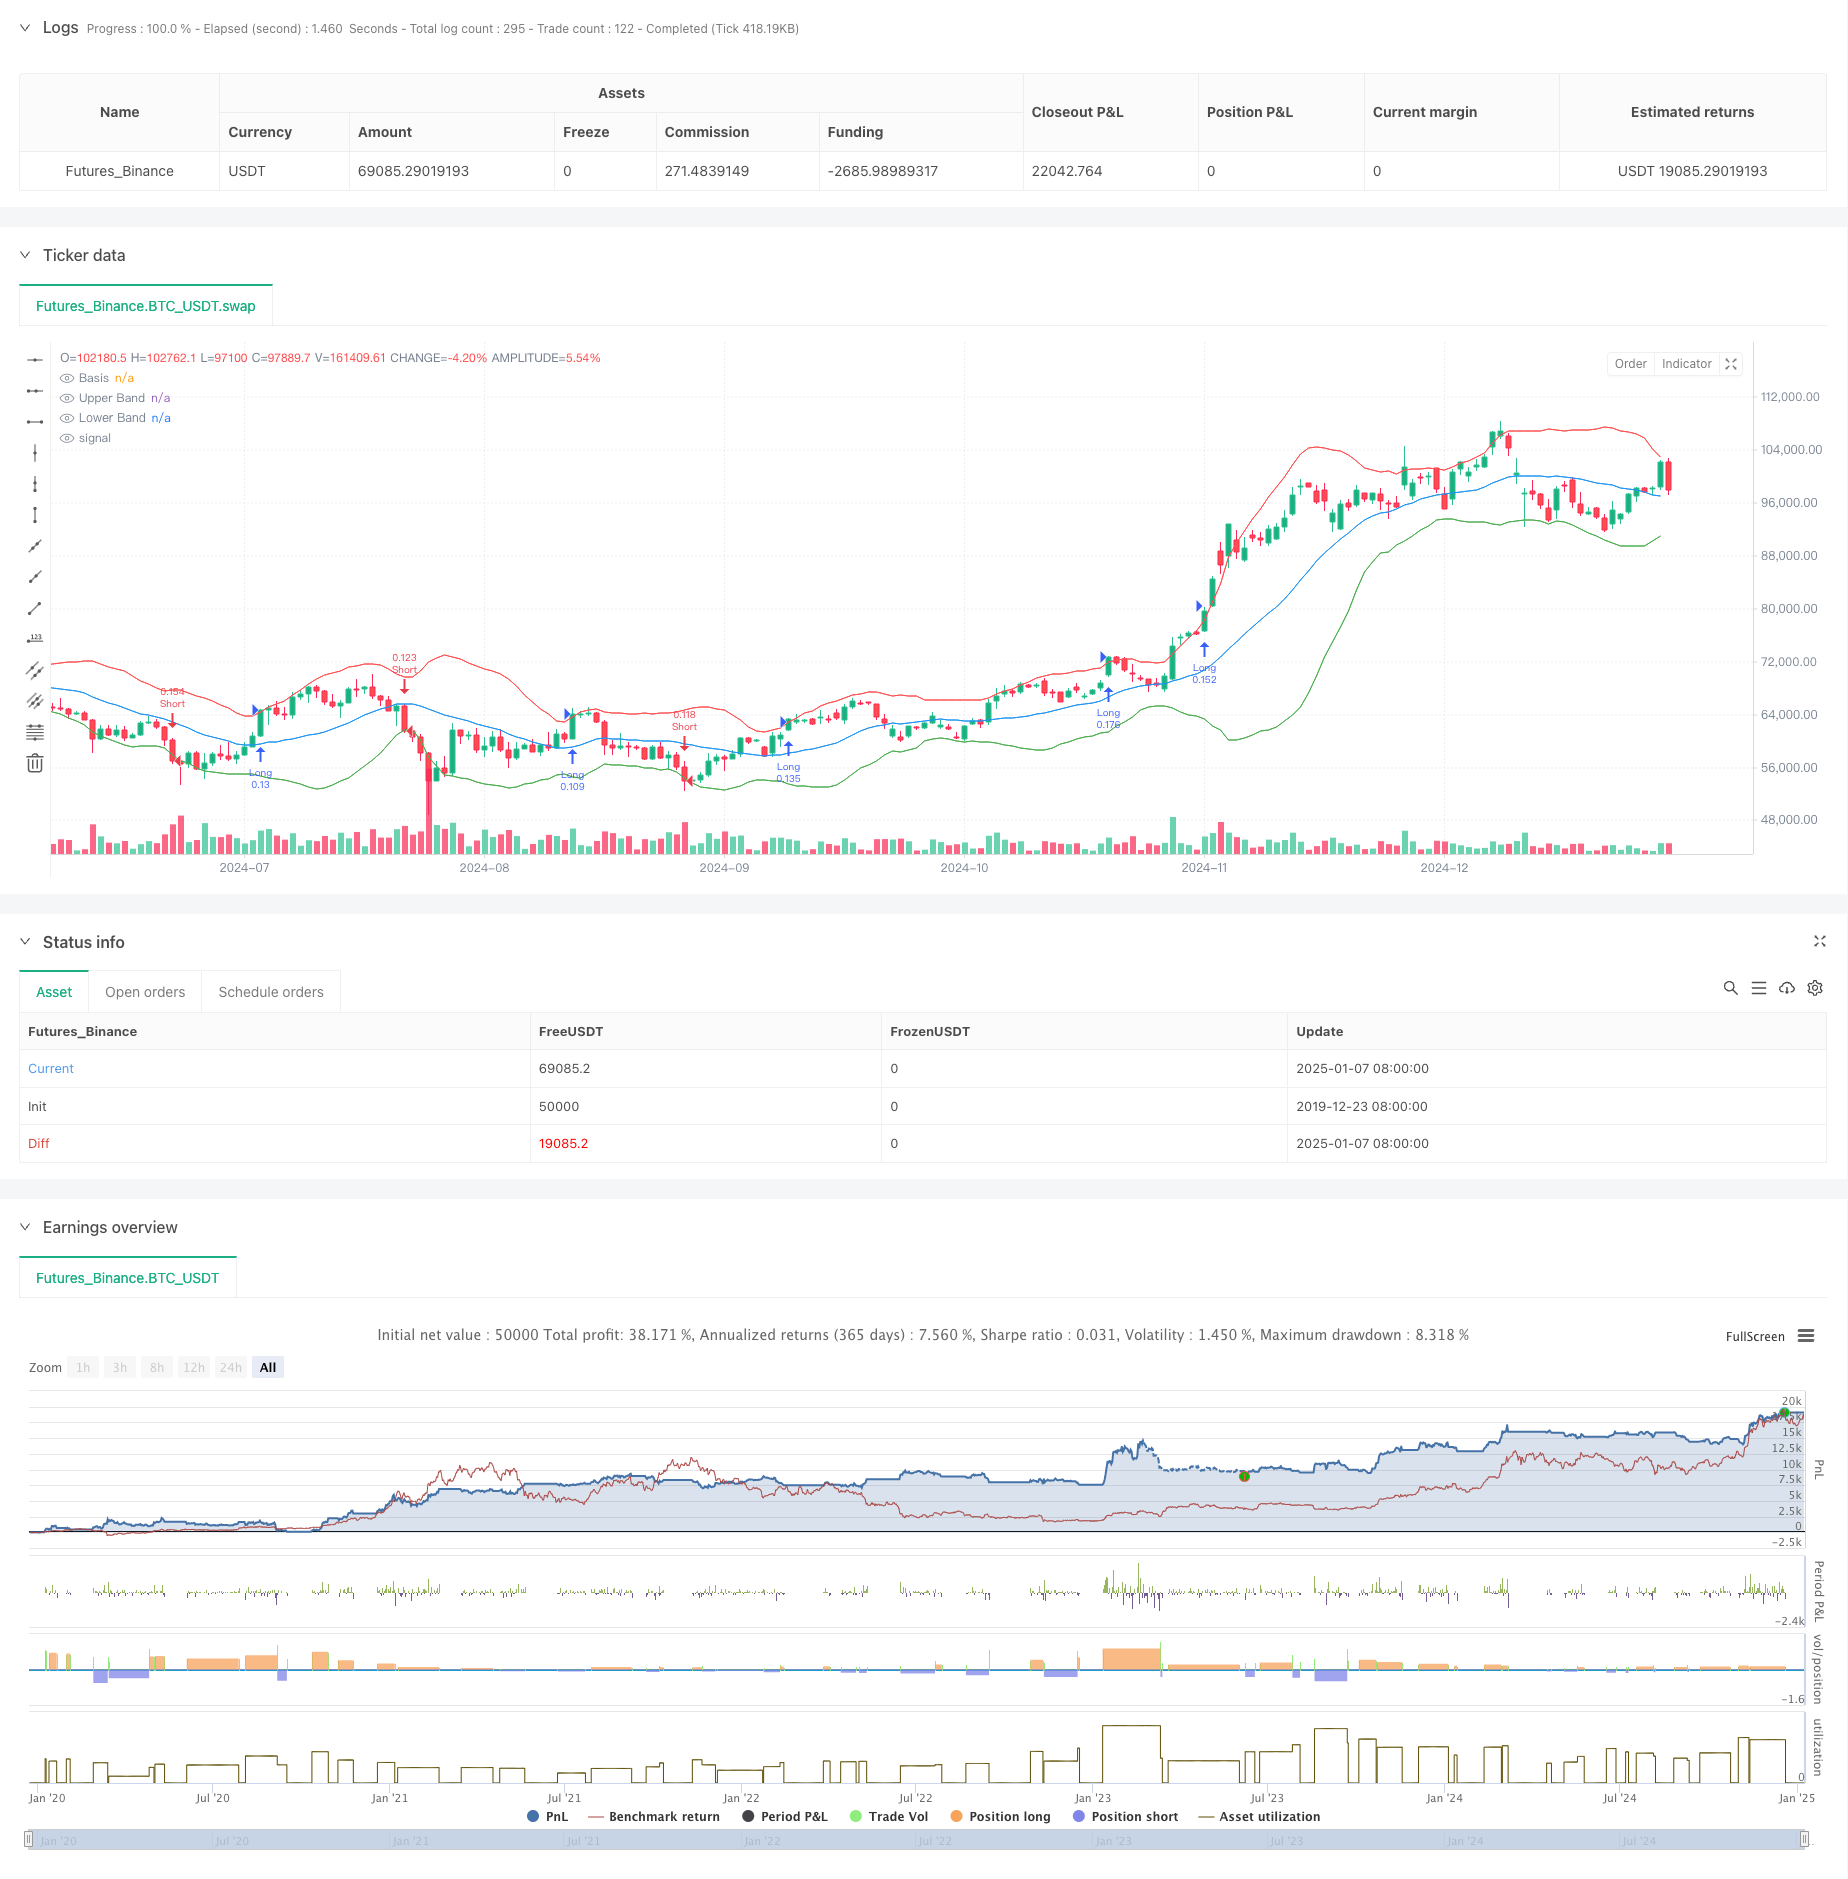
Overview
This strategy is a trend following system that combines Bollinger Bands, volatility metrics, and risk management. It captures trending opportunities by monitoring price breakouts beyond Bollinger Bands while dynamically adjusting position sizes using ATR for precise risk control. The strategy also incorporates a consolidation period detection mechanism to effectively filter false signals in ranging markets.
Strategy Principles
The strategy operates based on the following core logic:
- Uses a 20-period moving average as the middle band of Bollinger Bands, with upper and lower bands at 2 standard deviations.
- Identifies market consolidation periods by comparing current Bollinger Band width to its moving average.
- During non-consolidation periods, enters long positions on upper band breakouts and short positions on lower band breakouts.
- Utilizes 14-period ATR to dynamically calculate stop-loss levels and sets take-profit levels based on a 2:1 risk-reward ratio.
- Automatically calculates position sizes for each trade based on 1% account risk limit and ATR value.
Strategy Advantages
- High Adaptability - Bollinger Bands automatically adjust width based on market volatility, adapting to different market conditions.
- Comprehensive Risk Control - Effectively controls risk per trade through percentage risk limits and dynamic position sizing using ATR.
- High Signal Quality - Filters low-quality signals by identifying consolidation periods, improving win rate.
- Complete Trading System - Includes entry, exit, and position management components.
- Clear Operating Rules - Clear rules for signal generation and position calculation, easy to execute.
Strategy Risks
- Trend Reversal Risk - May suffer significant losses during sudden trend reversals.
- Slippage Impact - May face significant slippage costs during highly volatile periods.
- False Breakout Risk - False breakouts may still occur despite consolidation filtering.
- Capital Efficiency - May generate frequent trades in ranging markets, increasing transaction costs.
- Parameter Sensitivity - Strategy performance significantly affected by choice of Bollinger Bands and risk control parameters.
Optimization Directions
- Add Trend Confirmation Indicators - Can incorporate other trend indicators like MACD or RSI for signal confirmation.
- Improve Consolidation Detection - Can introduce volume information to enhance consolidation period detection accuracy.
- Dynamic Parameter Adjustment - Automatically adjust Bollinger Bands and ATR parameters based on market volatility.
- Enhanced Stop-Loss Mechanism - Can add trailing stop-loss functionality for better profit protection.
- Add Time Filters - Consider adding trading time windows to avoid low liquidity periods.
Summary
This strategy captures trends through Bollinger Bands breakouts while incorporating a comprehensive risk control system. Its strengths lie in high adaptability and controlled risk, though attention must be paid to false breakouts and trend reversal risks. The strategy has room for further improvement through adding trend confirmation indicators and optimizing parameter adjustment mechanisms. Overall, it represents a logically sound and practical trend following strategy.
Source Pine Script
/*backtest
start: 2019-12-23 08:00:00
end: 2025-01-08 08:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Bollinger Bands Breakout Strategy", overlay=true)

// Input parameters
length = input(20, title="Bollinger Bands Length")
stdDev = input(2.0, title="Standard Deviation")
riskRewardRatio = input(2.0, title="Risk/Reward Ratio")
atrLength = input(14, title="ATR Length")
riskPercentage = input(1.0, title="Risk Percentage per Trade")

// Calculate Bollinger Bands
basis = ta.sma(close, length)
dev = stdDev * ta.stdev(close, length)
upperBand = basis + dev
lowerBand = basis - dev

// Calculate ATR for position sizing
atr = ta.atr(atrLength)

// Plot Bollinger Bands
plot(basis, color=color.blue, title="Basis")
plot(upperBand, color=color.red, title="Upper Band")
plot(lowerBand, color=color.green, title="Lower Band")

// Market Consolidation Detection
isConsolidating = (upperBand - lowerBand) < ta.sma(upperBand - lowerBand, length) * 0.5

// Breakout Conditions
longCondition = ta.crossover(close, upperBand) and not isConsolidating
shortCondition = ta.crossunder(close, lowerBand) and not isConsolidating

// Risk Management: Calculate position size
equity = strategy.equity
riskAmount = equity * (riskPercentage / 100)
positionSize = riskAmount / (atr * riskRewardRatio)

// Execute trades with risk management
if (longCondition)
    strategy.entry("Long", strategy.long, qty=positionSize)
    strategy.exit("Take Profit", from_entry="Long", limit=close + atr * riskRewardRatio, stop=close - atr)

if (shortCondition)
    strategy.entry("Short", strategy.short, qty=positionSize)
    strategy.exit("Take Profit", from_entry="Short", limit=close - atr * riskRewardRatio, stop=close + atr)

// Alert conditions for breakouts
alertcondition(longCondition, title="Long Breakout", message="Long breakout detected!")
alertcondition(shortCondition, title="Short Breakout", message="Short breakout detected!")
Published by ChaoZhang on the FMZ strategy square · last modified 2025-01-10. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Multi-Period-Bollinger-Bands-Trend-Breakout-Strategy-with-Volatility-Risk-Control-Model.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Momentum Breakout Moving Average StrategyPine Script · Breakout · 1d
- Momentum Breakout Trading Strategy 440964Pine Script · Breakout · 5m
- Moving Average Crossover and Upper Rail Breakthrough Impulse StrategyPine Script · Breakout · 1m
- Bollinger Bands Breakout Strategy 448080Pine Script · Breakout · 1h
- Amazing Price Breakout StrategyPine Script · Breakout · 1h
- Cross Timeframe SuperTrend Breakout StrategyPine Script · Breakout · 1h