Multi Period Momentum Driven Adaptive Volatility Filtered Strategy
This strategy is an advanced trading system based on multi-period momentum indicators and volatility filtering. It constructs a comprehensive momentum scoring system by calculating price momentum across four time…
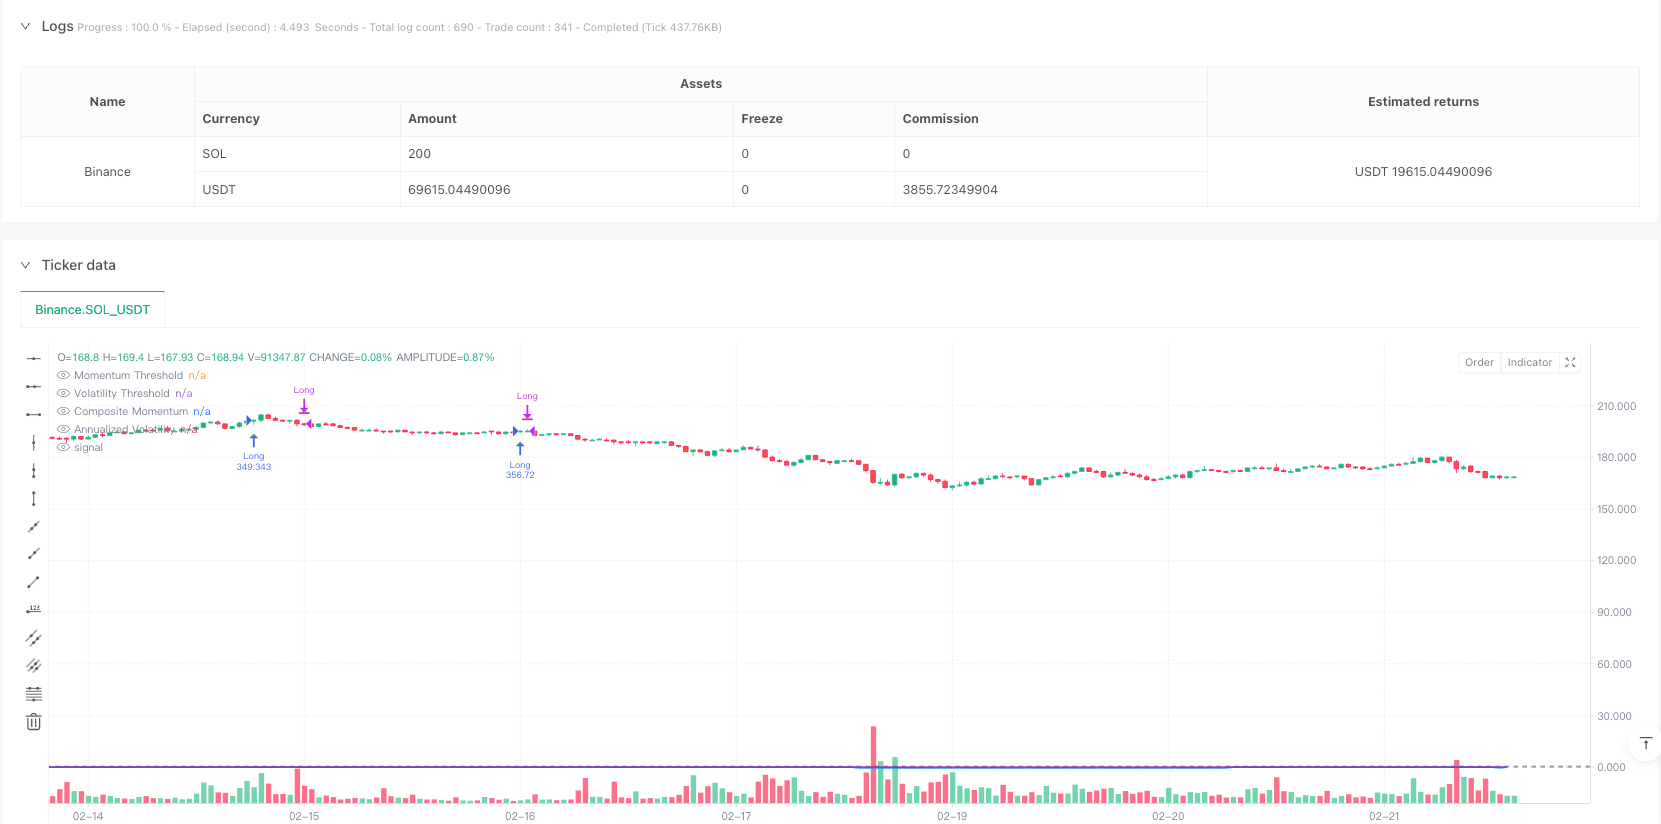
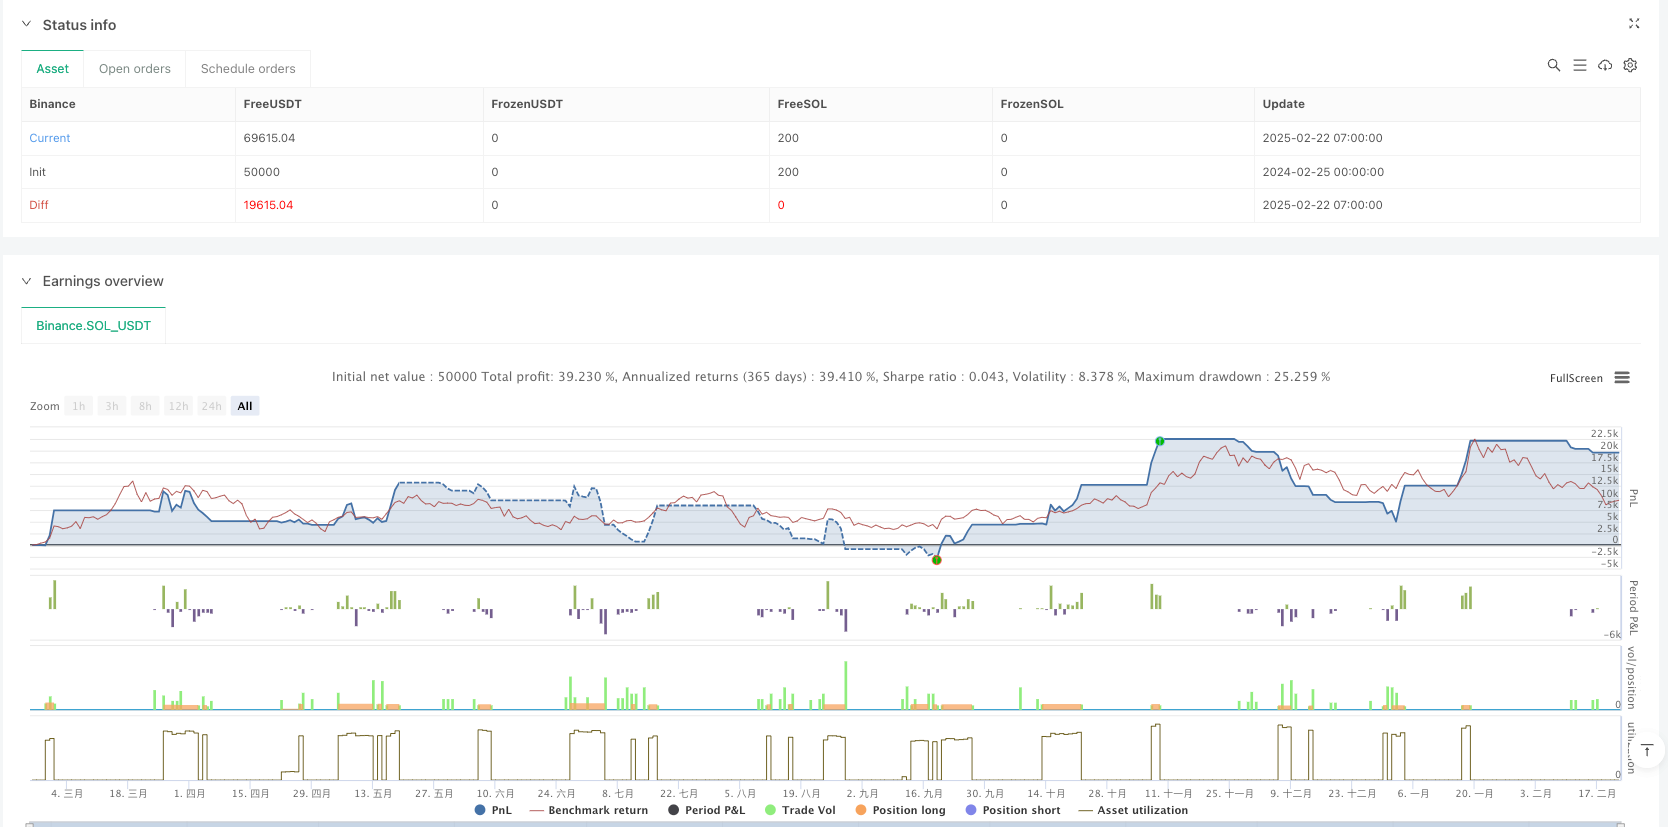
Overview
This strategy is an advanced trading system based on multi-period momentum indicators and volatility filtering. It constructs a comprehensive momentum scoring system by calculating price momentum across four time periods: 3-month, 6-month, 9-month, and 12-month. Additionally, the strategy incorporates an annualized volatility filtering mechanism to control trading risk by setting volatility thresholds. The strategy focuses on capturing trading opportunities with sustained upward trends and relatively stable volatility, making it a typical trend-following system.
Strategy Principles
The core logic includes several key elements:
- Momentum Calculation: Uses (current_price/historical_price-1) method to calculate momentum indicators for four time periods.
- Volatility Filtering: Calculates the standard deviation of daily returns and annualizes it, comparing it with a preset threshold (0.5) to filter high volatility periods.
- Signal Generation: Generates long signals when the composite momentum indicator turns positive from negative and volatility is below the threshold; exits when momentum turns negative.
- Risk Management: Employs 1% stop-loss and 50% take-profit levels to control single-trade risk.
Strategy Advantages
- Multi-dimensional Momentum Analysis: Provides a more comprehensive assessment of price trend strength and persistence by considering momentum across multiple time periods.
- Adaptive Volatility Filtering: Effectively avoids false signals during high volatility periods through dynamic volatility calculation and filtering.
- Comprehensive Risk Control: Implements stop-loss and take-profit thresholds for effective single-trade risk control.
- Systematic Decision-making: Fully systematized strategy that eliminates subjective judgment interference.
Strategy Risks
- Trend Reversal Risk: May incur significant losses during sudden trend reversals.
- Parameter Sensitivity: Strategy performance is sensitive to momentum period and volatility threshold parameter settings.
- Market Environment Dependency: May generate frequent false signals in ranging markets.
- Slippage Impact: May face significant transaction costs during periods of insufficient market liquidity.
Strategy Optimization Directions
- Dynamic Parameter Optimization: Introduce adaptive parameter adjustment mechanisms to dynamically adjust momentum periods and volatility thresholds based on market conditions.
- Market State Classification: Add market state identification modules to employ different parameter settings under different market environments.
- Signal Confirmation Mechanism: Incorporate additional technical indicators to confirm trading signals and improve strategy stability.
- Capital Management Optimization: Dynamically adjust position sizes based on signal strength to achieve more efficient capital utilization.
Summary
This strategy constructs a complete trend-following trading system by combining multi-period momentum analysis and volatility filtering. Its core advantages lie in its systematic decision-making process and comprehensive risk control mechanisms. While inherent risks exist, there is significant room for improvement through the proposed optimization directions. Overall, this is a well-designed and logically rigorous trading strategy suitable for application in low-volatility trend markets.
Source Pine Script
/*backtest
start: 2024-02-25 00:00:00
end: 2025-02-22 08:00:00
period: 1h
basePeriod: 1h
exchanges: [{"eid":"Binance","currency":"SOL_USDT"}]
*/

//@version=5
strategy("GOATED Long-Only", overlay=true, initial_capital=1000, default_qty_type=strategy.percent_of_equity, default_qty_value=100)

// Strategy parameters
var float VOLATILITY_THRESHOLD = input.float(0.5, "Volatility Threshold", minval=0.1, maxval=1.0, step=0.1)
var int TRADING_DAYS_PER_YEAR = 252
var float SQRT_TRADING_DAYS = math.sqrt(TRADING_DAYS_PER_YEAR)

// Trade parameters
var float STOP_LOSS = input.float(0.05, "Stop Loss %", minval=0.01, maxval=0.20, step=0.01)
var float TAKE_PROFIT = input.float(0.15, "Take Profit %", minval=0.05, maxval=0.50, step=0.01)

// Momentum periods (in trading days)
var int MOMENTUM_3M = input.int(63, "3-Month Momentum Period", minval=20)
var int MOMENTUM_6M = input.int(126, "6-Month Momentum Period", minval=40)
var int MOMENTUM_9M = input.int(189, "9-Month Momentum Period", minval=60)
var int MOMENTUM_12M = input.int(252, "12-Month Momentum Period", minval=80)

// Function to calculate momentum for a specific period
momentum(period) =>
    close / close[period] - 1

// Function to calculate annualized volatility
calcVolatility() =>
    returns = ta.change(close) / close[1]
    stdDev = ta.stdev(returns, TRADING_DAYS_PER_YEAR)
    annualizedVol = stdDev * SQRT_TRADING_DAYS
    annualizedVol

// Calculate individual momentum scores
float mom3m = momentum(MOMENTUM_3M)
float mom6m = momentum(MOMENTUM_6M)
float mom9m = momentum(MOMENTUM_9M)
float mom12m = momentum(MOMENTUM_12M)

// Calculate average momentum score
var int validPeriods = 0
var float totalMomentum = 0.0

validPeriods := 0
totalMomentum := 0.0

if not na(mom3m)
    validPeriods := validPeriods + 1
    totalMomentum := totalMomentum + mom3m

if not na(mom6m)
    validPeriods := validPeriods + 1
    totalMomentum := totalMomentum + mom6m

if not na(mom9m)
    validPeriods := validPeriods + 1
    totalMomentum := totalMomentum + mom9m

if not na(mom12m)
    validPeriods := validPeriods + 1
    totalMomentum := totalMomentum + mom12m

float compositeMomentum = validPeriods > 0 ? totalMomentum / validPeriods : na

// Calculate volatility
float annualizedVolatility = calcVolatility()

// Generate trading signals
var float MOMENTUM_THRESHOLD = input.float(0.0, "Momentum Threshold", minval=-1.0, maxval=1.0, step=0.01)
bool validVolatility = not na(annualizedVolatility) and annualizedVolatility <= VOLATILITY_THRESHOLD
bool validMomentum = not na(compositeMomentum) and compositeMomentum > MOMENTUM_THRESHOLD

// Store previous momentum state
bool prevValidMomentum = nz(validMomentum[1])

// Entry and exit conditions
bool longCondition = validVolatility and validMomentum and not prevValidMomentum
bool exitLongCondition = validVolatility and (not validMomentum) and prevValidMomentum

// Plot signals
plotshape(longCondition, title="Long Entry", location=location.belowbar, color=color.green, style=shape.triangleup, size=size.small)
plotshape(exitLongCondition, title="Long Exit", location=location.abovebar, color=color.red, style=shape.triangledown, size=size.small)

// Plot momentum and volatility indicators
plot(compositeMomentum, "Composite Momentum", color=color.blue, linewidth=2)
hline(MOMENTUM_THRESHOLD, "Momentum Threshold", color=color.gray, linestyle=hline.style_dashed)

plot(annualizedVolatility, "Annualized Volatility", color=color.purple, linewidth=1)
hline(VOLATILITY_THRESHOLD, "Volatility Threshold", color=color.gray, linestyle=hline.style_dashed)

// Strategy execution - Long positions
if (longCondition)
    strategy.entry("Long", strategy.long)

if (strategy.position_size > 0)
    float longStopLoss = strategy.position_avg_price * (1 - STOP_LOSS)
    float longTakeProfit = strategy.position_avg_price * (1 + TAKE_PROFIT)
    strategy.exit("Exit Long", "Long", stop=longStopLoss, limit=longTakeProfit)
    if (exitLongCondition)
strategy.close("Long", comment="Signal Exit")Published by ianzeng123 on the FMZ strategy square · last modified 2025-02-24. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Multi-Period-Momentum-Driven-Adaptive-Volatility-Filtered-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX Momentum Trend StrategyPine Script · Momentum · 10m
- Adaptive Trend Following Strategy Based on Momentum OscillatorPine Script · Momentum · 1d
- Advanced Composite Moving Average and Market Momentum Trend Capture StrategyPine Script · Momentum
- Advanced Multi Indicator Trend Following and Momentum Quantitative Trading StrategyPine Script · Momentum · 1h
- Bollinger Bands Momentum Trend Following Quantitative StrategyPine Script · Momentum · 1d
- Confirmed SMA Crossover Momentum StrategyPine Script · Momentum · 1d