Strategy vault / Trend following
Multi Smoothed Moving Average Dynamic Crossover Trend Following Strategy with Multiple Confirmations
This strategy is a trend-following system based on multiple smoothed moving averages, using triple smoothing to filter market noise while combining RSI momentum indicator, ATR volatility indicator, and 200-period EMA…
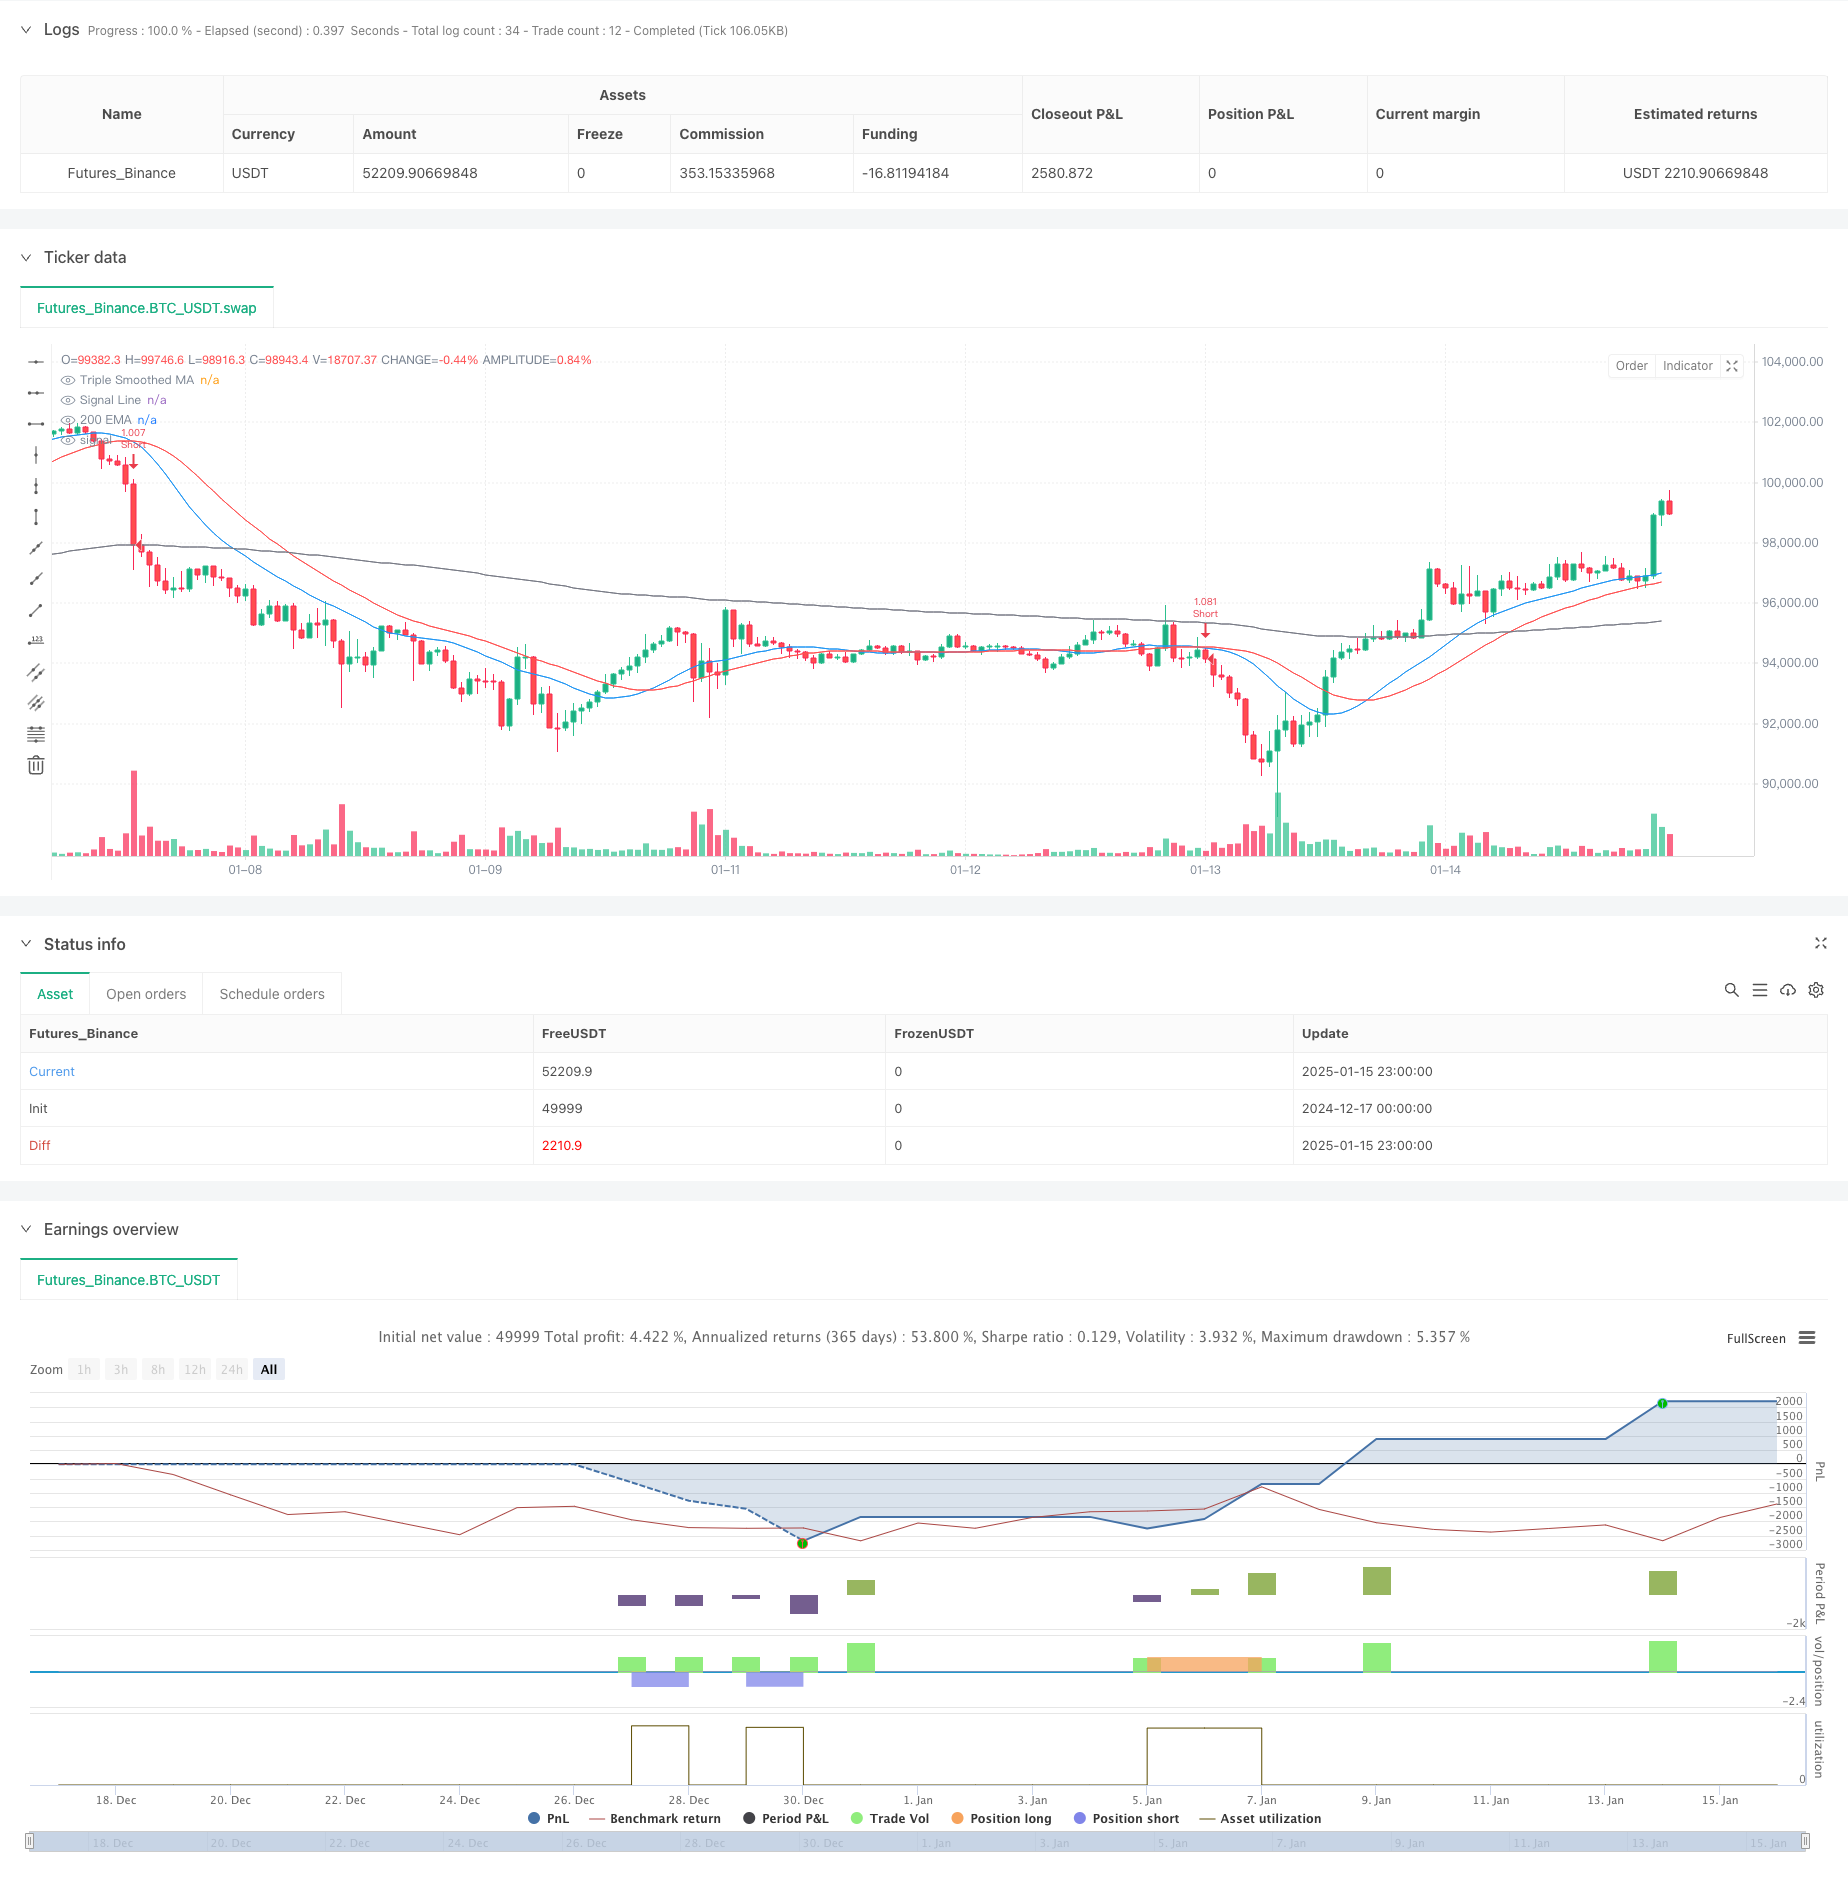
Overview
This strategy is a trend-following system based on multiple smoothed moving averages, using triple smoothing to filter market noise while combining RSI momentum indicator, ATR volatility indicator, and 200-period EMA trend filter to confirm trading signals. The strategy operates on a 1-hour timeframe, which effectively balances trading frequency and trend reliability while aligning with institutional trading behavior.
Strategy Principles
The core of the strategy is to construct a main trend line through triple smoothing of prices and generate trading signals through crossovers with a shorter-period signal line. Trade signals must simultaneously meet the following conditions:
- Price position relative to 200EMA confirms main trend direction
- RSI indicator position confirms momentum
- ATR indicator confirms sufficient volatility
- Signal line crossover with triple-smoothed MA confirms specific entry points Stop-loss uses ATR-based dynamic stops, while take-profit is set at 2x ATR to ensure favorable risk-reward ratios.
Strategy Advantages
- Triple smoothing significantly reduces false signals and improves trend judgment reliability
- Multiple confirmation mechanisms ensure trade direction aligns with major trends
- Dynamic stop-loss and take-profit settings adapt to different market volatility environments
- Strategy operation on 1-hour timeframe effectively avoids lower timeframe oscillations
- Non-repainting feature guarantees backtest result reliability
Strategy Risks
- May produce consecutive small losses in ranging markets
- Multiple confirmation mechanisms might cause missed trading opportunities
- Signal lag may affect entry point optimization
- Requires sufficient volatility to generate effective signals
- Dynamic stops may not be timely enough in extreme market conditions
Strategy Optimization Directions
- Can add volume indicators as auxiliary confirmation
- Consider introducing adaptive parameter optimization mechanisms
- Can add quantitative trend strength assessment
- Optimize stop-loss and take-profit multiplier settings
- Consider adding oscillator indicators to improve ranging market performance
Summary
This is a trend-following strategy with complete structure and rigorous logic. Through multiple smoothing processing and multiple confirmation mechanisms, it effectively improves the reliability of trading signals. The dynamic risk management mechanism provides good adaptability. Although there is some lag, the strategy still has significant room for improvement through parameter optimization and additional auxiliary indicators.
Source Pine Script
/*backtest
start: 2024-12-17 00:00:00
end: 2025-01-16 00:00:00
period: 1h
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT","balance":49999}]
*/

//@version=6
strategy("Optimized Triple Smoothed MA Crossover Strategy", overlay=true, default_qty_type=strategy.percent_of_equity, default_qty_value=200)

// === Input Settings ===
slength = input.int(7, "Main Smoothing Length", group="Moving Average Settings")
siglen = input.int(12, "Signal Length", group="Moving Average Settings")
src = input.source(close, "Data Source", group="Moving Average Settings")
mat = input.string("EMA", "Triple Smoothed MA Type", ["EMA", "SMA", "RMA", "WMA"], group="Moving Average Settings")
mat1 = input.string("EMA", "Signal Type", ["EMA", "SMA", "RMA", "WMA"], group="Moving Average Settings")

// === Trend Confirmation (Higher Timeframe Filter) ===
useTrendFilter = input.bool(true, "Enable Trend Filter (200 EMA)", group="Trend Confirmation")
trendMA = ta.ema(close, 200)

// === Momentum Filter (RSI Confirmation) ===
useRSIFilter = input.bool(true, "Enable RSI Confirmation", group="Momentum Confirmation")
rsi = ta.rsi(close, 14)
rsiThreshold = input.int(50, "RSI Threshold", group="Momentum Confirmation")

// === Volatility Filter (ATR) ===
useATRFilter = input.bool(true, "Enable ATR Filter", group="Volatility Filtering")
atr = ta.atr(14)
atrMa = ta.sma(atr, 14)

// === Risk Management (ATR-Based Stop Loss) ===
useAdaptiveSL = input.bool(true, "Use ATR-Based Stop Loss", group="Risk Management")
atrMultiplier = input.float(1.5, "ATR Multiplier for SL", minval=0.5, maxval=5, group="Risk Management")
takeProfitMultiplier = input.float(2, "Take Profit Multiplier", group="Risk Management")

// === Moving Average Function ===
ma(source, length, MAtype) =>
    switch MAtype
        "SMA" => ta.sma(source, length)
        "EMA" => ta.ema(source, length)
        "RMA" => ta.rma(source, length)
        "WMA" => ta.wma(source, length)

// === Triple Smoothed Calculation ===
tripleSmoothedMA = ma(ma(ma(src, slength, mat), slength, mat), slength, mat)
signalLine = ma(tripleSmoothedMA, siglen, mat1)

// === Crossovers (Entry Signals) ===
bullishCrossover = ta.crossunder(signalLine, tripleSmoothedMA)
bearishCrossover = ta.crossover(signalLine, tripleSmoothedMA)

// === Additional Confirmation Conditions ===
trendLongCondition = not useTrendFilter or (close > trendMA)  // Only long if price is above 200 EMA
trendShortCondition = not useTrendFilter or (close < trendMA) // Only short if price is below 200 EMA

rsiLongCondition = not useRSIFilter or (rsi > rsiThreshold)  // RSI above 50 for longs
rsiShortCondition = not useRSIFilter or (rsi < rsiThreshold) // RSI below 50 for shorts

atrCondition = not useATRFilter or (atr > atrMa)  // ATR must be above its MA for volatility confirmation

// === Final Trade Entry Conditions ===
longCondition = bullishCrossover and trendLongCondition and rsiLongCondition and atrCondition
shortCondition = bearishCrossover and trendShortCondition and rsiShortCondition and atrCondition

// === ATR-Based Stop Loss & Take Profit ===
longSL = close - (atr * atrMultiplier)
longTP = close + (atr * takeProfitMultiplier)

shortSL = close + (atr * atrMultiplier)
shortTP = close - (atr * takeProfitMultiplier)

// === Strategy Execution ===
if longCondition
    strategy.entry("Long", strategy.long)
    strategy.exit("Long Exit", from_entry="Long", stop=longSL, limit=longTP)

if shortCondition
    strategy.entry("Short", strategy.short)
    strategy.exit("Short Exit", from_entry="Short", stop=shortSL, limit=shortTP)

// === Plots ===
plot(tripleSmoothedMA, title="Triple Smoothed MA", color=color.blue)
plot(signalLine, title="Signal Line", color=color.red)
plot(trendMA, title="200 EMA", color=color.gray)

// === Alerts ===
alertcondition(longCondition, title="Bullish Signal", message="Triple Smoothed MA Bullish Crossover Confirmed")
alertcondition(shortCondition, title="Bearish Signal", message="Triple Smoothed MA Bearish Crossover Confirmed")
Published by ChaoZhang on the FMZ strategy square · last modified 2025-01-17. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Multi-Smoothed-Moving-Average-Dynamic-Crossover-Trend-Following-Strategy-with-Multiple-Confirmations.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dual Mode Adaptive Trend Trading Strategy EMA Crossover with ATR Volatility Based Risk Management SystemPine Script · Trend following · 1d
- Dynamic Dual EMA Crossover Strategy with Adaptive Profit Loss ControlPine Script · Trend following · 1d
- Dynamic Signal Line Trend Following and Volatility Filtering StrategyPine Script · Trend following · 1h
- EMA Cross Trend Following Strategy with SMA Stop Loss and Re Entry MechanismPine Script · Trend following · 1h