Multi Strategy Adaptive Trend Following and Breakout Trading System
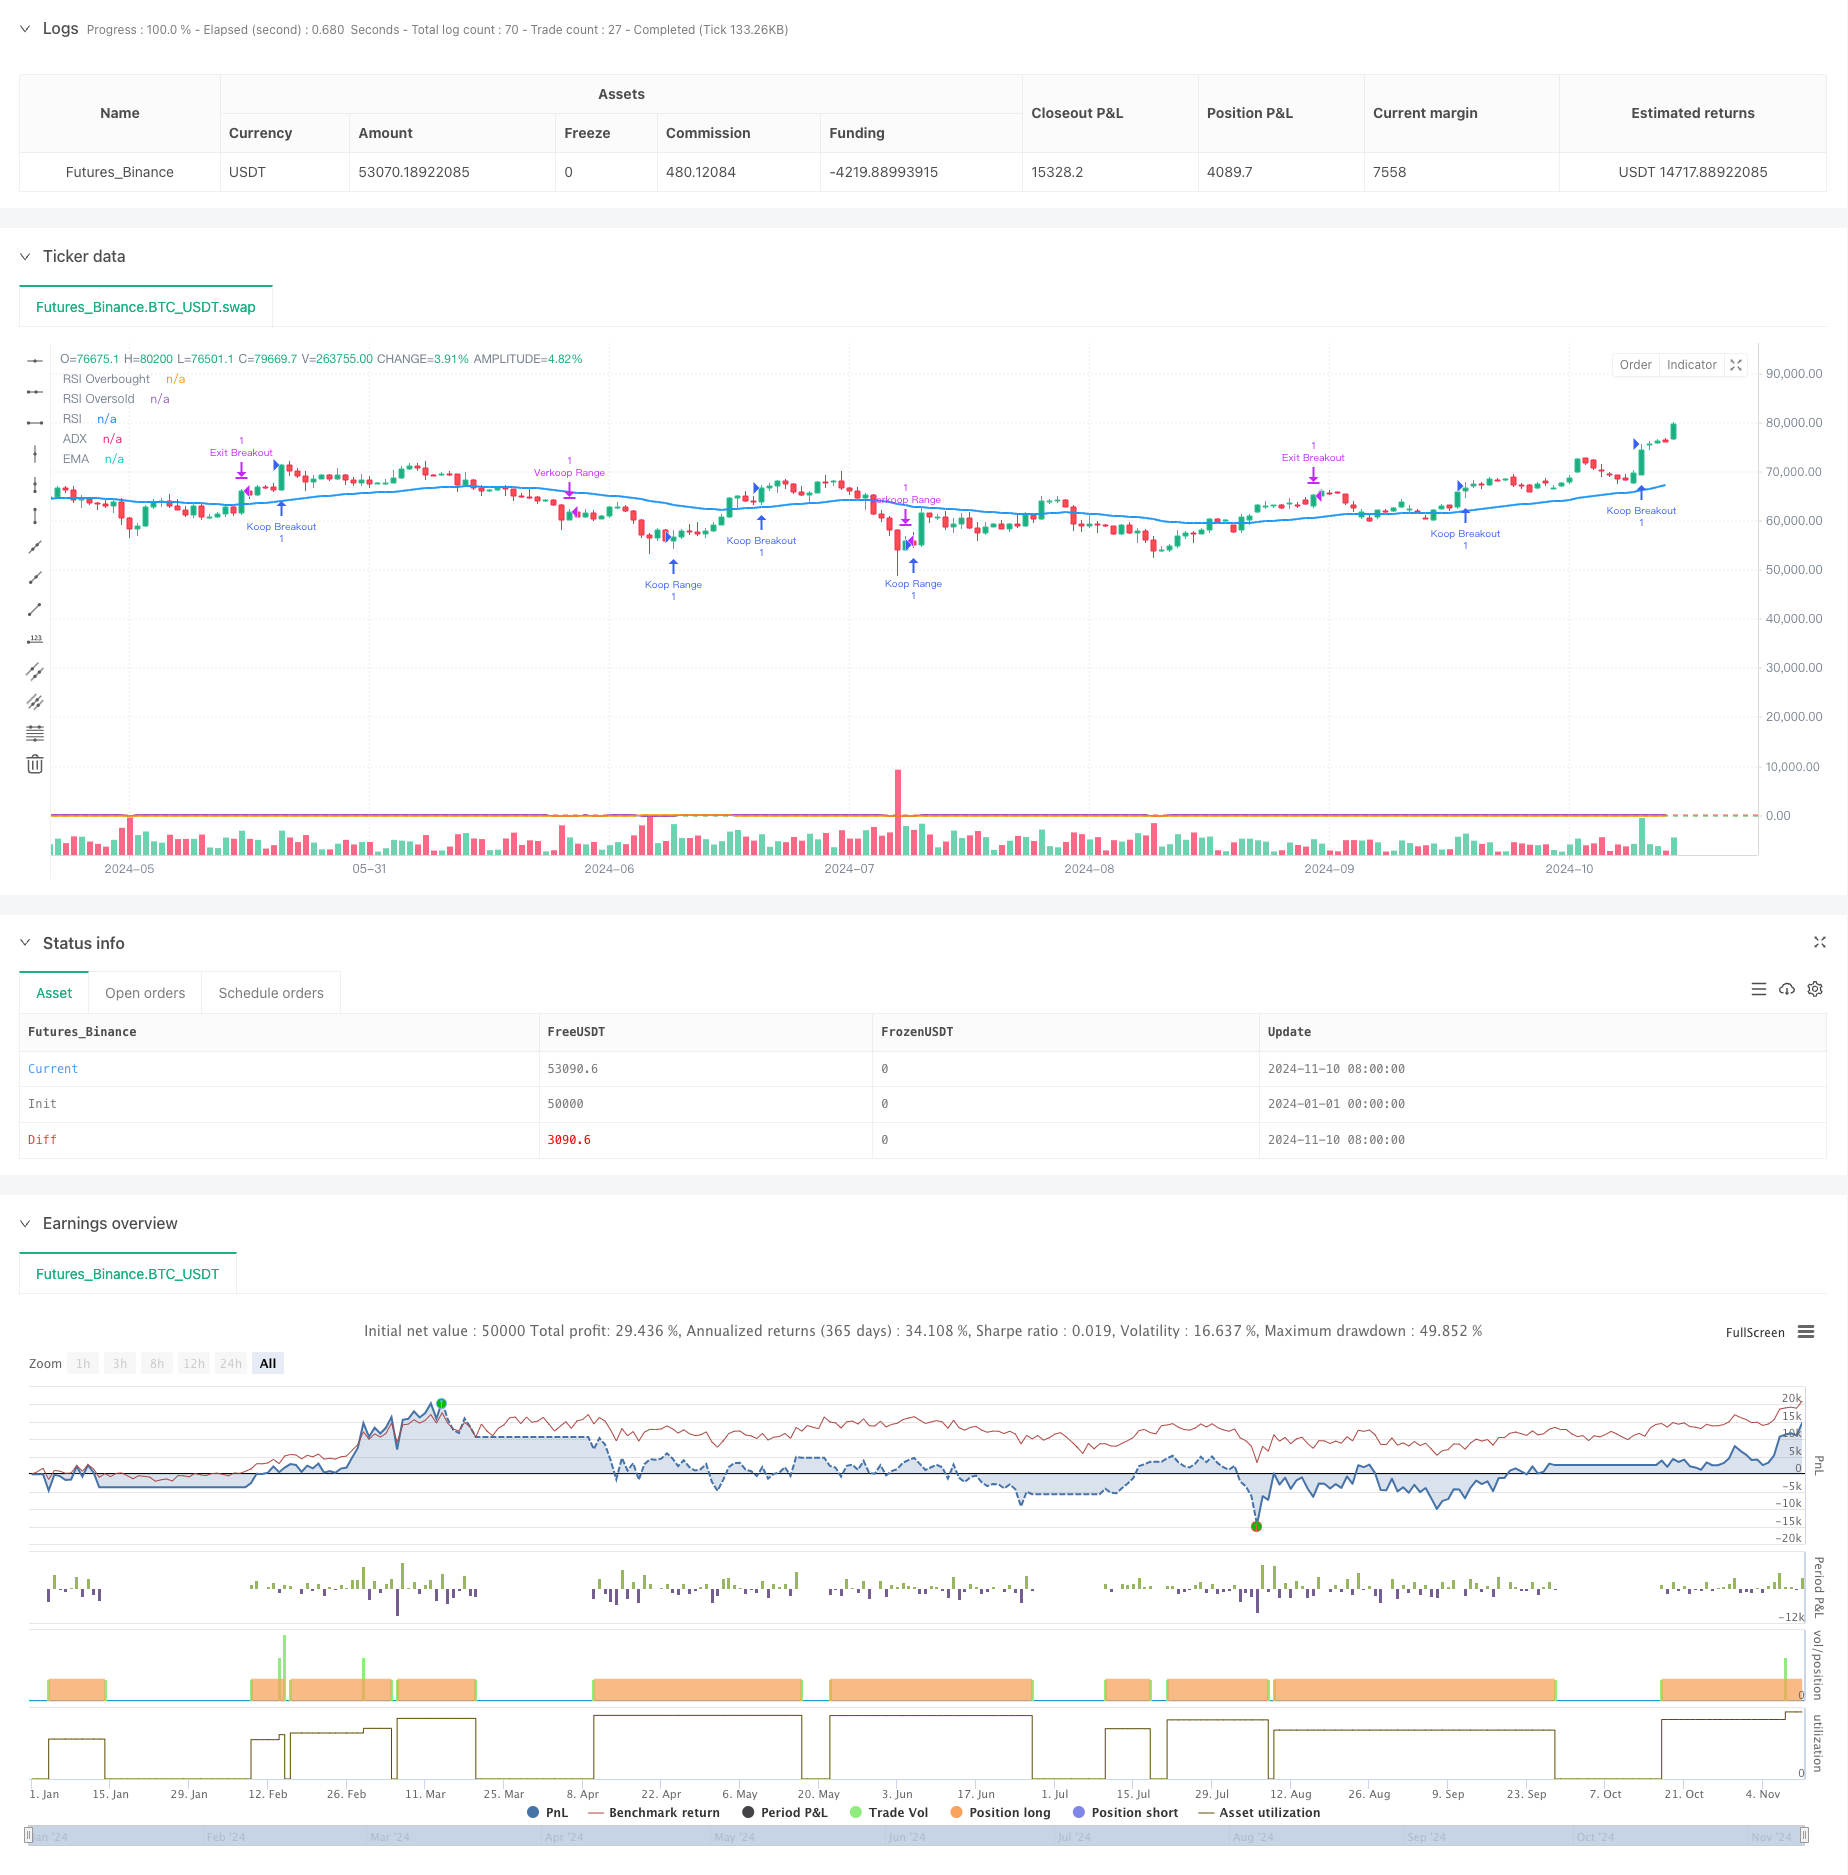
This strategy is an adaptive trading system that integrates multiple trading methods, combining trend following, range trading, and breakout trading strategies to adapt to different market conditions. The system uses…
Overview
This strategy is an adaptive trading system that integrates multiple trading methods, combining trend following, range trading, and breakout trading strategies to adapt to different market conditions. The system uses technical indicators such as EMA, RSI, and OBV for market state determination, combines ADX indicator for trend strength confirmation, and implements ATR-based dynamic stop-loss for risk control. The strategy's uniqueness lies in allowing users to freely select which trading strategies to enable and precisely control risk for each trade through money management parameters.
Strategy Principles
The strategy contains three main trading modules:
- Trend Trading Module: Uses EMA and ADX indicators to determine trend status, confirming trends when price is above EMA and ADX is above 25, looking for long opportunities in RSI oversold zones.
- Range Trading Module: Operates in non-trending markets, using RSI indicator for reversal trades in overbought and oversold zones.
- Breakout Trading Module: Combines price breakouts with OBV indicator to confirm volume support, capturing breakout opportunities with high volume confirmation.
Each module employs ATR-based dynamic stop-loss and sets profit targets based on user-defined risk-reward ratios. The system uses a volume filter to ensure trades occur in adequately liquid conditions.
Strategy Advantages
- High Adaptability: Multi-strategy combination adapts to different market environments
- Comprehensive Risk Control: Uses ATR dynamic stop-loss with customizable risk-reward ratios
- High Flexibility: Users can selectively enable different strategies based on market characteristics
- Strict Trade Confirmation: Integrates multiple confirmations from price, volume, and technical indicators
- Scientific Money Management: Precise control of risk percentage for each trade
Strategy Risks
- Parameter Optimization Risk: Multiple adjustable parameters may lead to over-optimization
- Market Environment Assessment Risk: Different strategies may generate conflicting signals
- Liquidity Risk: Potential slippage in low liquidity environments
- Systematic Risk: Market events may cause stop-loss failure
Recommended risk control measures:
- Conduct thorough historical data backtesting
- Adopt conservative money management ratios
- Regular parameter review and adjustment
- Set maximum position holding time limits
Strategy Optimization Directions
Enhance Market Volatility Adaptation:
- Dynamically adjust entry conditions based on volatility
- Increase signal confirmation thresholds in high volatility environments
Improve Strategy Switching Mechanism:
- Establish market environment scoring system
- Implement dynamic strategy weight adjustment
Strengthen Money Management System:
- Introduce dynamic position sizing
- Adjust risk parameters based on historical performance
Optimize Signal Filtering:
- Add trend strength confirmation indicators
- Enhance volume analysis methods
Summary
This strategy achieves adaptive trading across different market environments through multi-strategy combination and strict risk control systems. The modular design allows flexible configuration, while comprehensive money management mechanisms ensure trading safety. Through continuous optimization and improvement, the strategy shows promise for stable performance across various market conditions. For enhanced robustness in live trading, it is recommended to adopt conservative money management approaches and regularly evaluate and adjust strategy parameters.
Source Pine Script
/*backtest
start: 2024-01-01 00:00:00
end: 2024-11-11 00:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Ceulemans Trading Bot met ADX, Trendfilter en Selecteerbare Strategieën", overlay=true)

// Parameters voor indicatoren
emaLength = input.int(50, title="EMA Lengte")
rsiLength = input.int(14, title="RSI Lengte")
obvLength = input.int(20, title="OBV Lengte")
rsiOverbought = input.int(65, title="RSI Overbought")
rsiOversold = input.int(35, title="RSI Oversold")
atrLength = input.int(14, title="ATR Lengte")
adxLength = input.int(14, title="ADX Lengte")
adxSmoothing = input.int(14, title="ADX Smoothing")  // Voeg de smoothing parameter toe

// Money Management Parameters
capitalRisk = input.float(1.0, title="Percentage van kapitaal per trade", step=0.1)
riskReward = input.float(3.0, title="Risk/Reward ratio", step=0.1)
stopLossMultiplier = input.float(1.2, title="ATR Stop-Loss Multiplier", step=0.1)

// Strategieën selecteren (aan/uit schakelaars)
useTrendTrading = input.bool(true, title="Gebruik Trend Trading")
useRangeTrading = input.bool(true, title="Gebruik Range Trading")
useBreakoutTrading = input.bool(true, title="Gebruik Breakout Trading")

// Berekening indicatoren
ema = ta.ema(close, emaLength)
rsi = ta.rsi(close, rsiLength)
obv = ta.cum(ta.change(close) * volume)
atr = ta.atr(atrLength)
[diplus, diminus, adx] = ta.dmi(adxLength, adxSmoothing)  // ADX berekening met smoothing
avgVolume = ta.sma(volume, obvLength)

// Huidige marktsituatie analyseren
isTrending = close > ema and adx > 25  // Trend is sterk als ADX boven 25 is
isOversold = rsi < rsiOversold
isOverbought = rsi > rsiOverbought
isBreakout = close > ta.highest(close[1], obvLength) and obv > ta.cum(ta.change(close[obvLength]) * volume)
isRange = not isTrending and (close < ta.highest(close, obvLength) and close > ta.lowest(close, obvLength))
volumeFilter = volume > avgVolume

// Strategie logica

// 1. Trend Trading met tight stop-loss en ADX filter
if (useTrendTrading and isTrending and isOversold and volumeFilter)
    strategy.entry("Koop Trend", strategy.long)
    strategy.exit("Exit Trend", stop=strategy.position_avg_price - stopLossMultiplier * atr, limit=strategy.position_avg_price + riskReward * stopLossMultiplier * atr)

// 2. Range Trading
if (useRangeTrading and isRange and rsi < rsiOversold and volumeFilter)
    strategy.entry("Koop Range", strategy.long)
    strategy.exit("Verkoop Range", stop=strategy.position_avg_price - stopLossMultiplier * atr, limit=strategy.position_avg_price + riskReward * stopLossMultiplier * atr)

if (useRangeTrading and isRange and rsi > rsiOverbought and volumeFilter)
    strategy.entry("Short Range", strategy.short)
    strategy.exit("Exit Short Range", stop=strategy.position_avg_price + stopLossMultiplier * atr, limit=strategy.position_avg_price - riskReward * stopLossMultiplier * atr)

// 3. Breakout Trading met volume
if (useBreakoutTrading and isBreakout and volumeFilter)
    strategy.entry("Koop Breakout", strategy.long)
    strategy.exit("Exit Breakout", stop=strategy.position_avg_price - stopLossMultiplier * atr, limit=strategy.position_avg_price + riskReward * stopLossMultiplier * atr)

// Indicatoren plotten
plot(ema, title="EMA", color=color.blue, linewidth=2)
hline(rsiOverbought, "RSI Overbought", color=color.red)
hline(rsiOversold, "RSI Oversold", color=color.green)
plot(rsi, title="RSI", color=color.purple)
plot(adx, title="ADX", color=color.orange)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-11-12. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Multi-Strategy-Adaptive-Trend-Following-and-Breakout-Trading-System.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Multi Indicator Trend Following and Volatility Breakout StrategyPine Script · Breakout · 2h
- Multi Filter Trend Breakthrough Smart Moving Average Trading StrategyPine Script · Breakout · 1h
- Multi Dimensional Technical Indicator Fusion Trend Breakthrough StrategyPine Script · Breakout · 1h
- Multi Timeframe Trend Confirmed Quantitative Breakout Trading StrategyPine Script · Breakout · 1d
- Momentum Breakout Trading Strategy 440964Pine Script · Breakout · 5m
- Moving Average Crossover and Upper Rail Breakthrough Impulse StrategyPine Script · Breakout · 1m