Strategy vault / Trend following
Multi Timeframe RSI Moving Average Crossover Strategy
The Multi-Timeframe RSI Moving Average Crossover Strategy is a trend following strategy across multiple timeframes. It uses RSI indicators on multiple timeframes and takes a weighted moving average of each…
Overview
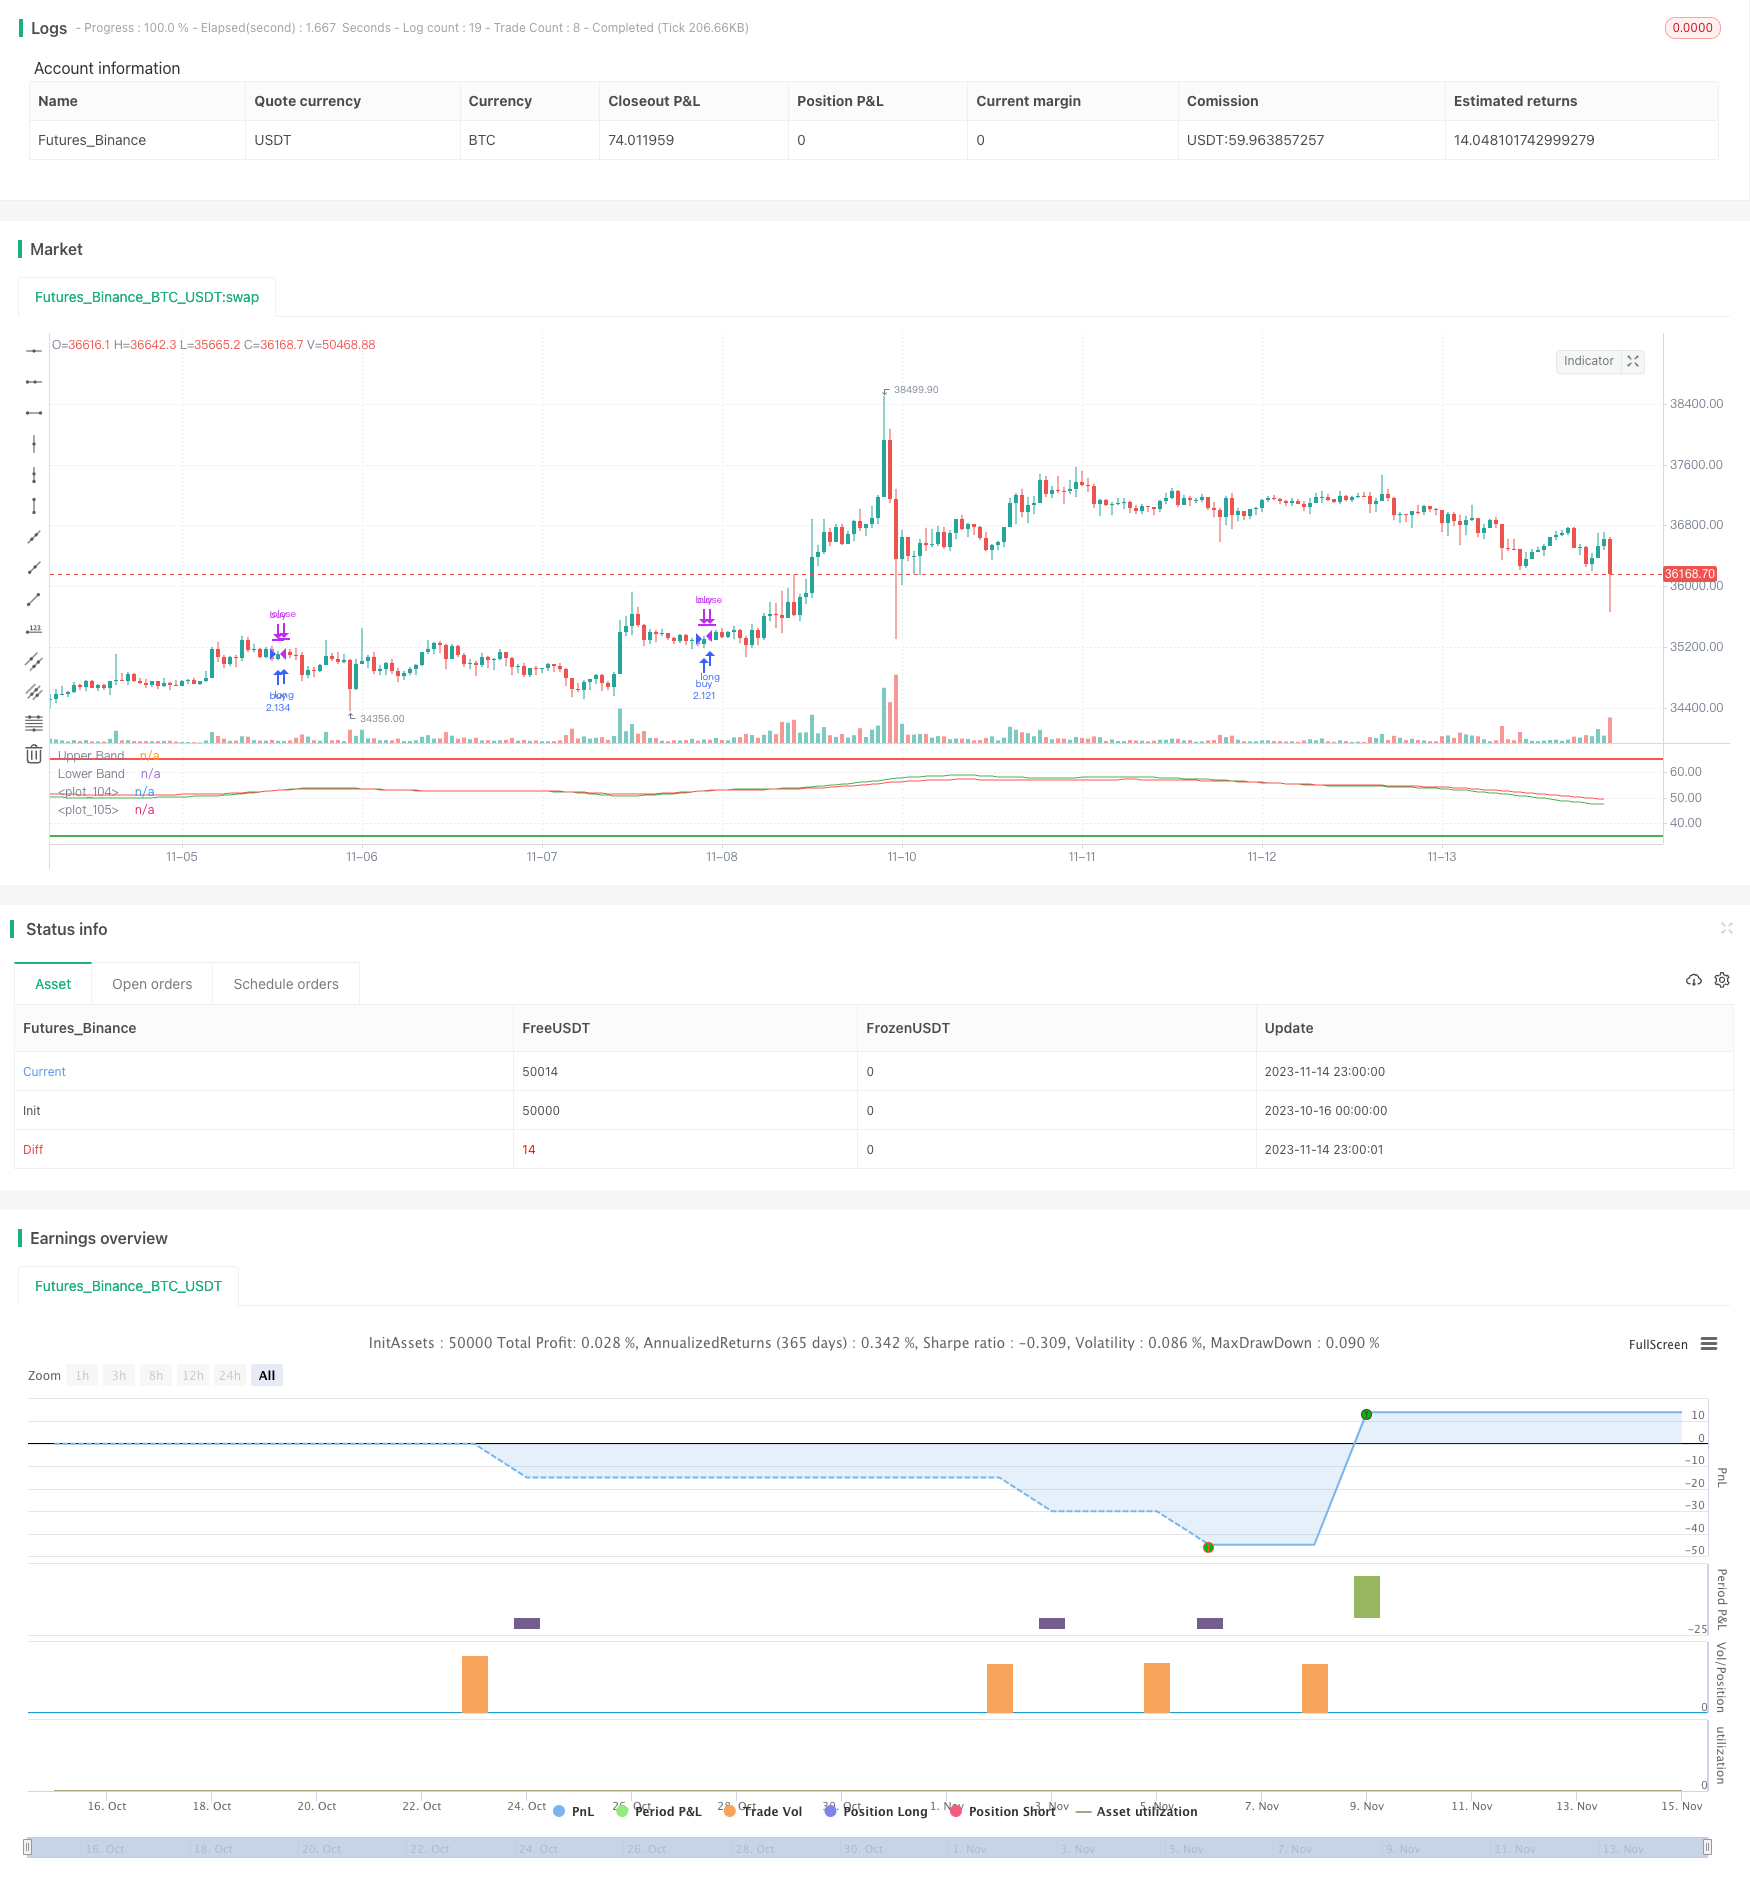
The Multi-Timeframe RSI Moving Average Crossover Strategy is a trend following strategy across multiple timeframes. It uses RSI indicators on multiple timeframes and takes a weighted moving average of each timeframe's RSI. The final signals are generated by combining all RSI moving averages into two comprehensive indicators and trading the crossover signals, which is a typical dual moving average crossover system.
Principles
This strategy first calculates RSI indicators on multiple timeframes (1-min, 5-min, 15-min, etc). Then it takes 15-period VMA (weighted moving average) of the RSI for each timeframe to get the RSI moving average lines.
After that, all the RSI moving averages from different timeframes are combined equally into two signals - fast line and slow line. The fast line is a 100-period EMA and the slow line is a 150-period EMA.
When the fast line crosses above the slow line, a buy signal is generated. When the fast line crosses below the slow line, a sell signal is generated. By combining multi-timeframe RSI in this way, the crossover signals can effectively track trends while filtering out short-term market noise.
Advantages
Combining multiple timeframes can smooth price curves and avoid false breakouts effectively.
RSI indicates overbought/oversold levels, avoiding chasing new highs/lows.
Dual moving averages have better holding effect than a single moving average system.
Using VMA instead of SMA reduces the impact of short-term fluctuations.
Risks
Multi-timeframe strategies require extensive parameter tuning, improper settings may cause missing good entries or late entries.
Moving averages have poor curve fitting, underperform at trend turning points.
RSI divergence happens frequently, reversal signals should be watched.
Solutions: Optimize timeframe parameters; Combine with other indicators like MACD to determine trends; Watch out for RSI divergence signals.
Optimization Directions
Optimize the number of timeframes and parameter settings to better capture trends.
Consider adding stop loss to control risks.
Combine other indicators for better decision on trends and divergences.
Test different holding period parameters for best holding effect.
Conclusion
The Multi-Timeframe RSI Moving Average Crossover Strategy generates trading signals by combining RSI indicators from multiple timeframes using a moving average system, which is a typical multi-timeframe trend following strategy. Its strength lies in effectively tracking trends and filtering out noise, but parameter tuning and risk control need attention. With further optimization, it can become a robust trend following system.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 1 | Res 01 |
| v_input_2 | 5 | Res 0 |
| v_input_3 | 15 | Res 1 |
| v_input_4 | 15 | Res 2 |
| v_input_5 | 15 | Res 3 |
| v_input_6 | 30 | Res 4 |
| v_input_7 | 45 | Res 5 |
| v_input_8 | 60 | Res 6 |
| v_input_9 | 15 | lengthRSI |
| v_input_10 | 15 | lengthMA |
| v_input_11 | 100 | lengthFMA |
| v_input_12 | 150 | lengthFMA2 |
| v_input_13 | true | Long trades 0 or 1 |
| v_input_14 | false | Short trades 0 or 1 |
| v_input_15 | true | From Month |
| v_input_16 | true | From Day |
| v_input_17 | 2020 | From Year |
| v_input_18 | true | Thru Month |
| v_input_19 | true | Thru Day |
| v_input_20 | 2112 | Thru Year |
| v_input_21 | true | Show Date Range |
| v_input_22 | 10 | Long Stop Loss (%) |
| v_input_23 | 10 | Short Stop Loss (%) |
Source Pine Script
/*backtest
start: 2023-10-16 00:00:00
end: 2023-11-15 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy(title="RSI multitimeframe SMA crossover", shorttitle="RSI multitimeframe strategy", default_qty_type= strategy.percent_of_equity, margin_long=50, default_qty_value=150)

res1 = input(title="Res 01", type=input.resolution, defval="1")
res2 = input(title="Res 0", type=input.resolution, defval="5")
res3 = input(title="Res 1", type=input.resolution, defval="15")
res4 = input(title="Res 2", type=input.resolution, defval="15")
res5 = input(title="Res 3", type=input.resolution, defval="15")
res6 = input(title="Res 4", type=input.resolution, defval="30")
res7 = input(title="Res 5", type=input.resolution, defval="45")
res8 = input(title="Res 6", type=input.resolution, defval="60")


lengthRSI = input(15, minval=1)
lengthMA = input(15, minval=1)
lengthFMA = input(100, minval=1)
lengthFMA2 = input(150, minval=1)
Long_yes = input(defval=1, title="Long trades 0 or 1", minval=0, maxval=1)
Short_yes = input(defval=0, title="Short trades 0 or 1", minval=0, maxval=1)
src = close

// === INPUT BACKTEST RANGE ===
fromMonth = input(defval = 1,    title = "From Month",      type = input.integer, minval = 1, maxval = 12)
fromDay   = input(defval = 1,    title = "From Day",        type = input.integer, minval = 1, maxval = 31)
fromYear  = input(defval = 2020, title = "From Year",       type = input.integer, minval = 1970)
thruMonth = input(defval = 1,    title = "Thru Month",      type = input.integer, minval = 1, maxval = 12)
thruDay   = input(defval = 1,    title = "Thru Day",        type = input.integer, minval = 1, maxval = 31)
thruYear  = input(defval = 2112, title = "Thru Year",       type = input.integer, minval = 1970)

// === INPUT SHOW PLOT ===
showDate  = input(defval = true, title = "Show Date Range", type = input.bool)

// === FUNCTION EXAMPLE ===
start     = timestamp(fromYear, fromMonth, fromDay, 00, 00)        // backtest start window
finish    = timestamp(thruYear, thruMonth, thruDay, 23, 59)        // backtest finish window
window()  => time >= start and time <= finish ? true : false       // create function "within window of time"


// stop loss
longLossPerc = input(title="Long Stop Loss (%)", type=input.float, minval=0.0, step=0.5, defval=10) *
   0.01
longStopPrice = strategy.position_avg_price * (1 - longLossPerc)

shortLossPerc = input(title="Short Stop Loss (%)", type=input.float, minval=0.0, step=0.5, defval=10) *
   0.01
shortStopPrice = strategy.position_avg_price * (1 + shortLossPerc)


rsi1 = rsi(src, lengthRSI)
MA1 = vwma(rsi1, lengthMA)


outD1 = security(syminfo.tickerid, res1, MA1)
outD2 = security(syminfo.tickerid, res2, MA1)
outD3 = security(syminfo.tickerid, res3, MA1)
outD4 = security(syminfo.tickerid, res4, MA1)
outD5 = security(syminfo.tickerid, res5, MA1)
outD6 = security(syminfo.tickerid, res6, MA1)
outD7 = security(syminfo.tickerid, res7, MA1)
outD8 = security(syminfo.tickerid, res8, MA1)


//plot_d0 = outD0
//plot_d1 = outD1
//plot_d2 = outD2
//plot_d3 = outD3
//plot_d4 = outD4
//plot_d5 = outD5
//plot_d6 = outD6

out_multi = ema(outD1+outD2+outD3+outD4+outD5+outD6+outD7+outD8, lengthFMA)
out_multi2 = ema(outD1+outD2+outD3+outD4+outD5+outD6+outD7+outD8, lengthFMA2)
//out_multi1 = outD2+outD3+outD4
//out_multi2 = outD4+outD5+outD6

//col0 = outD0 < 20 ? color.lime : outD0 > 80 ? color.red : color.blue
//col1 = outD1 < 20 ? color.lime : outD1 > 80 ? color.red : color.blue
//col2 = outD2 < 20 ? color.lime : outD2 > 80 ? color.red : color.blue
//col3 = outD3 < 20 ? color.lime : outD3 > 80 ? color.red : color.blue
//col4 = outD4 < 20 ? color.lime : outD4 > 80 ? color.red : color.blue
//col5 = outD5 < 20 ? color.lime : outD5 > 80 ? color.red : color.blue
//col6 = outD6 < 20 ? color.lime : outD6 > 80 ? color.red : color.blue


// plot(plot_d0,linewidth=2, color=col0)
// plot(plot_d1, linewidth=2, color=col1)
// plot(plot_d2,linewidth=2, color=col2)
// plot(plot_d3,linewidth=2, color=col3)
// plot(plot_d4,linewidth=2, color=col4)
// plot(plot_d5,linewidth=2, color=col5)
// plot(plot_d6,linewidth=2, color=col6)

long=(out_multi/8)
short=(out_multi2/8)

plot(long, linewidth=1, color=color.green)
plot(short, linewidth=1, color=color.red)

long1=crossover(long,short)
short1=crossunder(long,short)

h0 = hline(65, "Upper Band", color=color.red, linestyle=hline.style_solid, linewidth=2 )
h1 = hline(35, "Lower Band", color=color.green, linestyle=hline.style_solid, linewidth=2)


strategy.entry("buy", strategy.long, when=long1 and window() and Long_yes > 0)
if strategy.position_size > 0
    strategy.exit(id="XL STP", stop=longStopPrice)
strategy.close("buy",when=short1 )

strategy.entry("sell", strategy.short, when=short1 and window() and Short_yes > 0)
if strategy.position_size < 0
    strategy.exit(id="XS STP", stop=shortStopPrice)
strategy.close("buy",when=long1 )
Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-16. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Multi-Timeframe-RSI-Moving-Average-Crossover-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dynamic Dual EMA Crossover Strategy with Adaptive Profit Loss ControlPine Script · Trend following · 1d
- EMA SMA Multi Indicator Comprehensive Trend Following StrategyPine Script · Trend following · 1h
- EMA and RSI Trend Trading StrategyPine Script · Trend following · 1d
- Fixed Range Volume Profile And Anchored VWAP Trend Identification Strategy With Dynamic Stop LossPine Script · Trend following · 1h