Strategy vault / Trend following
Overlay Trend Signals Strategy
This strategy generates trading signals by calculating the Directional Movement Indexes (DMI) DI+ and DI- along with Average Directional Index (ADX) and Exponential Moving Average (EMA). It triggers a long signal…
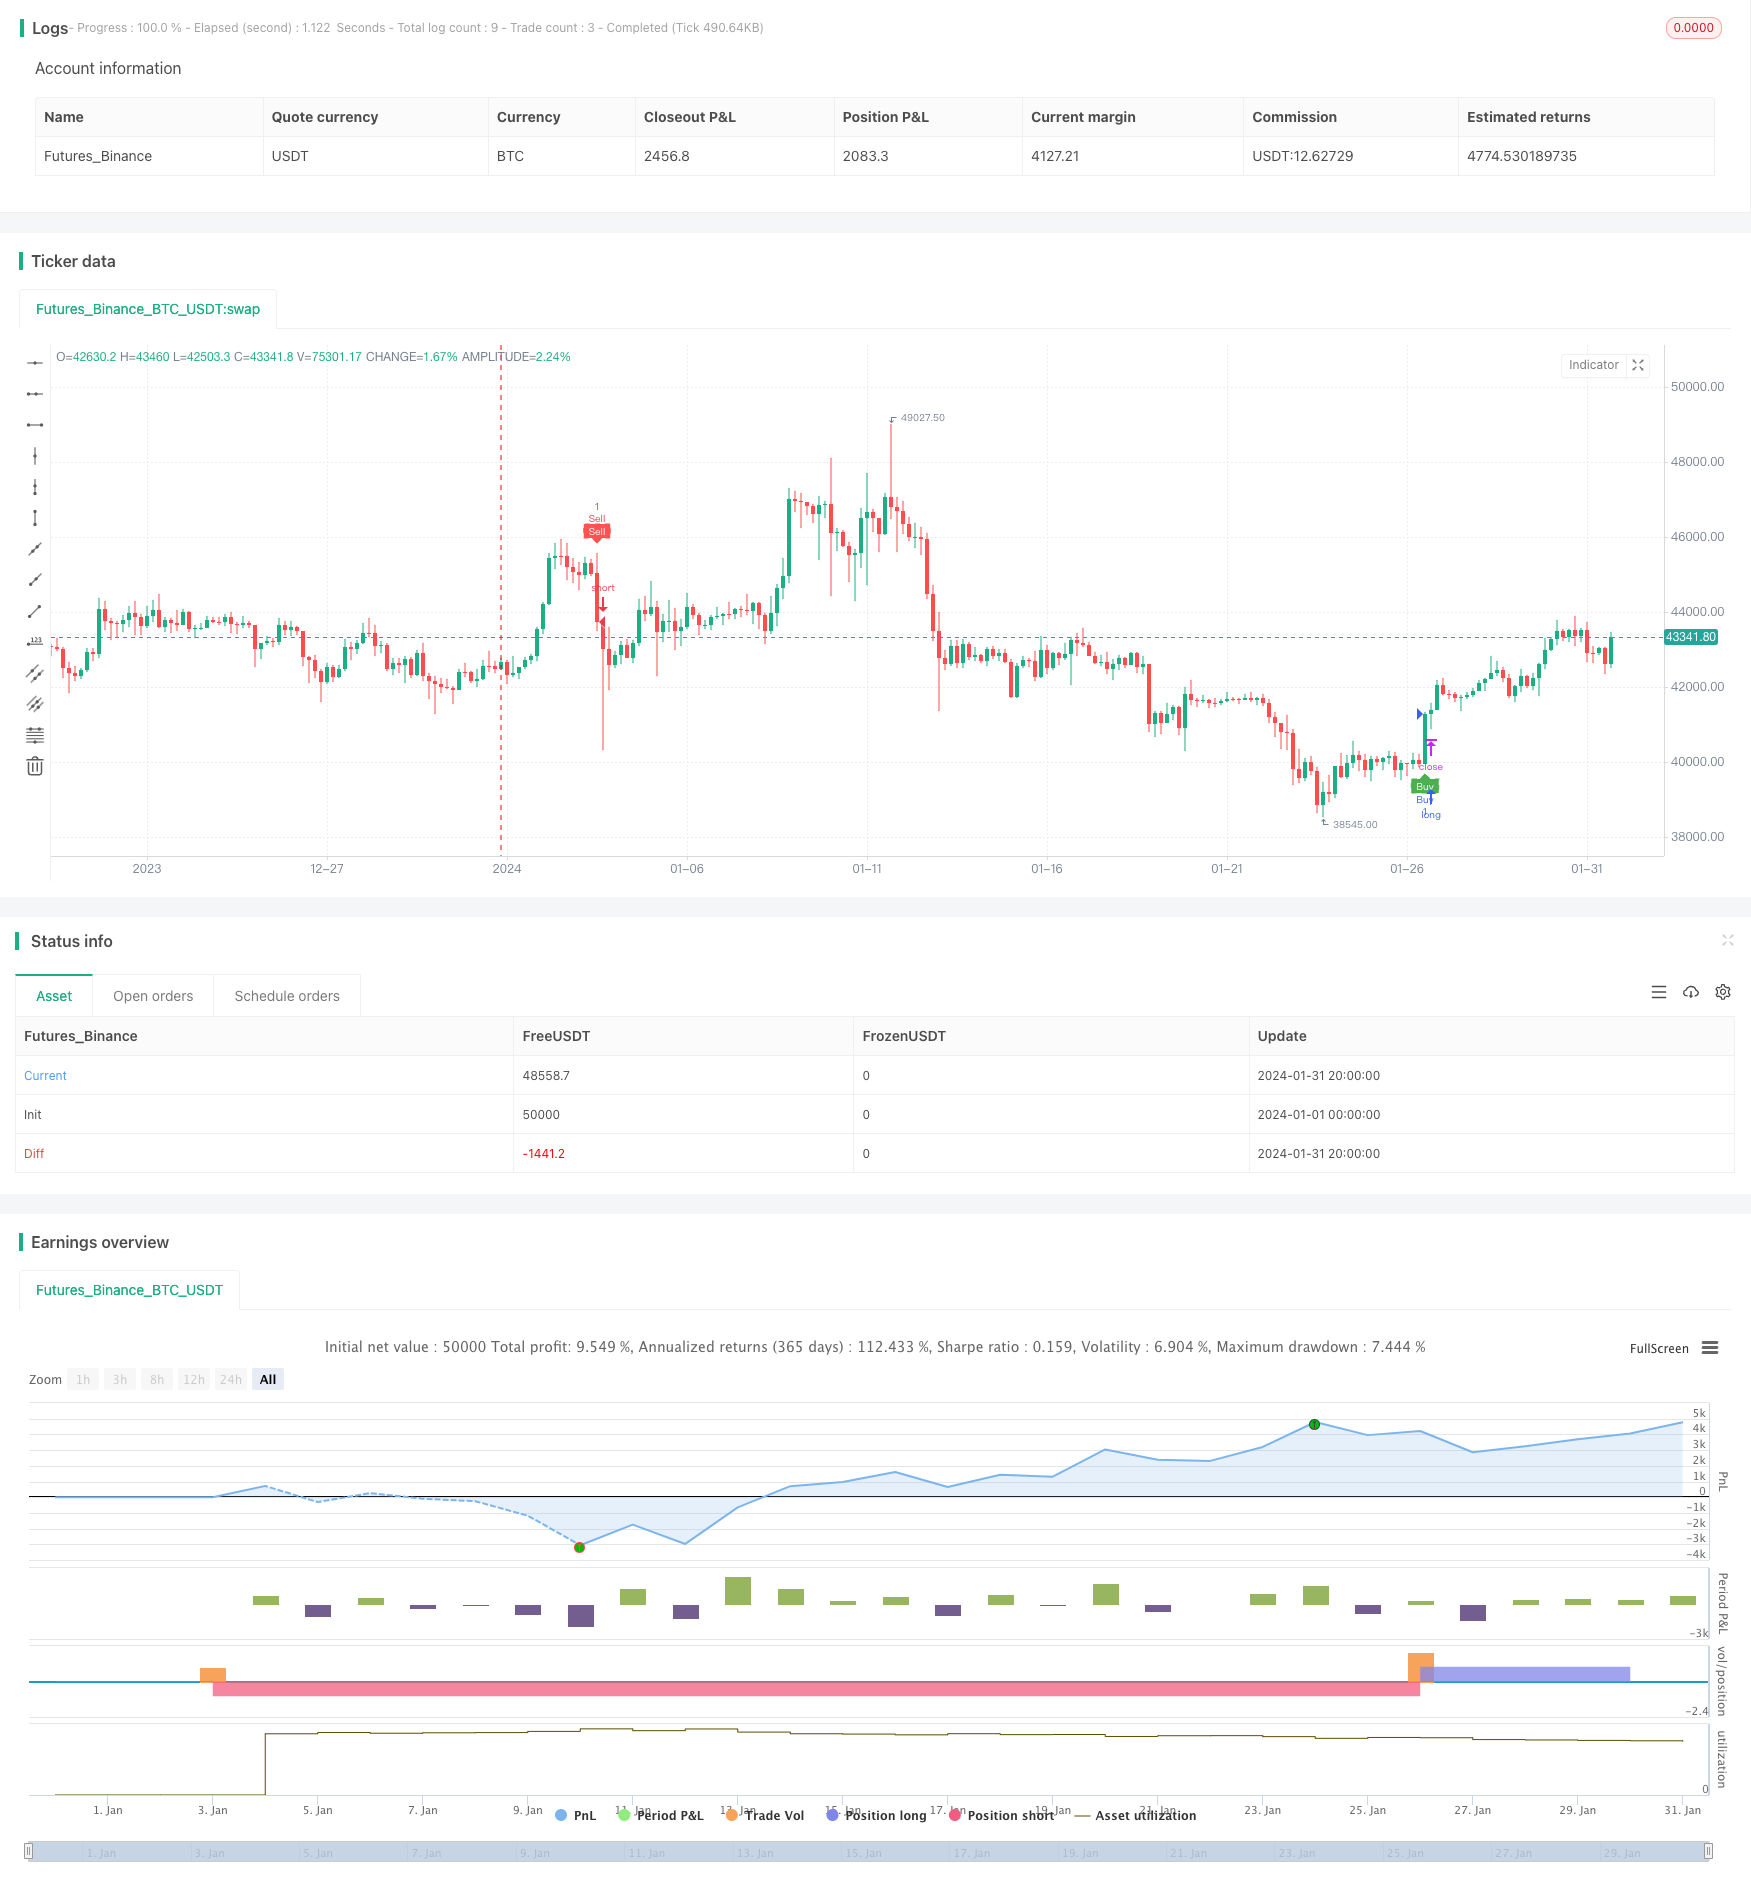
Overview
This strategy generates trading signals by calculating the Directional Movement Indexes (DMI) DI+ and DI- along with Average Directional Index (ADX) and Exponential Moving Average (EMA). It triggers a long signal when DI+ crosses above DI- and ADX is above 20. A short signal is triggered when DI- crosses below DI+ and ADX is above 25. The stop loss signal is when DI- crosses above DI+ with ADX above 30.
Strategy Logic
Calculate DI+, DI-, ADX
- Use ta.dmi() to compute DI+, DI-, ADX
- DI+/DI- measures directional price movement
- ADX measures strength of price movement
Calculate Exponential Moving Average
- Use custom my_ema() function to compute EMA
- EMA smoothes price data
Generate trading signals
- Long signal: DI+ crosses above DI- and ADX > 20 and close > EMA
- Indicates upward trend and increased volatility
- Short signal: DI- crosses below DI+ and ADX > 25 and close < EMA
- Indicates downward trend and high volatility
- Long signal: DI+ crosses above DI- and ADX > 20 and close > EMA
Set stop loss
- Long stop loss: DI- crosses above DI+ and ADX > 30
- Indicates trend reversal
- Short stop loss: DI+ crosses below DI- and ADX > 30
- Indicates trend reversal
- Long stop loss: DI- crosses above DI+ and ADX > 30
In summary, this strategy combines momentum and trend analysis indicators to trade when strong price trends emerge, with stop losses to limit losses.
Advantage Analysis
- Dual DI avoids false signals
- Single DI can give false signals, dual DI ensures trend
- ADX threshold requires increased volatility
- Only trades high volatility moves, avoids ranging
- EMA complements DI
- EMA identifies mid/long term trends
- Strict stop loss
- Cuts losses quickly
Risk Analysis
- Frequent stop loss
- Volatile swings may trigger frequent stops
- Parameter dependence
- Optimal DI and ADX parameters need to be found
- Low trade frequency
- Strict rules reduce trades
Can optimize by expanding stop loss, tuning parameters, adding filters to increase frequency.
Optimization Opportunities
- Parameter optimization
- Optimize DI and ADX parameters
- Add filters
- Volume, divergence etc.
- Widen stop loss
- Relax stops to reduce frequency
Conclusion
This strategy combines momentum and trend analysis indicators to trade strong trends, with strict stops to control risk. Can further improve performance through parameter optimization, additional filters, and relaxed stops.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_int_1 | 14 | DI Length |
| v_input_int_2 | 14 | ADX Smoothing |
| v_input_int_3 | 26 | EMA Length |
| v_input_source_1_close | 0 | EMA Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_bool_1 | true | Signal Labels |
Source Pine Script
/*backtest
start: 2024-01-01 00:00:00
end: 2024-01-31 23:59:59
period: 4h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This Pine Script™ code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © Tamil_FNO_Trader

//@version=5
strategy("Overlay Signals by TFOT", overlay=true)

// Calculate DMI
len = input.int(14, minval=1, title="DI Length")
lensig = input.int(14, title="ADX Smoothing", minval=1, maxval=50)
[diplus, diminus, adx] = ta.dmi(len, lensig)

// Get EMA
emalen = input.int(26, minval=1, title = "EMA Length")
emasrc = input.source(close, title = "EMA Source")

my_ema(src, length) =>
    alpha = 2 / (length + 1)
    sum = 0.0
    sum := na(sum[1]) ? src : alpha * src + (1 - alpha) * nz(sum[1])
EMA2 = my_ema(emasrc, emalen)

// Variables
var bool buycondition1 = false
var bool sellcondition1 = false

var int firstbuybar = na
var int firstsellbar = na

var int buyexitbar = na
var int sellexitbar = na

var bool buyexit1 = false
var bool sellexit1 = false

// Buy & Sell Conditions
buycondition1 := (ta.crossover(diplus, diminus)) and (adx > 20) and (close > EMA2) and na(firstbuybar)
sellcondition1 := (ta.crossover(diminus, diplus)) and (adx > 25) and (close < EMA2) and na(firstsellbar)

buyexit1 := ta.crossover(diminus, diplus) and (adx > 30) and na(buyexitbar)
sellexit1 := ta.crossover(diplus, diminus) and (adx > 30) and na(sellexitbar)

if buycondition1
    if(na(firstbuybar))
        firstbuybar := bar_index
        buyexitbar := na
        firstsellbar := na
        strategy.entry("Buy", strategy.long)

if sellcondition1
    if(na(firstsellbar))
        firstsellbar := bar_index
        sellexitbar := na
        firstbuybar := na
        strategy.entry("Sell", strategy.short)

if buyexit1 and not na(firstbuybar)
    if(na(buyexitbar))
        buyexitbar := bar_index
        firstbuybar := na
        firstsellbar := na
        strategy.close("Buy")

if sellexit1 and not na(firstsellbar)
    if(na(sellexitbar))
        sellexitbar := bar_index
        firstsellbar := na
        firstbuybar := na
        strategy.close("Sell")

// Plot signals on chart
hl = input.bool(defval = true, title = "Signal Labels")

plotshape(hl and buycondition1 and bar_index == firstbuybar ? true : na, "Buy", style = shape.labelup, location = location.belowbar, color = color.green, text = "Buy", textcolor = color.white, size = size.tiny)
plotshape(hl and sellcondition1 and bar_index == firstsellbar ? true : na, "Sell", style = shape.labeldown, location = location.abovebar, color = color.red, text = "Sell", textcolor = color.white, size = size.tiny)

plotshape(hl and buyexit1 and bar_index == buyexitbar ? true : na, "Buy Exit", style = shape.labelup, location = location.belowbar, color = color.red, text = "Buy X", textcolor = color.white, size = size.tiny)
plotshape(hl and sellexit1 and bar_index == sellexitbar ? true : na, "Sell Exit", style = shape.labeldown, location = location.abovebar, color = color.red, text = "Sell X", textcolor = color.white, size = size.tiny)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-18. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Overlay-Trend-Signals-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- Dual EMA Crossover Oscillation Tracking StrategyPine Script · Trend following · 5m
- Dual EMA Filtered ATR Adaptive Trend Following StrategyPine Script · Trend following · 1h
- Dual Moving Average Trend Detection with Volatility Based Stop Loss StrategyPine Script · Trend following · 1d
- Dynamic EMA Trend Detection with ATR Threshold StrategyPine Script · Trend following · 1h
- EMA AROON ASHPine Script · Trend following · 3m