Strategy vault / Trend following
Quant Trading Strategy Based on Moving Average Crossover
This strategy is built based on the golden cross and dead cross principles of simple moving averages (SMA). It uses the golden cross of 3-day and 5-day lines as the entry signal and stop loss or take profit as the…
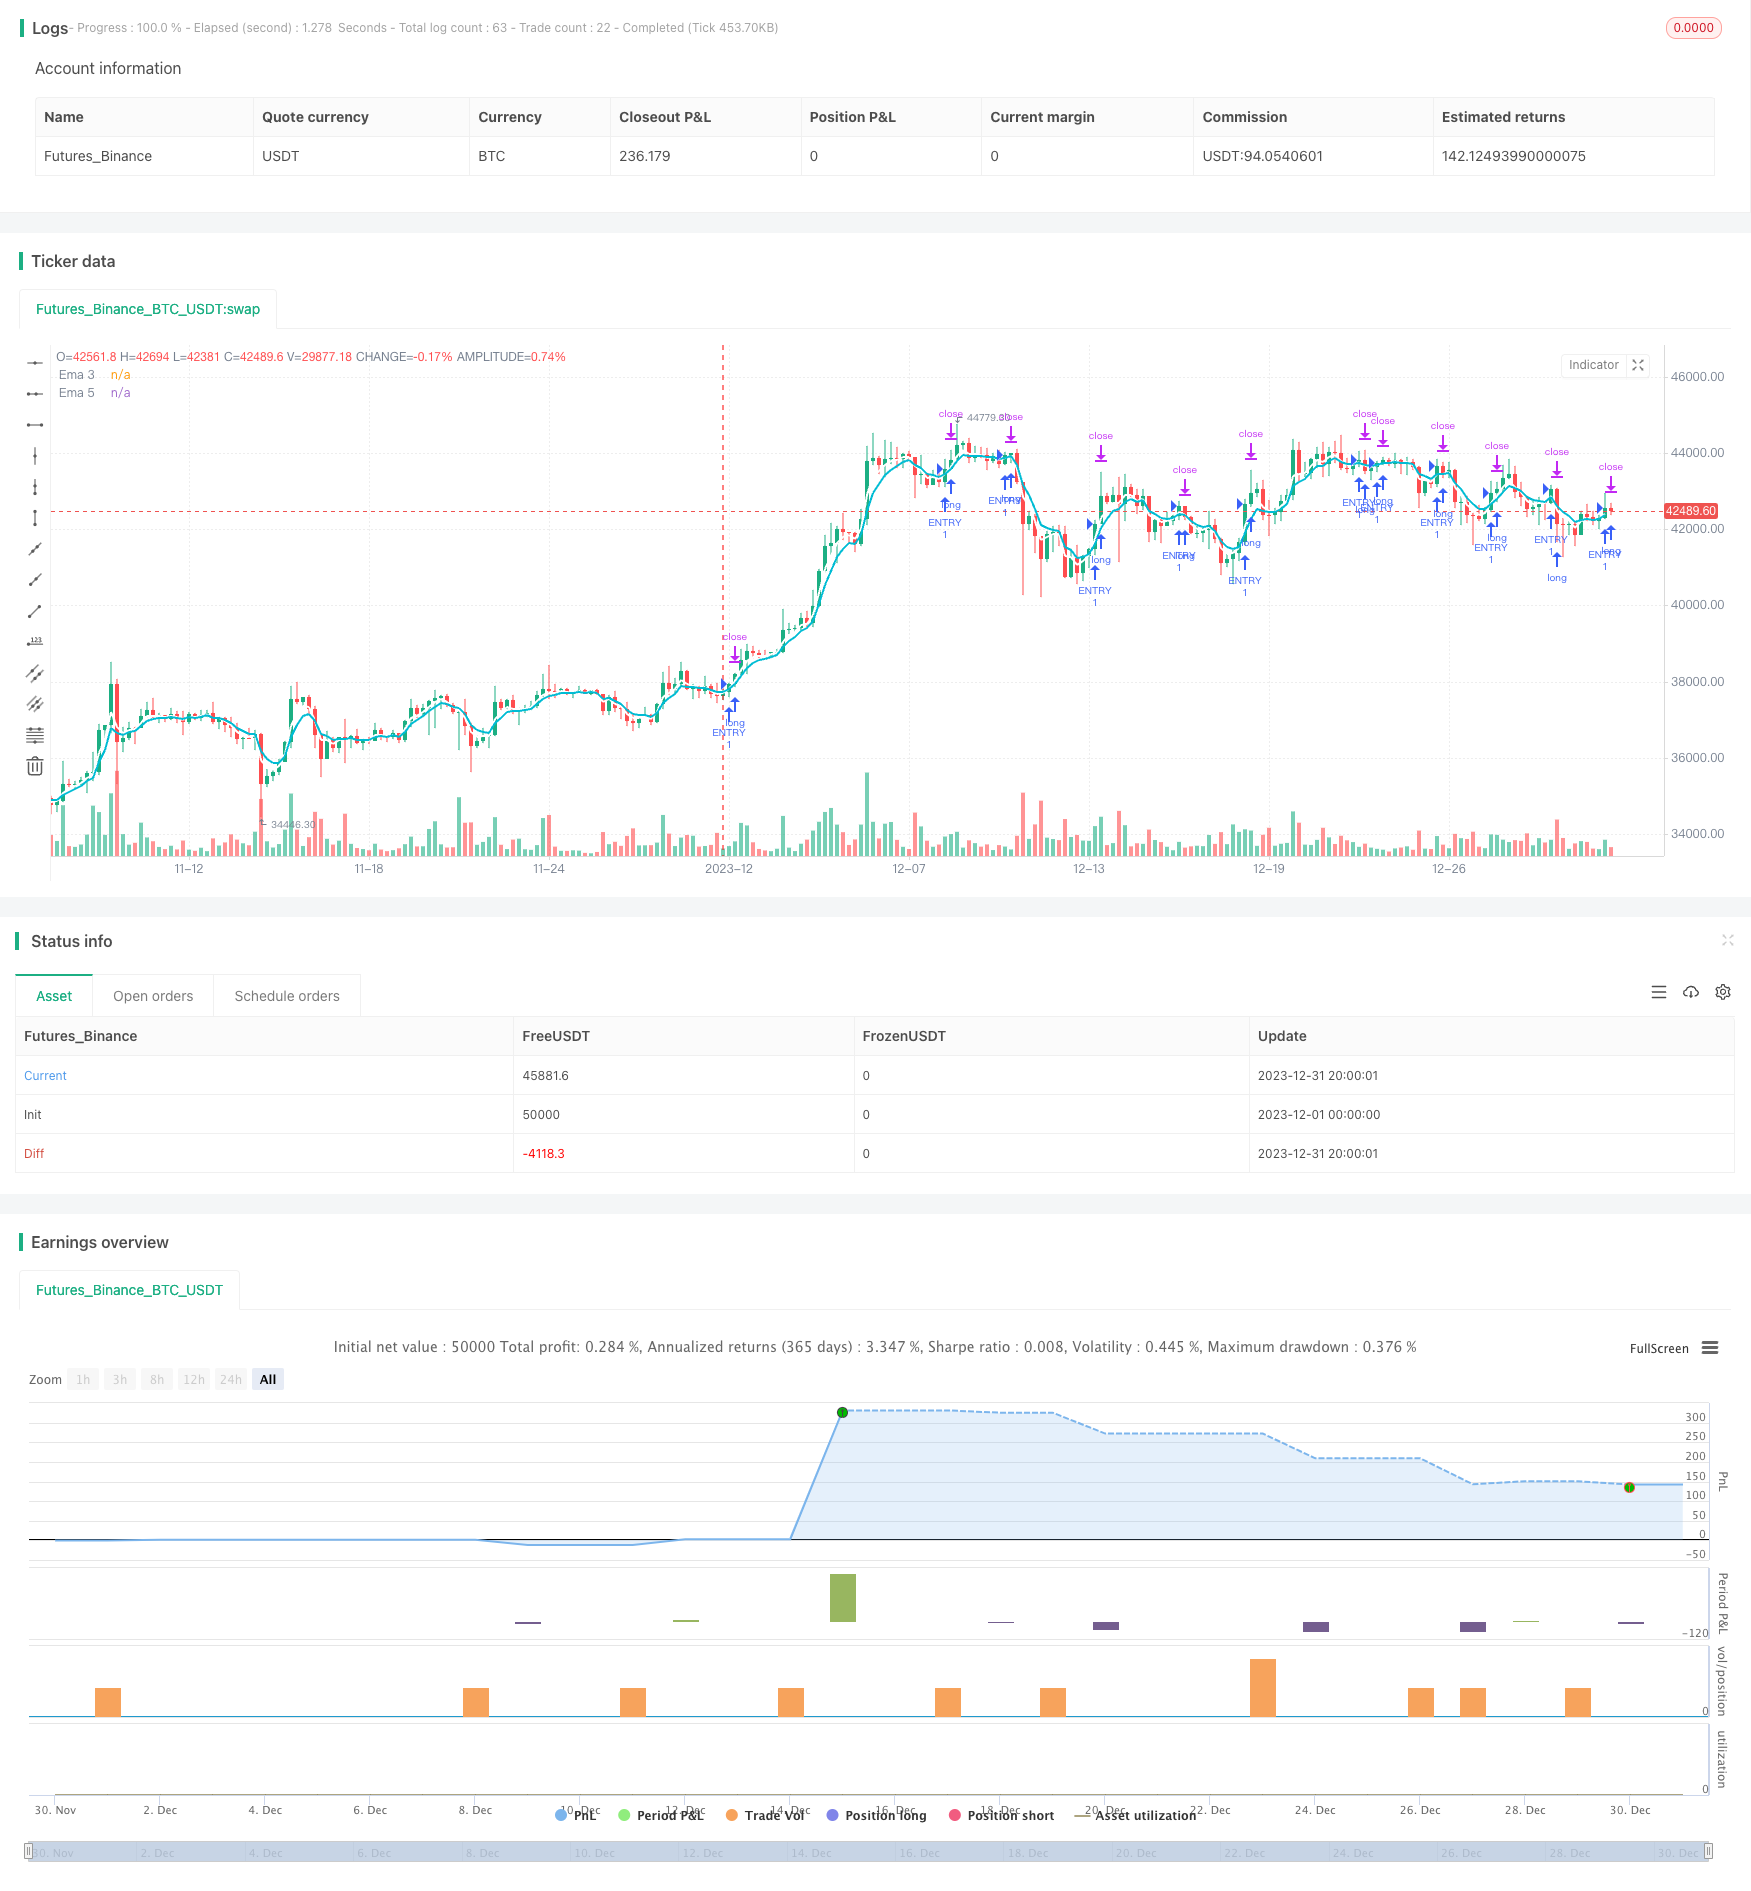
Overview
This strategy is built based on the golden cross and dead cross principles of simple moving averages (SMA). It uses the golden cross of 3-day and 5-day lines as the entry signal and stop loss or take profit as the exit signal.
Strategy Principle
The strategy is mainly based on two SMAs, the 3-day line and the 5-day line. Among them, the 3-day line represents the short-term trend, and the 5-day line represents the longer mid-term trend. When the short term rises rapidly, that is, when the 3-day line crosses above the 5-day line, it indicates that the current market is in an upward trend. At this time, go long. On the contrary, when the short term falls rapidly, that is, when the 3-day line crosses below the 5-day line, it indicates that the current market is in a downward trend. At this time, go short. By capturing the crossover of price changes between the two cycles of short-term and medium-term, the market can be better judged and the probability of successful entry can be improved.
Advantage Analysis
The strategy has the following advantages:
- The strategy logic is simple and clear, easy to understand and implement.
- The moving average crossover strategy makes relatively accurate judgments on the overall market trend with high probability of successful entry.
- Selecting moving averages of two different cycles can better grasp market changes.
- The implementation of take profit and stop loss mechanisms effectively controls losses.
Risk Analysis
The strategy also has some risks:
- Due to the use of shorter moving average cycles, it is prone to be affected by short-term market fluctuations, which may increase the probability of stop loss.
- The strategy is relatively mechanized and cannot adapt to special market conditions.
- It does not consider the judgment of long-term trends, which can cause the strategy to suffer greater losses in a long-term market downturn.
To reduce risks, we can consider optimizing the selection of entry moving averages, or adding auxiliary judgments of long-cycle moving averages. At the same time, the take profit and stop loss points can also be adjusted to better fit the real market conditions.
Optimization Directions
The strategy can be optimized in the following aspects:
- Increase more moving averages of different cycles to form multi-level screening to improve the stability of the strategy.
- Add judgments of other technical indicators such as MACD, RSI, etc. to assist entry.
- Add judgments on long-term trends to avoid going long in long-term downtrends.
- Optimize the take profit and stop loss points to better adapt to actual market fluctuations.
- Test longer backtest periods to evaluate parameter stability.
Summary
This strategy is constructed based on the principle of moving average crossover, adopting entry on golden cross and exit on stop loss or take profit. It is simple to implement and has relatively stable backtest results. By adding more auxiliary technical indicators, optimizing parameters, and expanding backtest range, etc., the stability and profitability of the strategy can be further enhanced. In general, the moving average strategy has good market adaptability and is worth further research and application.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | From Month |
| v_input_2 | true | From Day |
| v_input_3 | 2018 | From Year |
| v_input_4 | true | To Month |
| v_input_5 | true | To Day |
| v_input_6 | 9999 | To Year |
Source Pine Script
/*backtest
start: 2023-12-01 00:00:00
end: 2023-12-31 23:59:59
period: 5h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
strategy(title="Revolut v1.0", overlay=true)

// === GENERAL INPUTS ===
ATR = atr(3)
ema3 = ema(close, 3)
ema5 = ema(close, 5)

// === INPUT BACKTEST RANGE ===
FromMonth = input(defval = 1, title = "From Month", minval = 1, maxval = 12)
FromDay   = input(defval = 1, title = "From Day", minval = 1, maxval = 31)
FromYear  = input(defval = 2018, title = "From Year", minval = 2017)
ToMonth   = input(defval = 1, title = "To Month", minval = 1, maxval = 12)
ToDay     = input(defval = 1, title = "To Day", minval = 1, maxval = 31)
ToYear    = input(defval = 9999, title = "To Year", minval = 2017)

// === FUNCTION EXAMPLE ===
start     = timestamp(FromYear, FromMonth, FromDay, 00, 00)  // backtest start window
finish    = timestamp(ToYear, ToMonth, ToDay, 23, 59)        // backtest finish window
window()  => true// create function "within window of time"


// === PLOTTING ===
plot(ema3, title="Ema 3", color = white, linewidth = 2, transp=0)
plot(ema5, title="Ema 5", color = aqua, linewidth = 2, transp=0)


// === ENTRY POSITION LOGIC ===
entryCondition = crossover(ema(close, 3), ema(close, 5))
if (entryCondition)
    strategy.entry("ENTRY", strategy.long, when=window())


// === EXIT POSTION LOGIC ===
//strategy.exit("Take Profit", "ENTRY", profit=6, loss=5, when=window())
strategy.exit("Take Profi Or STOP", "ENTRY", profit = 6, loss = 5, when=window())


// #####################################
// We can start to incorperate this into the script later
// We can program a emergency exit price
//strategy.close_all()

// You can use this if you want another exit
//strategy.exit("2nd Exit", "ENTRY", profit=1500, stop=500, when=window())
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-23. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Quant-Trading-Strategy-Based-on-Moving-Average-Crossover.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dynamic Dual EMA Crossover Strategy with Adaptive Profit Loss ControlPine Script · Trend following · 1d
- EMA and RSI Trend Trading StrategyPine Script · Trend following · 1d
- Fixed Range Volume Profile And Anchored VWAP Trend Identification Strategy With Dynamic Stop LossPine Script · Trend following · 1h
- Multi Moving Average Trend Capture and Crossover Confirmation Trading SystemPine Script · Trend following · 1m