Strategy vault / Trend following
RISOTTO
RSI OTT is Anıl Özekşi's latest derived version of Optimized Trend Tracker on RSI Oscillator. He can solve the fake signals of RSI Oscillator by adopting OTT on the indicator. Those who don't know OTT can search in…
RSI OTT is Anıl Özekşi's latest derived version of Optimized Trend Tracker on RSI Oscillator. He can solve the fake signals of RSI Oscillator by adopting OTT on the indicator. Those who don't know OTT can search in indicators.
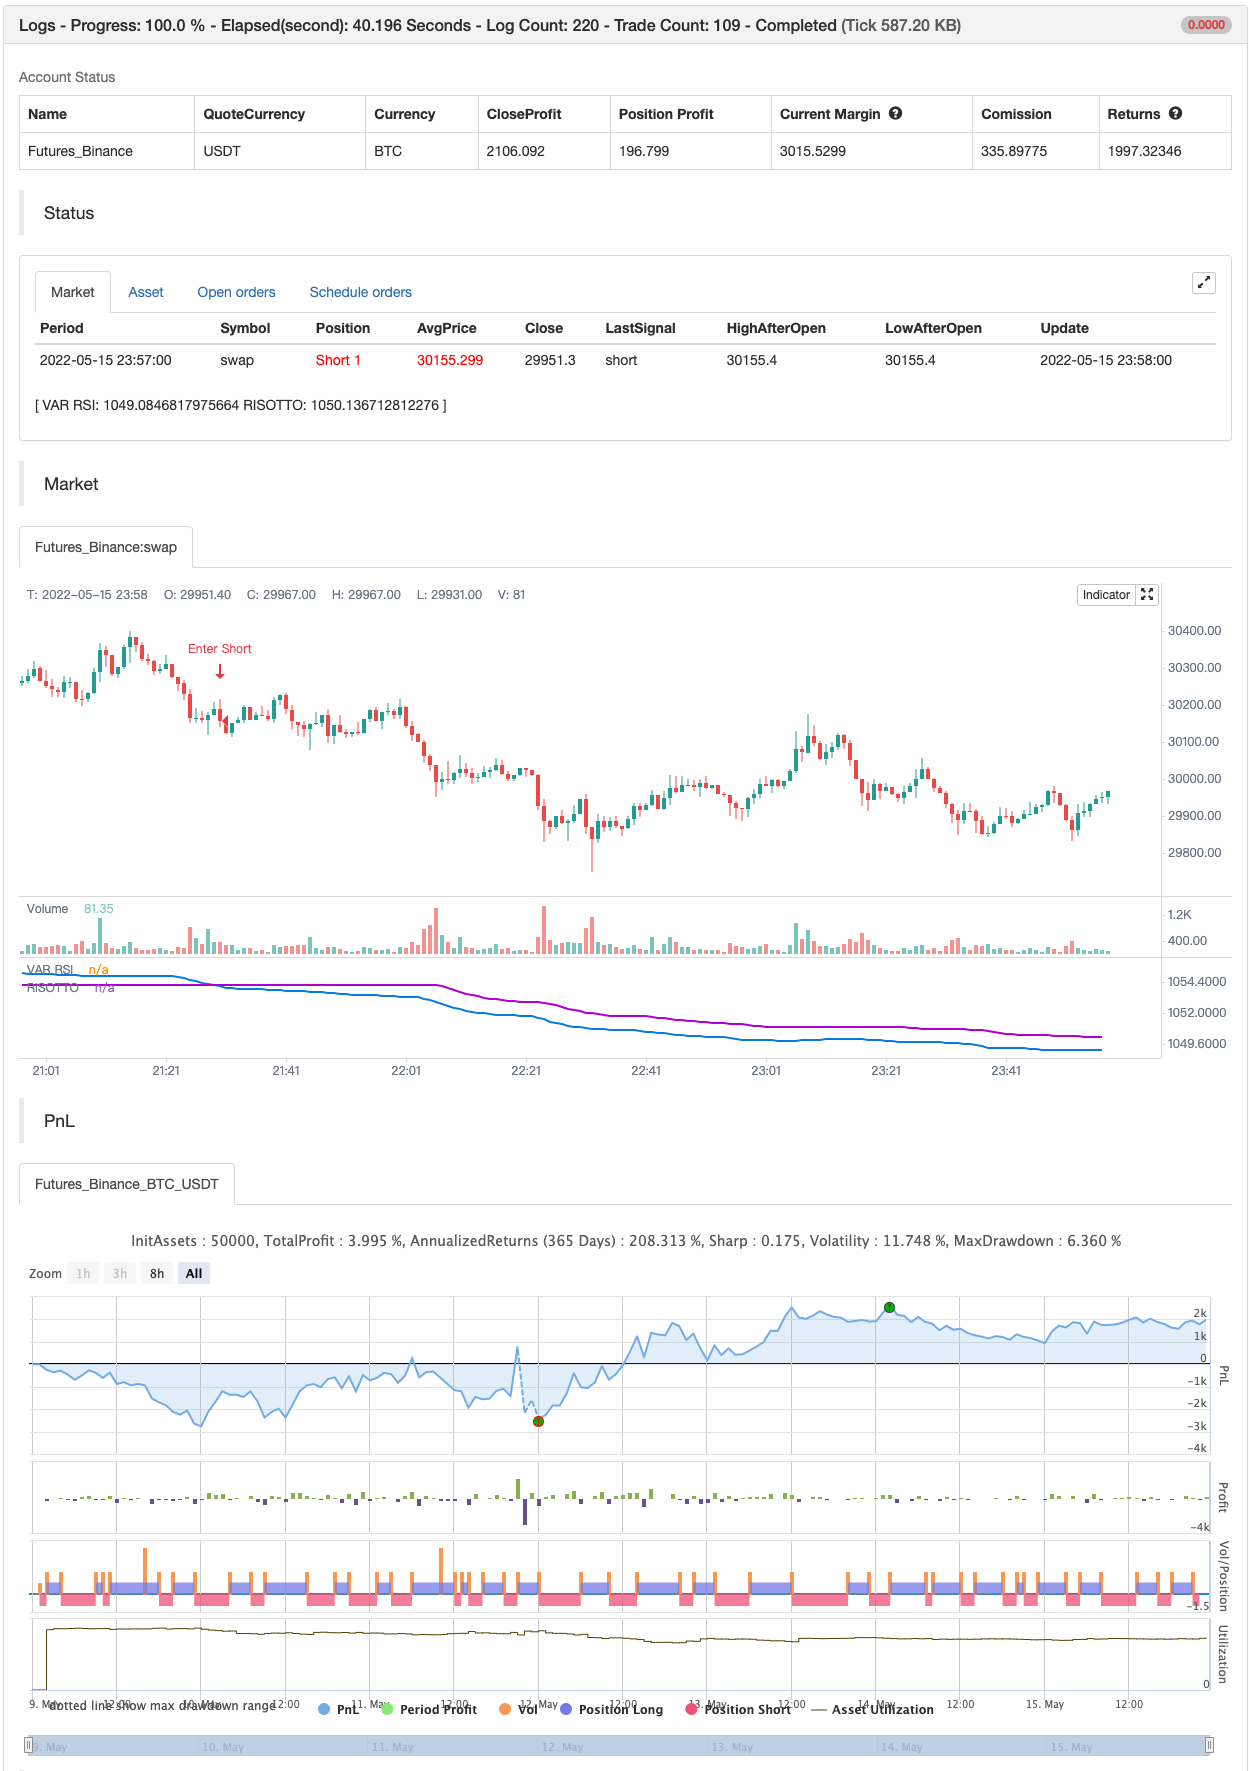
backtest
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_4 | false | Show RSI/OTT Crossing Signals? |
| v_input_1 | 100 | (?0.0 RSI)0.0 RSI Period |
| v_input_2 | 50 | (?RISOTTO)RISOTTO Period |
| v_input_3 | 0.2 | RISOTTO Percent |
Source Pine Script
/*backtest
start: 2022-05-09 00:00:00
end: 2022-05-15 23:59:00
period: 1m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
//created by    : @Anil_Ozeksi
//developer     : @Anil_Ozeksi
//author        : @mr. fofenks

study("RISOTTO",overlay=false, precision=2)


src               = close

//RSI
x1                = input(defval = 100      , title = "VAR RSI Period"          , type = input.integer, minval = 1  ,step = 1       , group = "VAR RSI")

//OTT
x2                = input(defval = 50       , title = "RISOTTO Period"          , type = input.integer, minval = 1  ,step = 1       , group = "RISOTTO")
x3                = input(defval = 0.2      , title = "RISOTTO Percent"         , type = input.float  , minval = 0  ,step = 0.05    , group = "RISOTTO")

//Signals
showsignalsc      = input( defval=false     , title = "Show RSI/OTT Crossing Signals?", type=input.bool)

OTT_Func(src,length, percent)=>
    valpha        = 2/(length+1)
    vud1          = src>src[1] ? src-src[1] : 0
    vdd1          = src<src[1] ? src[1]-src : 0
    vUD           = sum(vud1,9)
    vDD           = sum(vdd1,9)
    vCMO          = nz((vUD-vDD)/(vUD+vDD))
    VAR           = 0.0
    VAR          := nz(valpha*abs(vCMO)*src)+(1-valpha*abs(vCMO))*nz(VAR[1])
    fark          = VAR*percent*0.01//multi*atr //
    longStop      = VAR - fark
    longStopPrev  = nz(longStop[1], longStop)
    longStop     := VAR > longStopPrev ? max(longStop, longStopPrev) : longStop
    shortStop     = VAR + fark
    shortStopPrev = nz(shortStop[1], shortStop)
    shortStop    := VAR < shortStopPrev ? min(shortStop, shortStopPrev) : shortStop
    dir           = 1
    dir          := nz(dir[1], dir)
    dir          := dir == -1 and VAR > shortStopPrev ? 1 : dir == 1 and VAR < longStopPrev ? -1 : dir
    MT            = dir==1 ? longStop: shortStop
    OTT           = VAR>MT ? MT*(200+percent)/200 : MT*(200-percent)/200
    [VAR,OTT]

rsi               = rsi(src,x1)

[VRSI,_]          = OTT_Func(rsi, x2, 1)
[_,RISOTTO]       = OTT_Func(VRSI+1000, 2, x3)

buySignalc        = crossover(VRSI+1000, RISOTTO[2])
sellSignallc      = crossunder(VRSI+1000, RISOTTO[2])

plot(VRSI+1000         , color=#0585E1     , linewidth=2, title="VAR RSI" , display = display.all)
plot(nz(RISOTTO[2])    , color=#B800D9     , linewidth=2, title="RISOTTO" , display = display.all)


plotshape(buySignalc    and showsignalsc ? RISOTTO*0.995 : na, title="Buy"  , text="Buy"    , location=location.absolute, style=shape.labelup   , size=size.tiny, color=color.green , textcolor=color.white)
plotshape(sellSignallc  and showsignalsc ? RISOTTO*1.005 : na, title="Sell" , text="Sell"   , location=location.absolute, style=shape.labeldown , size=size.tiny, color=color.red   , textcolor=color.white)

//alertcondition(cross(src, OTT[2]), title="Price Cross Alert", message="OTT - Price Crossing!")
//alertcondition(crossover(src, OTT[2]), title="Price Crossover Alarm", message="PRICE OVER OTT - BUY SIGNAL!")
//alertcondition(crossunder(src, OTT[2]), title="Price Crossunder Alarm", message="PRICE UNDER OTT - SELL SIGNAL!")


if buySignalc
    strategy.entry("Enter Long", strategy.long)
else if sellSignallc
strategy.entry("Enter Short", strategy.short)Published by ChaoZhang on the FMZ strategy square · last modified 2022-05-17. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/RISOTTO.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive ATR and RSI Trend Following Strategy with Trailing Stop LossPine Script · Trend following · 1h
- Advanced Supertrend Indicator Trading Mechanism Optimization StrategyPine Script · Trend following · 1d
- BB Percentage Index Trend Fading StrategyPine Script · Trend following · 1h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dual Indicator Dynamic Trend Trading Strategy Multi dimensional Technical Analysis System Based on RSI and MACDPine Script · Trend following