RSI and Moving Average Breakout Strategy
The RSI and Moving Average Breakout Strategy is a quantitative strategy that utilizes both the RSI indicator and moving average lines to determine trading opportunities. The core idea of this strategy is to seek…
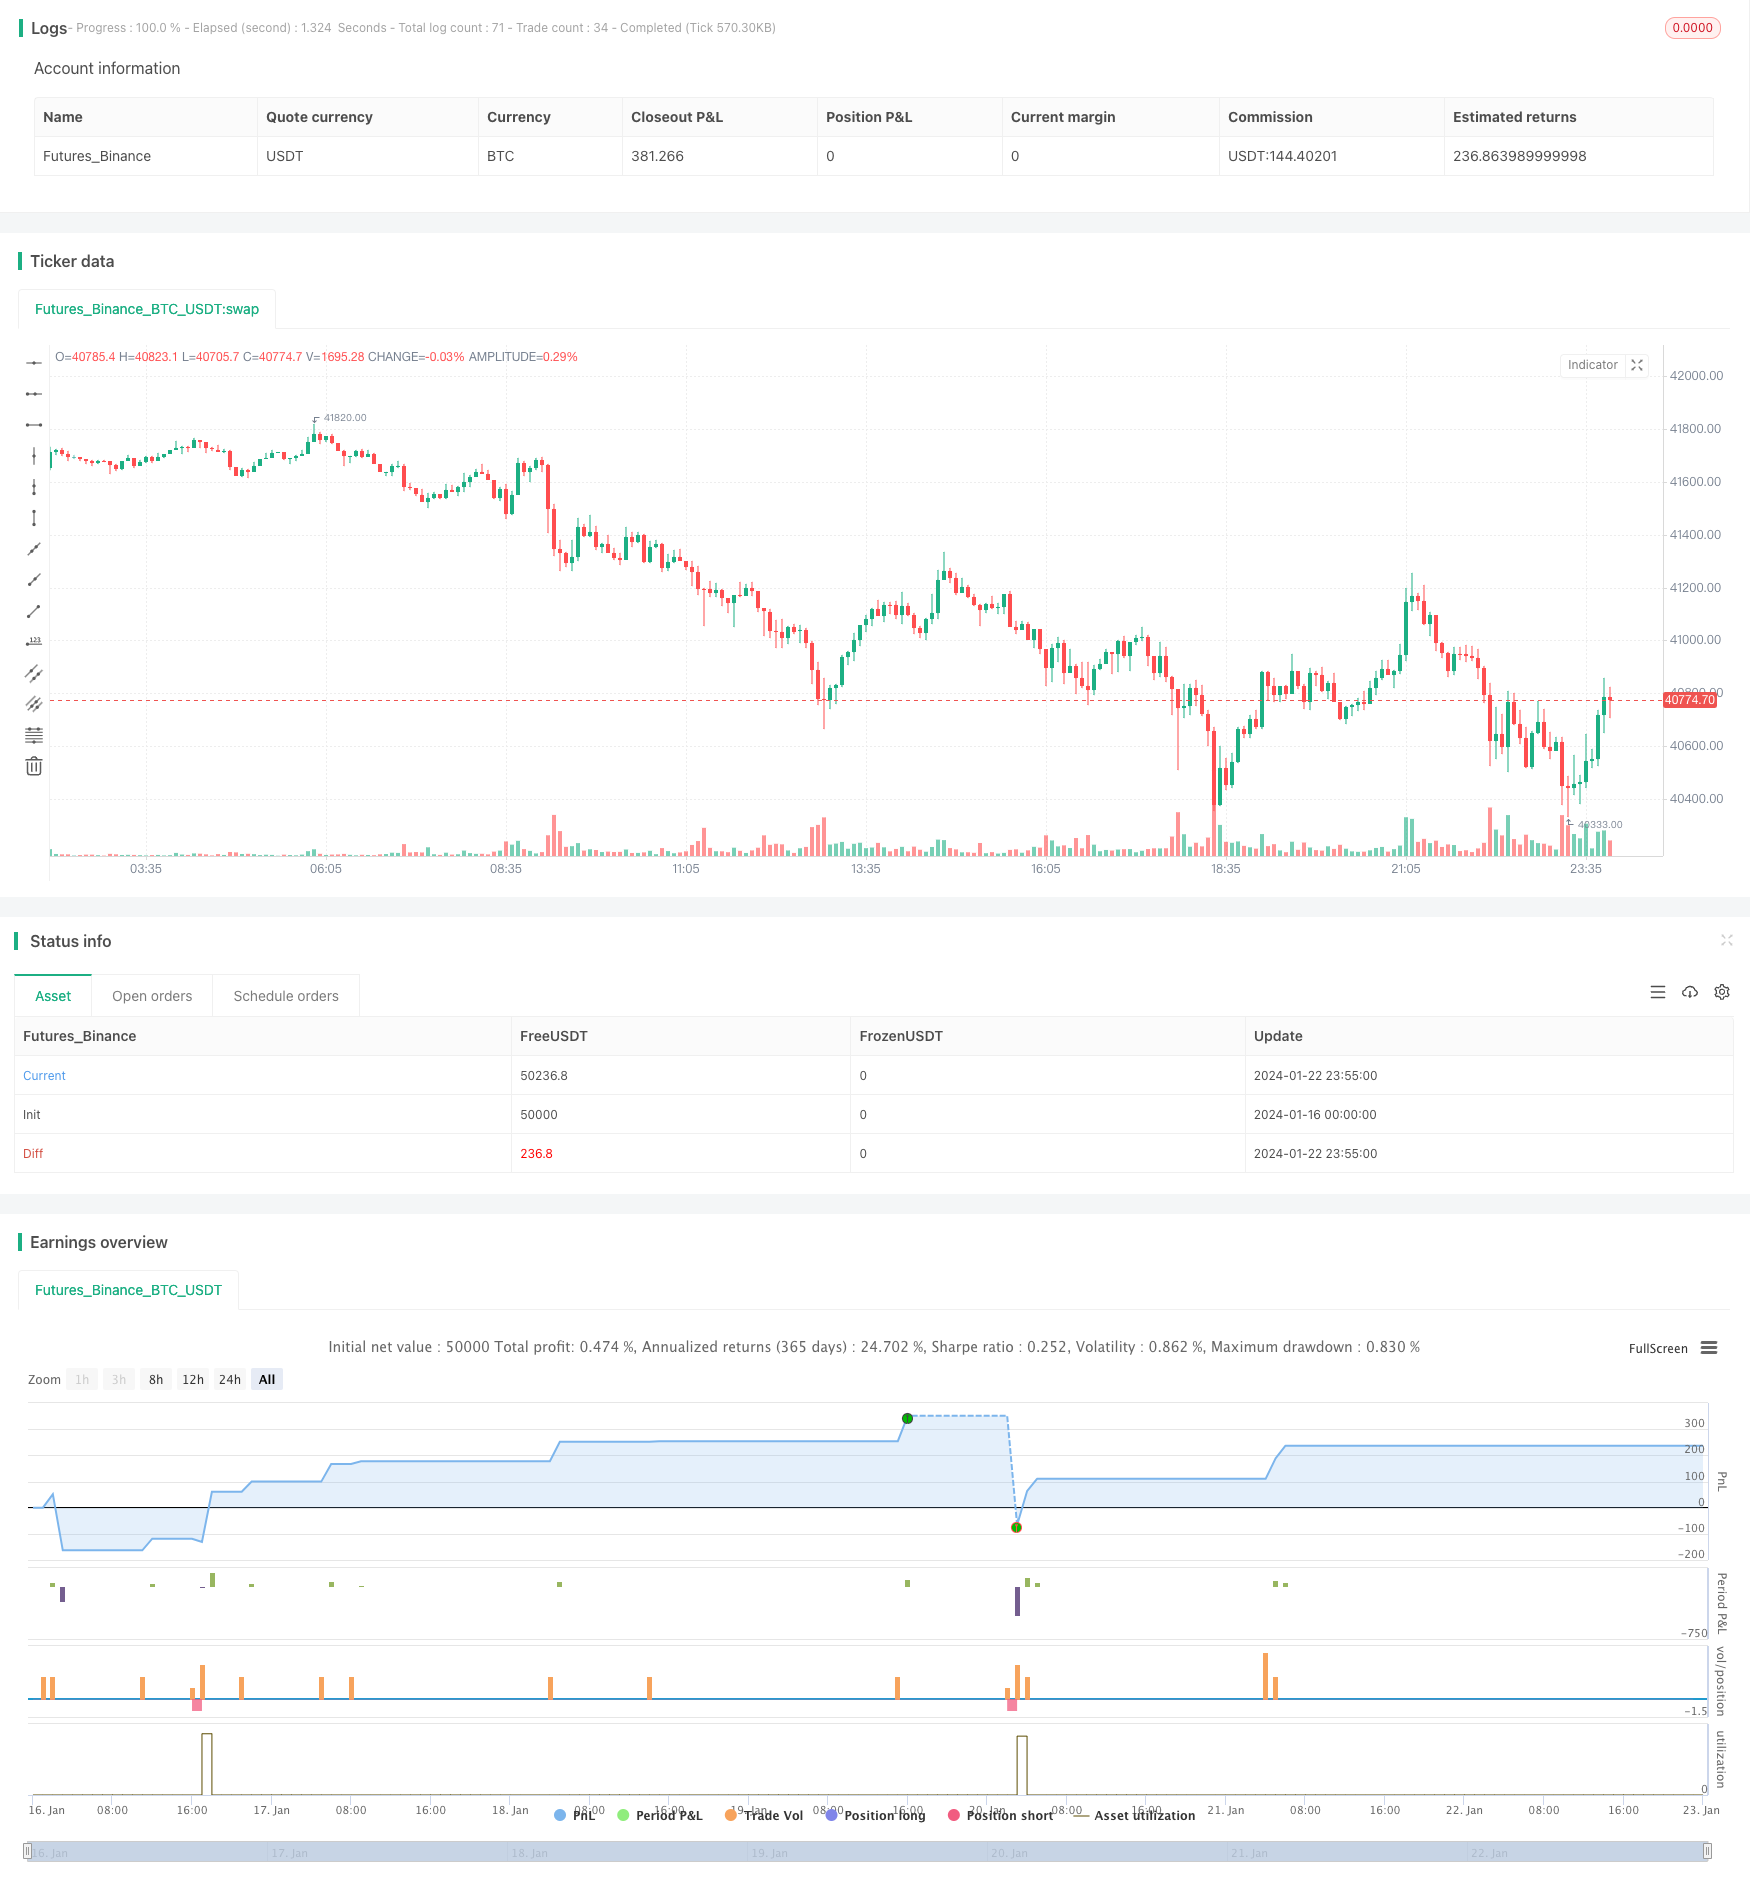
Overview
The RSI and Moving Average Breakout Strategy is a quantitative strategy that utilizes both the RSI indicator and moving average lines to determine trading opportunities. The core idea of this strategy is to seek better breakout points with the direction of moving averages when RSI reaches overbought or oversold levels.
Strategy Logic
Calculate RSI indicator and Simple Moving Average lines based on user-defined parameters.
When RSI crosses above the oversold line (default 30), a long signal is generated if price is below the LONG exit Moving Average.
When RSI crosses below the overbought line (default 70), a short signal is generated if price is above the SHORT exit Moving Average.
Users can choose to filter signals based on a trend Moving Average line. Signals are only generated when price is above or below the filtering Moving Average.
Exits are determined by the LONG and SHORT exit Moving Average lines.
Advantage Analysis
Dual indicator design improves accuracy by incorporating two major market factors.
Utilizes the mean-reversion characteristic of RSI effectively to locate turning points.
Additional filter with Moving Averages increases logic rigor to avoid chasing tops and bottoms.
Customizable parameters allow optimizations across different products and timeframes.
Simple logic makes it easy to comprehend and modify.
Risk Analysis
Whipsaws are common with RSI, Density indicator could help.
RSI tends to fail on larger timeframes, parameters can be adjusted or additional indicators can assist.
Moving Averages have lagging effect, lengths could be shortened or indicators like MACD can assist.
More indicators should be introduced to validate signals due to the basic logic.
Optimization Directions
Optimize RSI parameters or introduce Density indicator to reduce false signals.
Incorporate trend and volatility indicators like DMI and BOLL to locate trends and supports.
Introduce MACD to replace or complement Moving Average judgements.
Add more logic conditions on entry signals to avoid unfavorable breakouts.
Conclusion
The RSI and Moving Average Breakout Strategy combines the overbought-oversold detection of RSI and trend determination of Moving Averages to capitalize on mean-reversion opportunities theoretically. The strategy is intuitive and easy to use for beginners, and can be optimized across different products, making it a recommended starter quantitative strategy. More auxiliary indicators could be introduced to further validate signals and improve profitability.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 0 | Long Only or Short Only or Both?: Both | Long Only | Short Only |
| v_input_2 | 14 | RSI Length |
| v_input_3 | 70 | Upper Threshold |
| v_input_4 | 30 | Lower Threshold |
| v_input_5 | 5 | Long Exit SMA Length |
| v_input_6 | 5 | Short Exit SMA Length |
| v_input_7 | 0 | Trend SMA Filter?: Above | Below | Don't Include |
| v_input_8 | 200 | Trend SMA Length |
Source Pine Script
/*backtest
start: 2024-01-16 00:00:00
end: 2024-01-23 00:00:00
period: 5m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//Global Market Signals: RSI Strategy.
//@version=4
strategy("GMS: RSI Strategy", overlay=true)

LongShort = input(title="Long Only or Short Only or Both?", type=input.string, defval="Both", options=["Both", "Long Only", "Short Only"])
RSILength = input(title="RSI Length", type = input.integer ,defval=14)
RSIUpper = input(title="Upper Threshold", type = input.float ,defval=70)
RSILower = input(title="Lower Threshold", type = input.float ,defval=30)
LongExit = input(title="Long Exit SMA Length", type = input.integer ,defval=5)
ShortExit = input(title="Short Exit SMA Length", type = input.integer ,defval=5)
AboveBelow = input(title="Trend SMA Filter?", type=input.string, defval="Above", options=["Above", "Below", "Don't Include"])
TrendLength = input(title="Trend SMA Length", type = input.integer ,defval=200)


//Long Side

if LongShort =="Long Only" and AboveBelow == "Above"
    strategy.entry("LONG", true, when = rsi(close,RSILength)<RSILower and close< sma(close,LongExit) and close>sma(close,TrendLength))
    strategy.close("LONG", when = close>sma(close,LongExit))

if LongShort =="Long Only" and AboveBelow == "Below"
    strategy.entry("LONG", true, when = rsi(close,RSILength)<RSILower and close< sma(close,LongExit) and close<sma(close,TrendLength))
    strategy.close("LONG", when = close>sma(close,LongExit))

if LongShort =="Long Only" and AboveBelow == "Don't Include"
    strategy.entry("LONG", true, when = rsi(close,RSILength)<RSILower and close< sma(close,LongExit))
    strategy.close("LONG", when = close>sma(close,LongExit))

if LongShort =="Both" and AboveBelow == "Above"
    strategy.entry("LONG", true, when = rsi(close,RSILength)<RSILower and close< sma(close,LongExit) and close>sma(close,TrendLength))
    strategy.close("LONG", when = close>sma(close,LongExit))

if LongShort =="Both" and AboveBelow == "Below"
    strategy.entry("LONG", true, when = rsi(close,RSILength)<RSILower and close< sma(close,LongExit) and close<sma(close,TrendLength))
    strategy.close("LONG", when = close>sma(close,LongExit))

if LongShort =="Both" and AboveBelow == "Don't Include"
    strategy.entry("LONG", true, when = rsi(close,RSILength)<RSILower and close< sma(close,LongExit))
    strategy.close("LONG", when = close>sma(close,LongExit))


//SHORT SIDE

if LongShort =="Short Only" and AboveBelow == "Above"
    strategy.entry("SHORT", false, when = rsi(close,RSILength)>RSIUpper and close> sma(close,ShortExit) and close>sma(close,TrendLength))
    strategy.close("SHORT", when = close<sma(close,ShortExit))

if LongShort =="Short Only" and AboveBelow == "Below"
    strategy.entry("SHORT", false, when = rsi(close,RSILength)>RSIUpper and close> sma(close,ShortExit) and close<sma(close,TrendLength))
    strategy.close("SHORT", when = close<sma(close,ShortExit))

if LongShort =="Short Only" and AboveBelow == "Don't Include"
    strategy.entry("SHORT", false, when = rsi(close,RSILength)>RSIUpper and close> sma(close,ShortExit))
    strategy.close("SHORT", when = close<sma(close,ShortExit))

if LongShort =="Both" and AboveBelow == "Above"
    strategy.entry("SHORT", false, when = rsi(close,RSILength)>RSIUpper and close> sma(close,ShortExit) and close>sma(close,TrendLength))
    strategy.close("SHORT", when = close<sma(close,ShortExit))

if LongShort =="Both" and AboveBelow == "Below"
    strategy.entry("SHORT", false, when = rsi(close,RSILength)>RSIUpper and close> sma(close,ShortExit) and close<sma(close,TrendLength))
    strategy.close("SHORT", when = close<sma(close,ShortExit))

if LongShort =="Both" and AboveBelow == "Don't Include"
    strategy.entry("SHORT", false, when = rsi(close,RSILength)>RSIUpper and close> sma(close,ShortExit))
    strategy.close("SHORT", when = close<sma(close,ShortExit))
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-24. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/RSI-and-Moving-Average-Breakout-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Momentum Breakout Trading Strategy 440964Pine Script · Breakout · 5m
- Moving Average Crossover and Upper Rail Breakthrough Impulse StrategyPine Script · Breakout · 1m
- Quantitative Trading Strategy Based on Ichimoku with Multiple SignalsPine Script · Breakout · 1h
- MACD Bollinger Turtle Trading StrategyPine Script · Breakout · 1d
- Momentum Breakout Intraday Trading StrategyPine Script · Breakout · 5m
- Multi Timeframe Trend Confirmed Quantitative Breakout Trading StrategyPine Script · Breakout · 1d