Strategy vault / Trend following
RSI and Moving Average Crossover Multi Timeframe Trading Strategy
The core idea of this strategy is to identify trend reversal points by utilizing both Relative Strength Index (RSI) and moving averages of different timeframes, in order to capture mid-to-long term trends while…
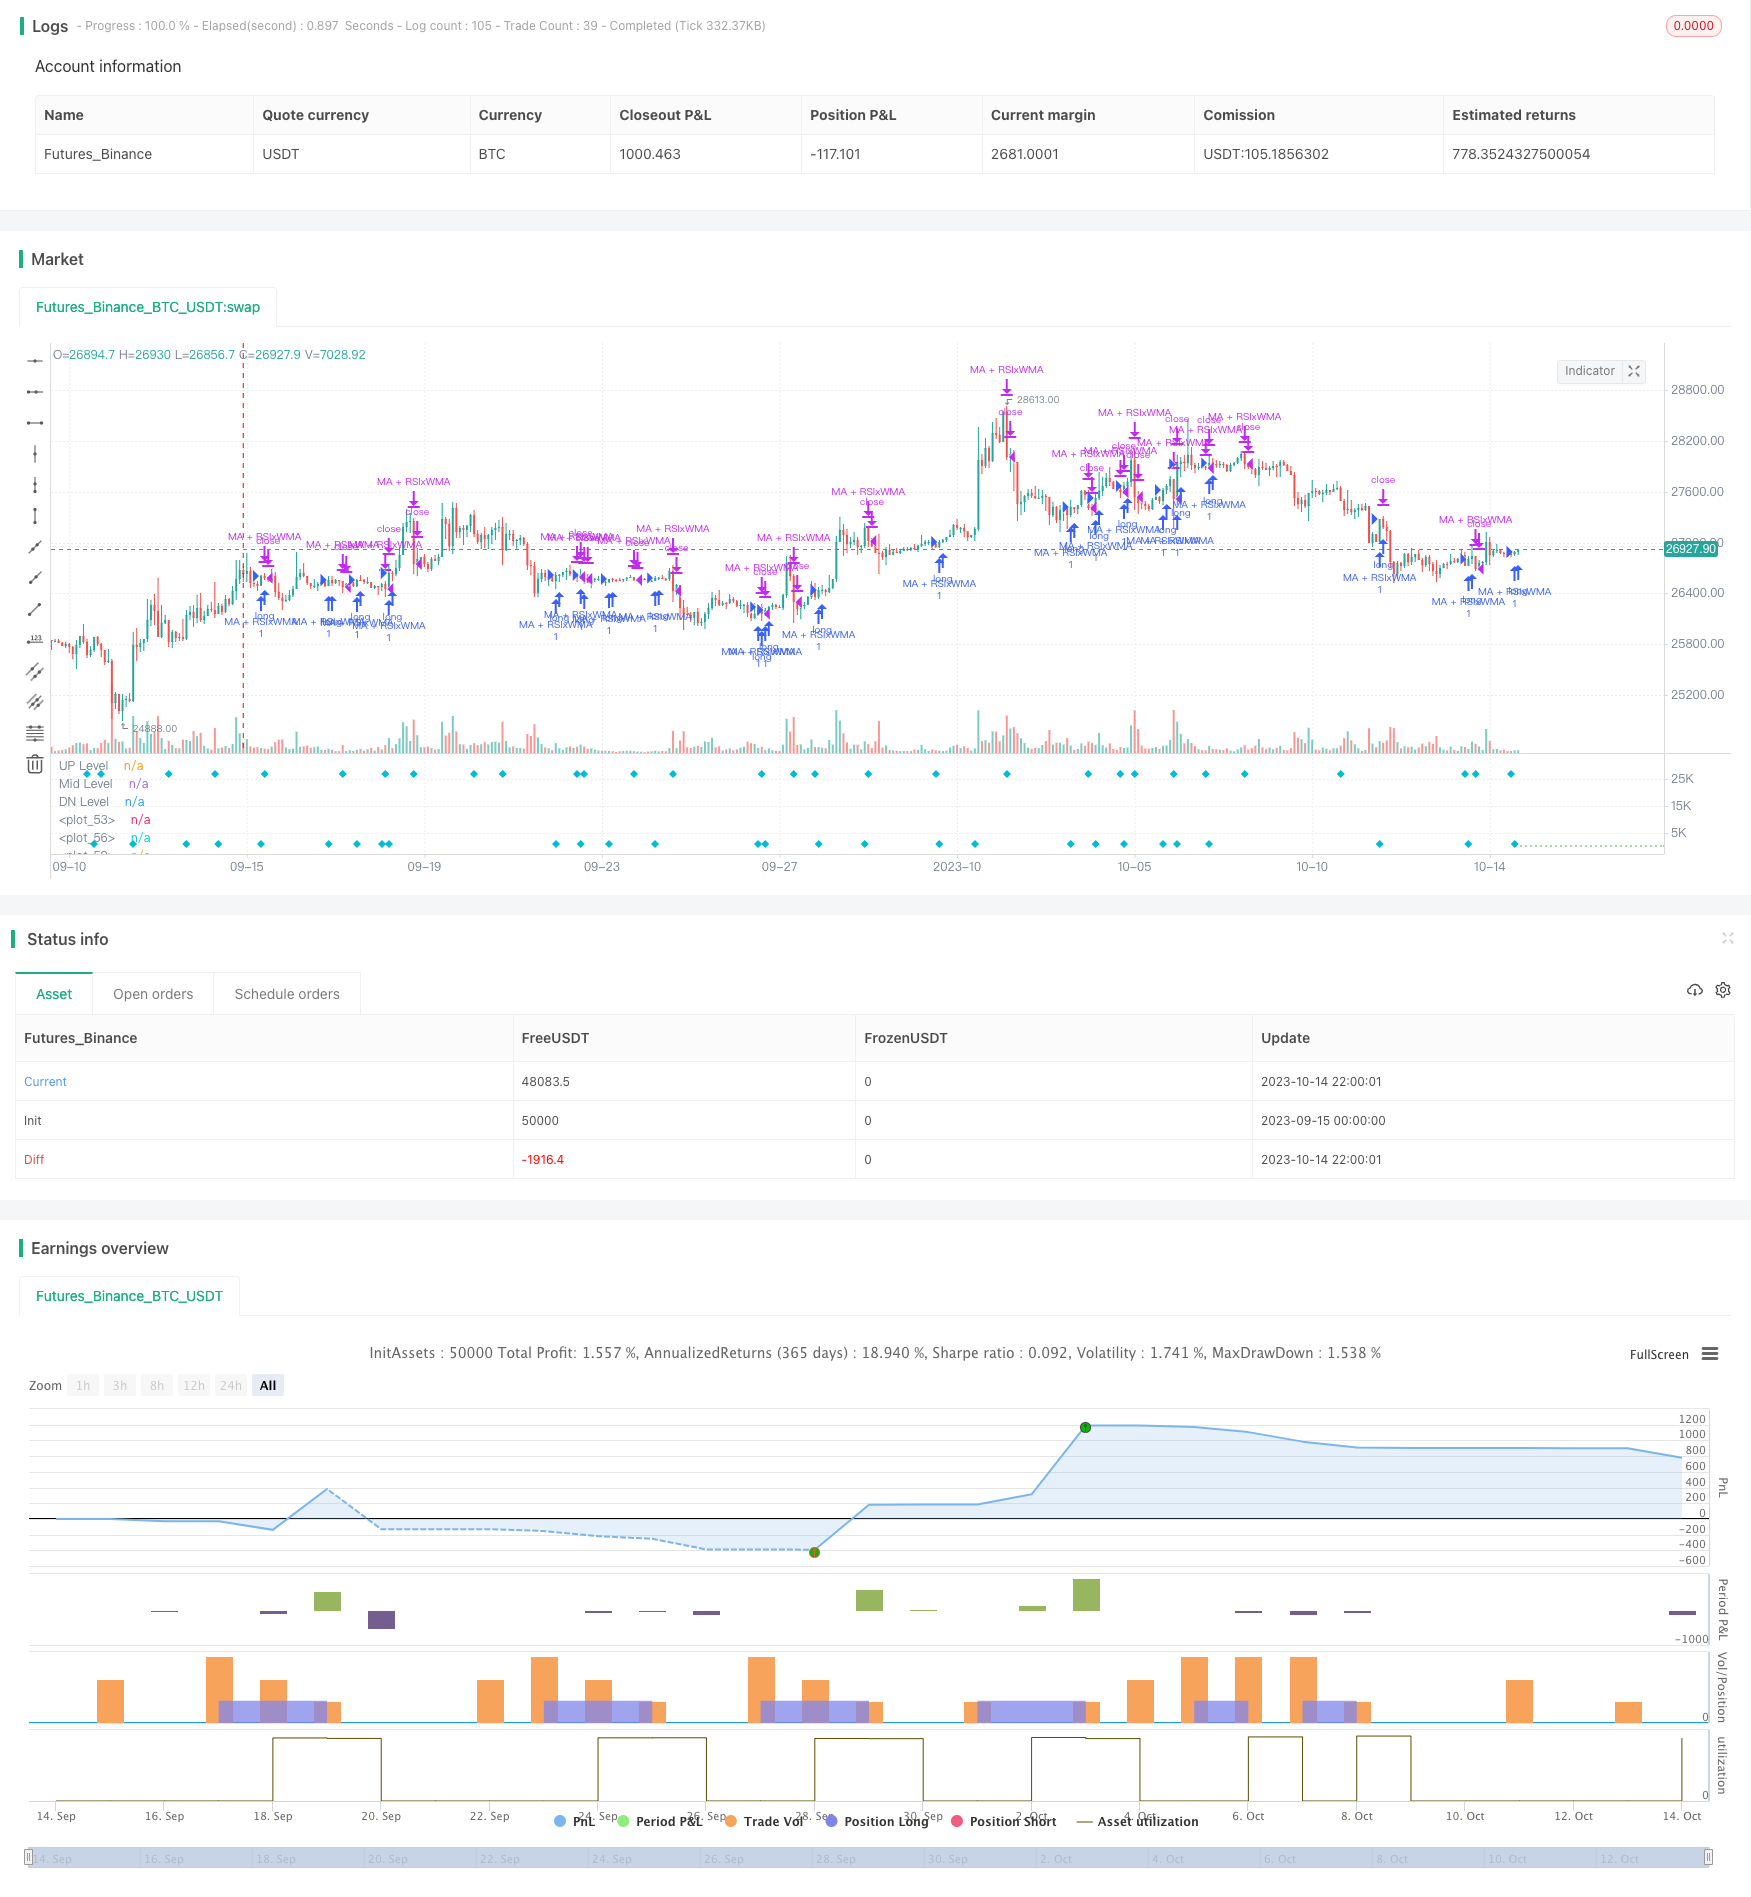
Overview
The core idea of this strategy is to identify trend reversal points by utilizing both Relative Strength Index (RSI) and moving averages of different timeframes, in order to capture mid-to-long term trends while conducting short-term trading. This strategy combines various trading signals in an attempt to improve trading success rate.
Strategy Logic
- Calculate RSI indicator, fast EMA and slow WMA moving averages.
- When RSI line crosses over WMA line, buy/sell signals are generated.
- When faster EMA crosses over slower WMA, buy/sell signals are generated.
- When both RSI and EMA cross over WMA simultaneously, strong buy/sell signals are generated.
- Additionally, when price crosses over auxiliary moving average lines, it strengthens the main signal.
- Set stop loss and take profit parameters.
This strategy combines breakout signals from multiple technical indicators and moving averages of different timeframes to identify trends of different periods, thereby improving reliability. RSI identifies overbought/oversold levels, EMA determines short-term trend, WMA determines medium-term trend, while price crossover with auxiliary moving averages verifies the trend. The combination of multiple signals enhances strategy performance.
Advantage Analysis
- Utilize RSI's reversal characteristic to capture reversal opportunities in overbought/oversold zones.
- Auxiliary moving averages act as trend filter to avoid false breakouts.
- Multi-timeframe combination enables tracking long-term trends while capturing short-term opportunities.
- Combining multiple indicator signals can improve trading success rate.
- Stop loss and take profit allows actively managing risks.
Risk Analysis
- RSI can generate false signals, needs filtering with moving averages.
- Rebounds under major trends may trigger reverse trade signals, need caution.
- Requires parameter optimization such as RSI period, moving average periods etc.
- Stop loss placement needs prudence to avoid being stopped out prematurely.
Risks can be mitigated through parameter optimization, strict stop loss strategy, and consideration of major trends etc.
Optimization Directions
- Optimize RSI parameters to find optimal period length.
- Test different moving average combinations.
- Incorporate volatility index like ATR for dynamic stop loss/take profit.
- Add position sizing and risk management modules.
- Utilize machine learning for parameter optimization and signal quality evaluation.
Summary
This strategy integrates trend following and extreme reversal trading ideas, adds multi-timeframe analysis and synthesized indicators, aiming to improve trading success rate. Key is to control risk, optimize parameters, and consider impacts of major trends. Overall this is a practical strategy with strong adaptability. More advanced techniques can be used to further improve strategy quality.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | RSI Value) |
| v_input_2 | 9 | Length: |
| v_input_3 | 50 | Level: |
| v_input_4 | true | RSI) |
| v_input_5 | 70 | O-BOUGHT |
| v_input_6 | 30 | O-SOLD |
| v_input_7 | true | Price-MA) |
| v_input_8 | 0 | Type: EMA | SMA | WMA | VWMA |
| v_input_9 | 3 | Length |
| v_input_10 | true | Trending-MA) |
| v_input_11 | 0 | ma_type2: WMA | SMA | EMA | VWMA |
| v_input_12 | 21 | Length |
| v_input_25 | true | TP-SL |
| v_input_26 | 3 | SL % |
| v_input_27 | 15 | TP % |
| v_input_13 | timestamp(01 Jan 2021 00:00 +0000) | (?Backtest Time Period)Start Time |
| v_input_14 | timestamp(01 Jan 2200 00:00 +0000) | End Time |
| v_input_15 | false | (?? ? --- Backtesting Signals Type --- ? )RSI x Trending-MA |
| v_input_16 | false | MA x Trendin-MA |
| v_input_17 | false | RSI + EMA x Trending-MA |
| v_input_18 | false | Trending-MA x 50 |
| v_input_19 | false | RSI x 50 |
| v_input_20 | false | RSI OS/OB x Trending-MA |
| v_input_21 | false | RSI Over Sold/Bought |
| v_input_22 | true | (?With MA)With MA Signal) |
| v_input_23 | 0 | withMA_type: SMA | EMA | WMA | VWMA |
| v_input_24 | 9 | with_MALen |
| v_input_28 | true | MA + RSI x Trending-MA |
Source Pine Script
/*backtest
start: 2023-09-15 00:00:00
end: 2023-10-15 00:00:00
period: 2h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © HamidBox

//@version=4
// strategy("H-M By HamidBox-YT", default_qty_type=strategy.cash, default_qty_value= 100, initial_capital=100, currency='USD', commission_type=strategy.commission.percent, commission_value=0.1)

ma(source, length, type) =>
    type == "SMA" ? sma(source , length)    :
     type == "EMA" ? ema(source , length)   :
     type == "WMA" ? wma(source , length)   :
     type == "VWMA" ? vwma(source , length) :
     na
WMA(source, length, type) =>
    type == "SMA" ? sma(source , length)    :
     type == "EMA" ? ema(source , length)   :
     type == "WMA" ? wma(source , length)   :
     type == "VWMA" ? vwma(source , length) :
     na

WithMA(source, length, type) =>
    type == "SMA" ? sma(source , length)    :
     type == "EMA" ? ema(source , length)   :
     type == "WMA" ? wma(source , length)   :
     type == "VWMA" ? vwma(source , length) :
     na


rsi_inline      = input(true , title="RSI Value)", inline="rsi")
rsiLength       = input(title="Length:", type=input.integer, defval=9, minval=1, inline="rsi")
rsiLineM        = input(title="Level:", type=input.integer, defval=50, minval=1, inline="rsi")

rsi_OSOBinline  = input(true , title="RSI)", inline="rsiosob")
rsiLineU        = input(title="O-BOUGHT", type=input.integer, defval=70, minval=1, inline="rsiosob")
rsiLineD        = input(title="O-SOLD", type=input.integer, defval=30, minval=1, inline="rsiosob")

ma_inline       = input(true , title="Price-MA)", inline="ma")
ma_type         = input(title="Type", defval="EMA", options=["EMA","SMA","WMA","VWMA"], inline="ma")
emaLength       = input(title="Length", type=input.integer, defval=3, inline="ma")

wma_inline      = input(true , title="Trending-MA)", inline="wma")
ma_type2        = input(title="", defval="WMA", options=["EMA","SMA","WMA","VWMA"], inline="wma")
wmaLength       = input(title="Length", type=input.integer, defval=21, inline="wma")


////////////////////////////////////////////////////////////////////////////////
startTime       = input(title="Start Time", type = input.time, defval = timestamp("01 Jan 2021 00:00 +0000"), group="Backtest Time Period")
endTime         = input(title="End Time", type = input.time, defval = timestamp("01 Jan 2200 00:00 +0000"), group="Backtest Time Period")
inDateRange     = true

////////////////////////////////////////////////////////////////////////////////

rsi         = rsi(close , rsiLength)
r           = plot(rsi_inline ? rsi : na, color=color.yellow, linewidth=2)

EMA         = ma(rsi, emaLength, ma_type)
e           = plot(ma_inline ? EMA : na, color=color.lime)

myWMA       = ma(rsi, wmaLength, ma_type2)
w           = plot(wma_inline ? myWMA : na, color=color.white, linewidth=2)


up  = hline(rsiLineU, title='UP Level', linewidth=1, color=color.red, linestyle=hline.style_dotted)
mid = hline(rsiLineM, title='Mid Level', linewidth=2, color=color.white, linestyle=hline.style_dotted)
dn  = hline(rsiLineD, title='DN Level', linewidth=1, color=color.green, linestyle=hline.style_dotted)

col_e_w = EMA > myWMA  ? color.new(color.green , 85) : color.new(color.red , 85)
col_r_w = rsi > myWMA  ? color.new(color.green , 85) : color.new(color.red , 85)

fill(e , w, color=col_e_w)
fill(r , w, color=col_r_w)

////////////////////////////////////////////////////////////////////////////////

//Signals     = input(true,group="? ? --- Backtesting Signals Type --- ? ")

///////////////////////////////////////////////////////////////////////////////
RSI_Cross   = input(false, "RSI x Trending-MA", inline="wma_cross",group="? ? --- Backtesting Signals Type --- ? ")      // INPUT

rsiBuySignal    = crossover(rsi , myWMA)
plotshape(RSI_Cross ? rsiBuySignal : na, title="RSI Crossover", style=shape.labelup, location=location.bottom, color=color.green)

rsiSellSignal   = crossunder(rsi , myWMA)
plotshape(RSI_Cross ? rsiSellSignal : na, title="RSI Crossunder", style=shape.labeldown, location=location.top, color=color.red)

if rsiBuySignal and RSI_Cross and inDateRange
    strategy.entry("RSIxWMA", strategy.long)
if rsiSellSignal and RSI_Cross and inDateRange
    strategy.close("RSIxWMA", comment="x")
if (not inDateRange)
    strategy.close_all()

////////////////////////////////////////////////////////////////////////////////

MA_Cross    = input(false, "MA x Trendin-MA",group="? ? --- Backtesting Signals Type --- ? ")       // INPUT

maBuySignal     = crossover(EMA, myWMA)
plotshape(MA_Cross ? maBuySignal : na, title="MA Cross", style=shape.circle, location=location.bottom, color=color.lime)

maSellSignal   = crossunder(EMA , myWMA)
plotshape(MA_Cross ? maSellSignal : na, title="RSI Crossunder", style=shape.circle, location=location.top, color=color.maroon)

if maBuySignal and MA_Cross and inDateRange
    strategy.entry("MAxWMA", strategy.long)
if maSellSignal and MA_Cross and inDateRange
    strategy.close("MAxWMA", comment="x")
if (not inDateRange)
    strategy.close_all()

////////////////////////////////////////////////////////////////////////////////

Mix         = input(false, "RSI + EMA x Trending-MA",group="? ? --- Backtesting Signals Type --- ? ")       // INPUT

rsi_ma_buy  = crossover(rsi , myWMA) and crossover(EMA, myWMA)
rsi_ma_sell = crossunder(rsi , myWMA) and crossunder(EMA, myWMA)

plotshape(Mix ? rsi_ma_buy : na, title="RSI Crossunder", style=shape.circle, location=location.bottom, color=color.lime, size=size.tiny)
plotshape(Mix ? rsi_ma_sell : na, title="RSI Crossunder", style=shape.circle, location=location.top, color=color.yellow, size=size.tiny)

if rsi_ma_buy and Mix and inDateRange
    strategy.entry("RSI+EMA x WMA", strategy.long)
if rsi_ma_sell and Mix and inDateRange
    strategy.close("RSI+EMA x WMA", comment="x")
if (not inDateRange)
    strategy.close_all()

////////////////////////////////////////////////////////////////////////////////
wma_cross       = input(false, "Trending-MA x 50",group="? ? --- Backtesting Signals Type --- ? ")       // INPUT

wma_buy         = crossover(myWMA , rsiLineM)
plotshape(wma_cross ? wma_buy : na, title="WMA Cross", style=shape.diamond, location=location.bottom, color=color.aqua)
wma_sell        = crossunder(myWMA , rsiLineM)
plotshape(wma_cross ? wma_sell : na, title="WMA Cross", style=shape.diamond, location=location.top, color=color.aqua)

if wma_buy and wma_cross and inDateRange
    strategy.entry("WMA x 50", strategy.long)
if wma_sell and wma_cross and inDateRange
    strategy.close("WMA x 50", comment="x")
if (not inDateRange)
    strategy.close_all()

////////////////////////////////////////////////////////////////////////////////
rsi_50      = input(false, "RSI x 50",group="? ? --- Backtesting Signals Type --- ? ")       // INPUT

rsi_50_buy      = crossover(rsi , rsiLineM)
plotshape(rsi_50 ? rsi_50_buy : na, title="WMA Cross", style=shape.cross, location=location.bottom, color=color.purple)
rsi_50_sell     = crossunder(rsi , rsiLineM)
plotshape(rsi_50 ? rsi_50_sell : na, title="WMA Cross", style=shape.cross, location=location.top, color=color.purple)

if rsi_50_buy and rsi_50 and inDateRange
    strategy.entry("RSI Cross 50", strategy.long)
if rsi_50_sell and rsi_50 and inDateRange
    strategy.close("RSI Cross 50", comment="x")
if (not inDateRange)
    strategy.close_all()

////////////////////////////////////////////////////////////////////////////////
RSI_OS_OB   = input(false, "RSI OS/OB x Trending-MA",group="? ? --- Backtesting Signals Type --- ? ")       // INPUT

rsi_OB_buy      = (rsi < rsiLineD or rsi[1] < rsiLineD[1] or rsi[2] < rsiLineD[2] or rsi[3] < rsiLineD[3] or rsi[4] < rsiLineD[4] or rsi[5] < rsiLineD[5]) and rsiBuySignal
plotshape(RSI_OS_OB ? rsi_OB_buy : na, title="RSI OB + Cross", style=shape.circle, location=location.bottom, color=color.lime, size=size.tiny)
rsi_OS_sell     = (rsi > rsiLineU or rsi[1] > rsiLineU[1] or rsi[2] > rsiLineU[2] or rsi[3] > rsiLineU[3] or rsi[4] > rsiLineU[4] or rsi[5] > rsiLineU[5]) and maSellSignal
plotshape(RSI_OS_OB ? rsi_OS_sell : na, title="RSI OS + Cross", style=shape.circle, location=location.top, color=color.red, size=size.tiny)

if rsi_OB_buy and RSI_OS_OB and inDateRange
    strategy.entry("RSI-OBOS x WMA", strategy.long)
if rsi_OS_sell and RSI_OS_OB and inDateRange
    strategy.close("RSI-OBOS x WMA", comment="x")
if (not inDateRange)
    strategy.close_all()

////////////////////////////////////////////////////////////////////////////////

rsi_OB_OS       = input(false, "RSI Over Sold/Bought",group="? ? --- Backtesting Signals Type --- ? ")       // INPUT

rsiBuy          = crossover(rsi , rsiLineD)
rsiSell         = crossunder(rsi, rsiLineU)
rsiExit         = crossunder(rsi, rsiLineD)

plotshape(rsi_OB_OS ? rsiBuy : na, title="RSI OB", style=shape.cross, location=location.bottom, color=color.purple)
plotshape(rsi_OB_OS ? crossunder(rsi, rsiLineU) : na, title="RSI OS", style=shape.cross, location=location.top, color=color.purple)
plotshape(rsi_OB_OS ? rsiExit : na, title="RSI OS", style=shape.cross, location=location.bottom, color=color.red)

if rsiBuy and rsi_OB_OS and inDateRange
    strategy.entry("RSI OB", strategy.long)
if (rsiSell or rsiExit) and rsi_OB_OS and inDateRange
    strategy.close("RSI OB", comment="x")
if (not inDateRange)
    strategy.close_all()

////////////////////////////////////////////////////////////////////////////////
////////////////////////////////////////////////////////////////////////////////

With_MA_Vis     = input(true , title="With MA Signal)", inline="WITH MA", group="With MA")
withMA_type     = input(title="", defval="SMA", options=["EMA","SMA","WMA","VWMA"], inline="WITH MA", group="With MA")
with_MALen      = input(title="", defval=9, type=input.integer, inline="WITH MA", group="With MA")

// TAKE-PROFIT / STOP-LOSS
Stop_Take_Vis   = input(true, "TP-SL")
LongSLValue     = input(title="SL %", type=input.float, defval=3, minval=0.5) * 0.01
LongTPValue     = input(title="TP %", type=input.float, defval=15, minval=0.5) * 0.01

LongSLDetermine = strategy.position_avg_price * (1 - LongSLValue)
LongTPDetermine = strategy.position_avg_price * (1 + LongTPValue)
//////////////////////////

with_ma     = WithMA(close, with_MALen, withMA_type)

Close_buy_MA    = crossover(close , with_ma)
Close_sell_MA   = crossunder(close , with_ma)

// PLOT OPTION
WithMaSignal    = input(true, "MA + RSI x Trending-MA",group="With MA")       // INPUT

// CONDITION IN VARIABLE
withMA_RSI_BUY  = (Close_buy_MA and rsiBuySignal) and WithMaSignal and inDateRange
withMA_RSI_SELL = (Close_sell_MA and rsiSellSignal) and WithMaSignal and inDateRange

// PLOT ING
plotshape(WithMaSignal ? withMA_RSI_BUY : na, title="With MA", style=shape.diamond, location=location.bottom, color=color.aqua)
plotshape(WithMaSignal ? withMA_RSI_SELL : na, title="With MA", style=shape.diamond, location=location.top, color=color.aqua)


if withMA_RSI_BUY
    strategy.entry("MA + RSIxWMA", strategy.long)
if withMA_RSI_SELL
    strategy.close("MA + RSIxWMA", comment="x")
if (not inDateRange)
    strategy.close_all()

// FOR SL - TP
if (strategy.position_size > 0) and Stop_Take_Vis
    strategy.exit("BUY", stop=LongSLDetermine, limit=LongTPDetermine)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-10-16. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/RSI-and-Moving-Average-Crossover-Multi-Timeframe-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dual Mode Adaptive Trend Trading Strategy EMA Crossover with ATR Volatility Based Risk Management SystemPine Script · Trend following · 1d
- Dynamic Dual EMA Crossover Strategy with Adaptive Profit Loss ControlPine Script · Trend following · 1d
- Dynamic Signal Line Trend Following and Volatility Filtering StrategyPine Script · Trend following · 1h
- EMA Cross Trend Following Strategy with SMA Stop Loss and Re Entry MechanismPine Script · Trend following · 1h