Strategy vault / Trend following
RSI Based Bullish Trend Following Strategy
This strategy is designed based on the Relative Strength Index (RSI) indicator for buying on RSI low points and taking profit and stop loss on RSI high points. It generates buy signals when RSI drops below the…
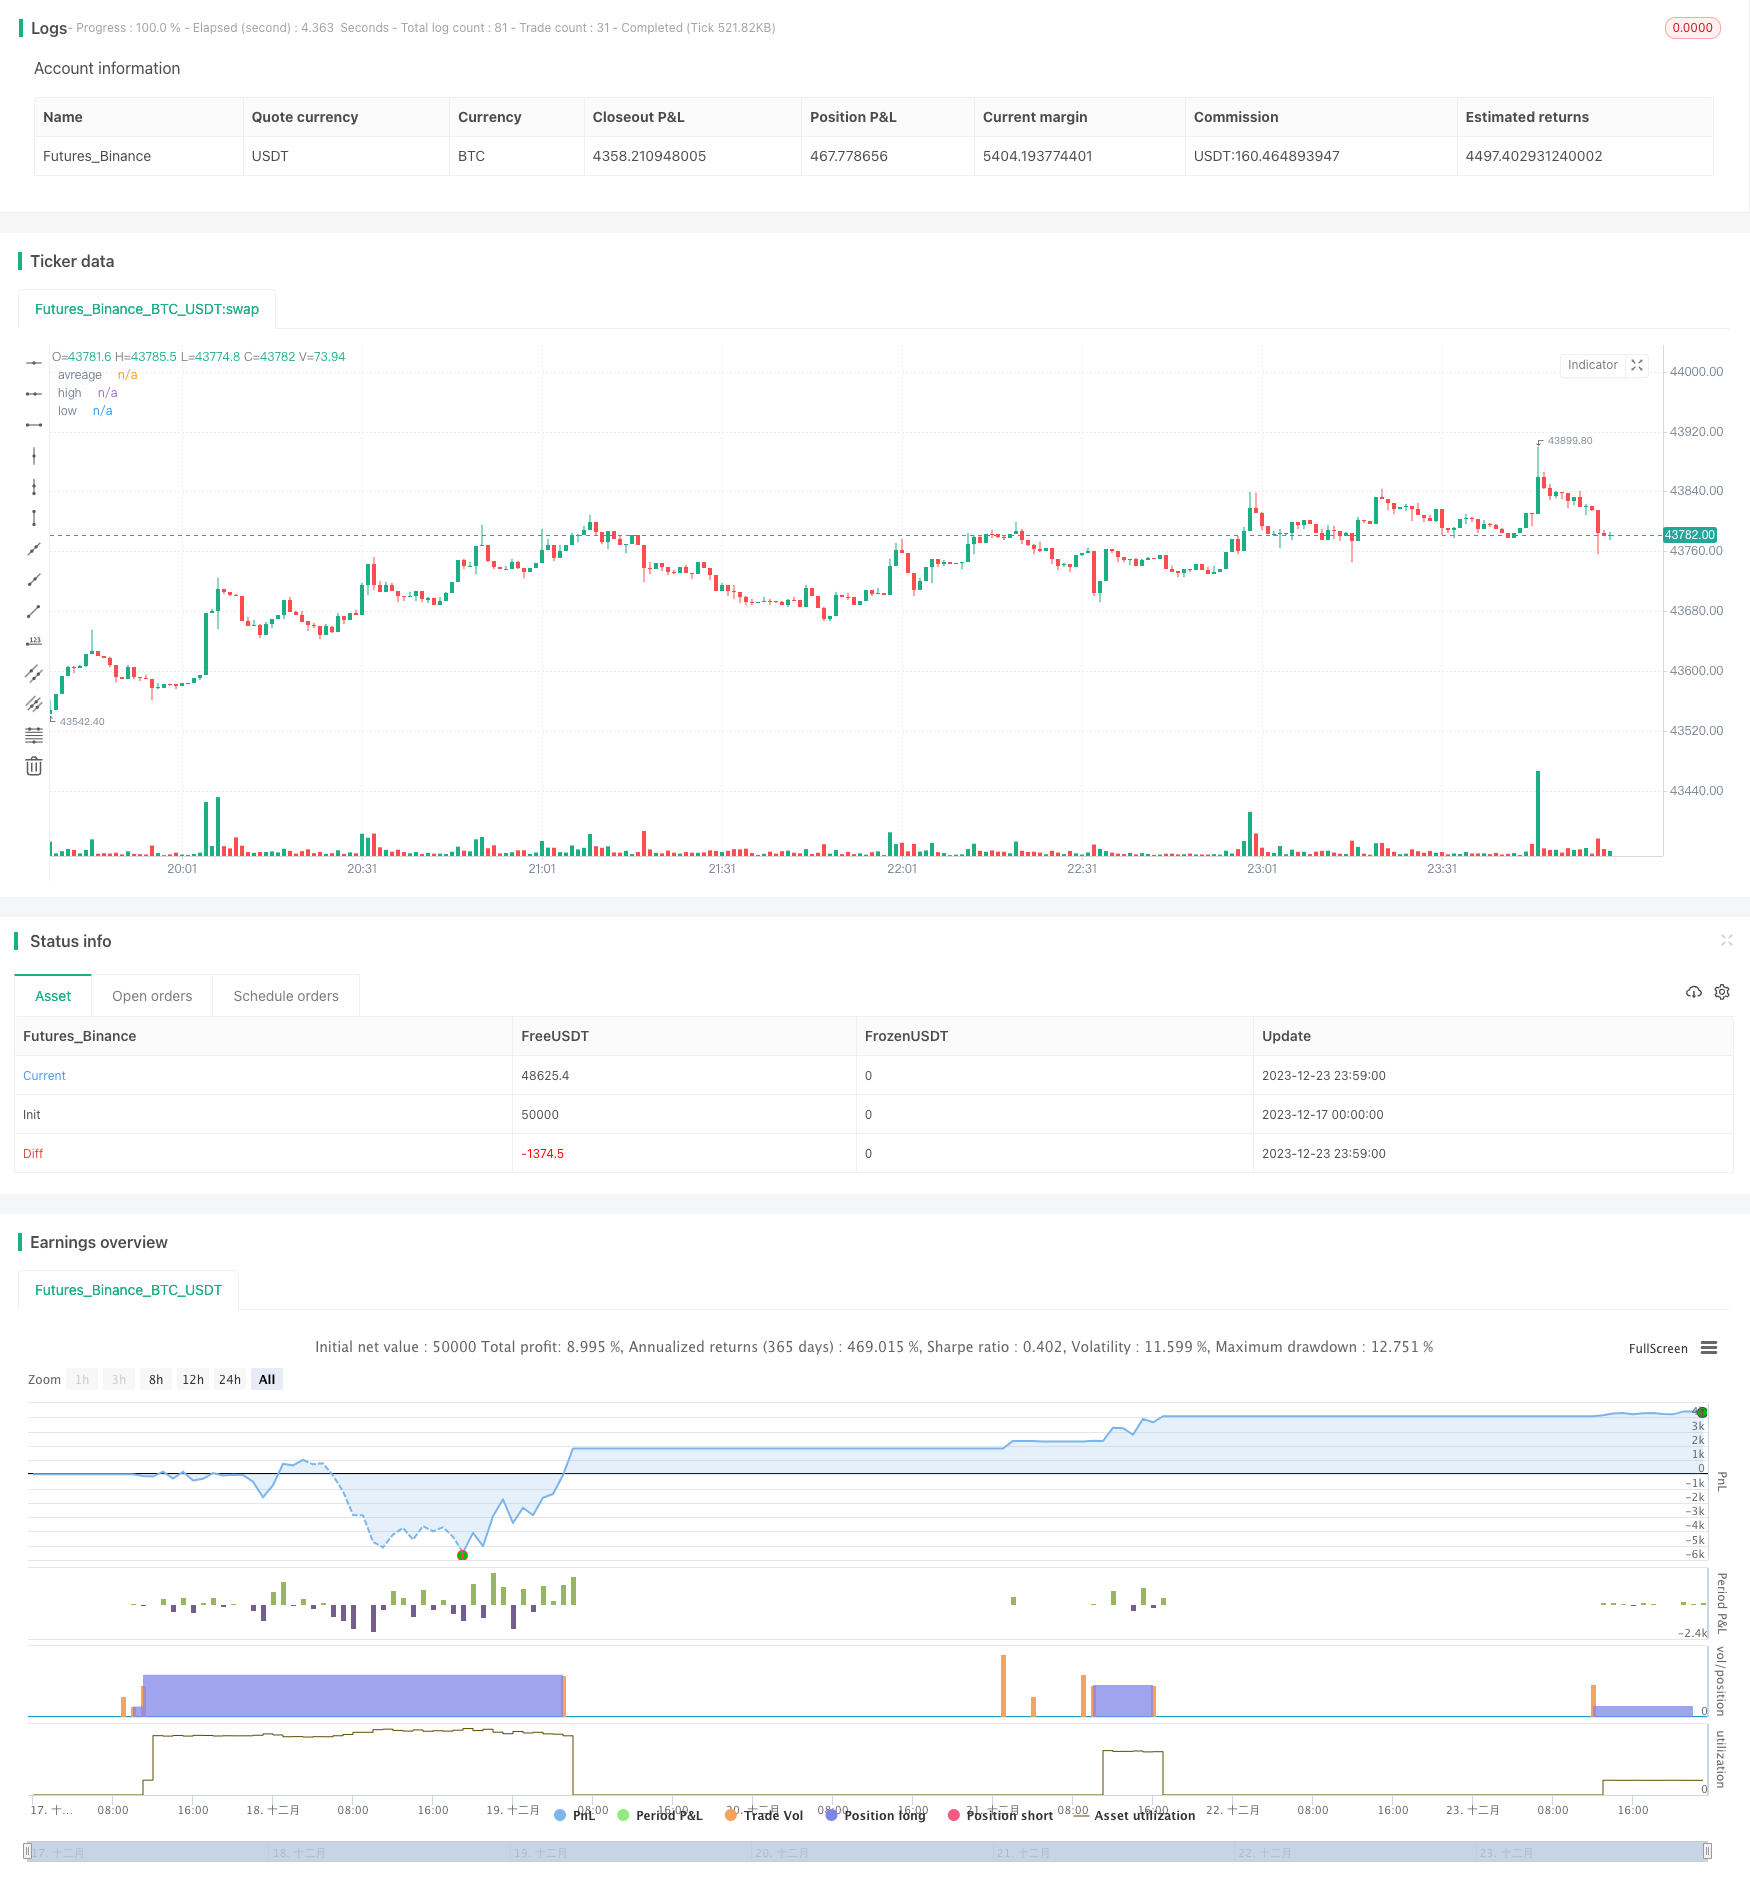
Overview
This strategy is designed based on the Relative Strength Index (RSI) indicator for buying on RSI low points and taking profit and stop loss on RSI high points. It generates buy signals when RSI drops below the oversold line and sell signals when RSI rises above the overbought line. The strategy is optimized to track trends with effective risk control.
Strategy Logic
The strategy uses the RSI indicator to determine if a stock is overvalued or undervalued. RSI combined with overbought and oversold lines forms buy and sell signals. Specifically, if RSI crosses above the 20 oversold line, a buy signal is generated; if RSI crosses below the 80 overbought line, a sell signal is generated.
After entering a long position, the strategy sets an initial stop loss to control the downside risk. At the same time, two take profit lines with different ratios are set to take profits in batches and lock in profits. Specifically, 50% of the position will take profit first at 3% above the entry price; then the remaining 50% position will take profit at 5% above the entry price.
The strategy effectively utilizes the RSI indicator to determine entry timing. The stop loss and take profit settings are reasonable to effectively control risks.
Advantages
- Utilize RSI indicator to determine long/short positions and avoid trading blindly
- Optimized RSI parameters for better indicator effect
- Reasonable dual take profit design allows taking profits in batches to lock in more profits
- Initial stop loss and trailing stop loss prevent huge losses
Risks
- Poor performance in a bull market that cannot sustain profits
- Probability of incorrect signals from RSI exists and can increase losses from improper signal judgement
- Risk that stops cannot be triggered if stop loss points are set too deep
- Risk of magnified losses without limit on pyramiding times and ratio
Improvements
- Add other indicators to filter RSI signals and improve accuracy
- Set limits on pyramiding times and ratios
- Test effects of different RSI parameters
- Optimize stop loss and take profit points to lower risks
Summary
The strategy utilizes RSI to judge market condition and has reasonable stop loss and take profit configuration. It can effectively determine market trend and control trading risks, suitable as a bullish trend following strategy. Signal filtering, parameter testing, stop loss optimization etc. can further improve the stability of the strategy.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_string_1 | 0 | Strategy Direction: long | short | all |
| v_input_1 | 21 | length |
| v_input_2 | 20 | overSold |
| v_input_3 | 80 | overBought |
| v_input_4 | true | Display info panels? |
| v_input_5 | 40 | fibs label offset |
| v_input_string_2 | 0 | fibs label size: size.normal | size.small | size.tiny | size.large | size.huge |
| v_input_6 | false | trend |
| v_input_float_1 | 5 | stop loss |
| v_input_int_1 | 50 | qty_percent1 |
| v_input_int_2 | 50 | qty_percent2 |
| v_input_float_2 | 3 | Take profit1 |
| v_input_float_3 | 5 | Take profit2 |
Source Pine Script
/*backtest
start: 2023-12-17 00:00:00
end: 2023-12-24 00:00:00
period: 1m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/

//@version=5

strategy(title='RSI Long Strategy', overlay=true, pyramiding=5, initial_capital=10000, default_qty_type=strategy.percent_of_equity, default_qty_value=100, calc_on_order_fills=false, slippage=0, commission_type=strategy.commission.percent, commission_value=0.075)
strat_dir_input = input.string(title='Strategy Direction', defval='long', options=['long', 'short', 'all'])
strat_dir_value = strat_dir_input == 'long' ? strategy.direction.long : strat_dir_input == 'short' ? strategy.direction.short : strategy.direction.all
strategy.risk.allow_entry_in(strat_dir_value)
//INPUTS


length = input(21)
overSold = input(20)
overBought = input(80)
p = close

vrsi = ta.rsi(p, length)
price = close
var bool long = na
var bool short = na

long := ta.crossover(vrsi, overSold)
short := ta.crossunder(vrsi, overBought)

var float last_open_long = na
var float last_open_short = na

last_open_long := long ? close : nz(last_open_long[1])
last_open_short := short ? close : nz(last_open_short[1])
mpoint=(last_open_long+last_open_short)/2

entry_value = last_open_long
entry_value1 = last_open_short

// Rounding levels to min tick
nround(x) =>
    n = math.round(x / syminfo.mintick) * syminfo.mintick
    n
//
disp_panels = input(true, title='Display info panels?')
fibs_label_off = input(40, title='fibs label offset')
fibs_label_size = input.string(size.normal, options=[size.tiny, size.small, size.normal, size.large, size.huge], title='fibs label size')
r1_x = timenow + math.round(ta.change(time) * fibs_label_off)
r1_y = last_open_short
text1 = 'High : ' + str.tostring(nround(last_open_short))
s1_y = last_open_long
text3 = 'low : ' + str.tostring(nround(last_open_long))

R1_label = disp_panels ? label.new(x=r1_x, y=r1_y, text=text1, xloc=xloc.bar_time, yloc=yloc.price, color=color.orange, style=label.style_label_down, textcolor=color.black, size=fibs_label_size) : na
S1_label = disp_panels ? label.new(x=r1_x, y=s1_y, text=text3, xloc=xloc.bar_time, yloc=yloc.price, color=color.lime, style=label.style_label_up, textcolor=color.black, size=fibs_label_size) : na

label.delete(R1_label[1])
label.delete(S1_label[1])
//
plot(mpoint, title='avreage', color=color.new(color.red, 40), style=plot.style_linebr, linewidth=3, trackprice=true, offset=-9999)
plot(last_open_short, title='high', color=color.new(color.red, 40), style=plot.style_linebr, linewidth=3, trackprice=true, offset=-9999)
plot(last_open_long, title='low', color=color.new(color.blue, 40), style=plot.style_linebr, linewidth=3, trackprice=true, offset=-9999)
//
trend = input(false)
if barstate.islast and trend == true
    line z = line.new(bar_index[1], last_open_short[1], bar_index, last_open_short, extend=extend.both, color=color.red, style=line.style_dashed, width=1)
    line f = line.new(bar_index[1], mpoint[1], bar_index, mpoint, extend=extend.both, color=color.blue, style=line.style_dashed, width=1)
    line w = line.new(bar_index[1], last_open_long[1], bar_index, last_open_long, extend=extend.both, color=color.green, style=line.style_dashed, width=1)
    line.delete(z[1])
    line.delete(f[1])
    line.delete(w[1])

//bu = ta.crossover(close, mpoint)
//sz = ta.crossunder(close, mpoint)
//bu1 = ta.crossover(close, last_open_short)
sz1 = ta.crossunder(close, last_open_short)
bu2 = ta.crossover(close, last_open_long)
//sz2 = ta.crossunder(close, last_open_long)
//plotshape(sz, style=shape.triangledown, location=location.abovebar, color=color.new(color.orange, 0), size=size.tiny)
//plotshape(bu, style=shape.triangleup, location=location.belowbar, color=color.new(color.blue, 0), size=size.tiny)
//plotshape(sz1, style=shape.triangledown, location=location.abovebar, color=color.new(color.red, 0), size=size.tiny)
//plotshape(bu1, style=shape.triangleup, location=location.belowbar, color=color.new(color.green, 0), size=size.tiny)
//plotshape(sz2, style=shape.triangledown, location=location.abovebar, color=color.new(color.red, 0), size=size.tiny)
//plotshape(bu2, style=shape.triangleup, location=location.belowbar, color=color.new(color.green, 0), size=size.tiny)

l = bu2
s = sz1
if l
    strategy.entry('buy', strategy.long)
if s
    strategy.entry('sell', strategy.short)
per(pcnt) =>
    strategy.position_size != 0 ? math.round(pcnt / 100 * strategy.position_avg_price / syminfo.mintick) : float(na)
stoploss = input.float(title=' stop loss', defval=5, minval=0.01)
los = per(stoploss)
q1 = input.int(title=' qty_percent1', defval=50, minval=1)
q2 = input.int(title=' qty_percent2', defval=50, minval=1)
tp1 = input.float(title=' Take profit1', defval=3, minval=0.01)
tp2 = input.float(title=' Take profit2', defval=5, minval=0.01)
//tp4 = input.float(title=' Take profit4', defval=5, minval=0.01)
strategy.exit('x1', qty_percent=q1, profit=per(tp1), loss=los)
strategy.exit('x2', qty_percent=q2, profit=per(tp2), loss=los)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-25. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/RSI-Based-Bullish-Trend-Following-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive ATR and RSI Trend Following Strategy with Trailing Stop LossPine Script · Trend following · 1h
- Adaptive Price Crossing Moving Average Trading StrategyPine Script · Trend following · 1d
- Adaptive Trading Strategy Based on Stochastic RSI Dual Line CrossoverPine Script · Trend following · 4h
- Advanced Multi Indicator Multi Dimensional Trend Cross Quantitative StrategyPine Script · Trend following · 3h
- Advanced Supertrend Indicator Trading Mechanism Optimization StrategyPine Script · Trend following · 1d
- BB Percentage Index Trend Fading StrategyPine Script · Trend following · 1h