Strategy vault / Trend following
RSI MACD Crossover Double MA Tracking Strategy
This strategy combines RSI indicator, MACD indicator and double moving averages to achieve trend tracking and positioning effects in volatility market. It uses RSI indicator to judge overbought and oversold…
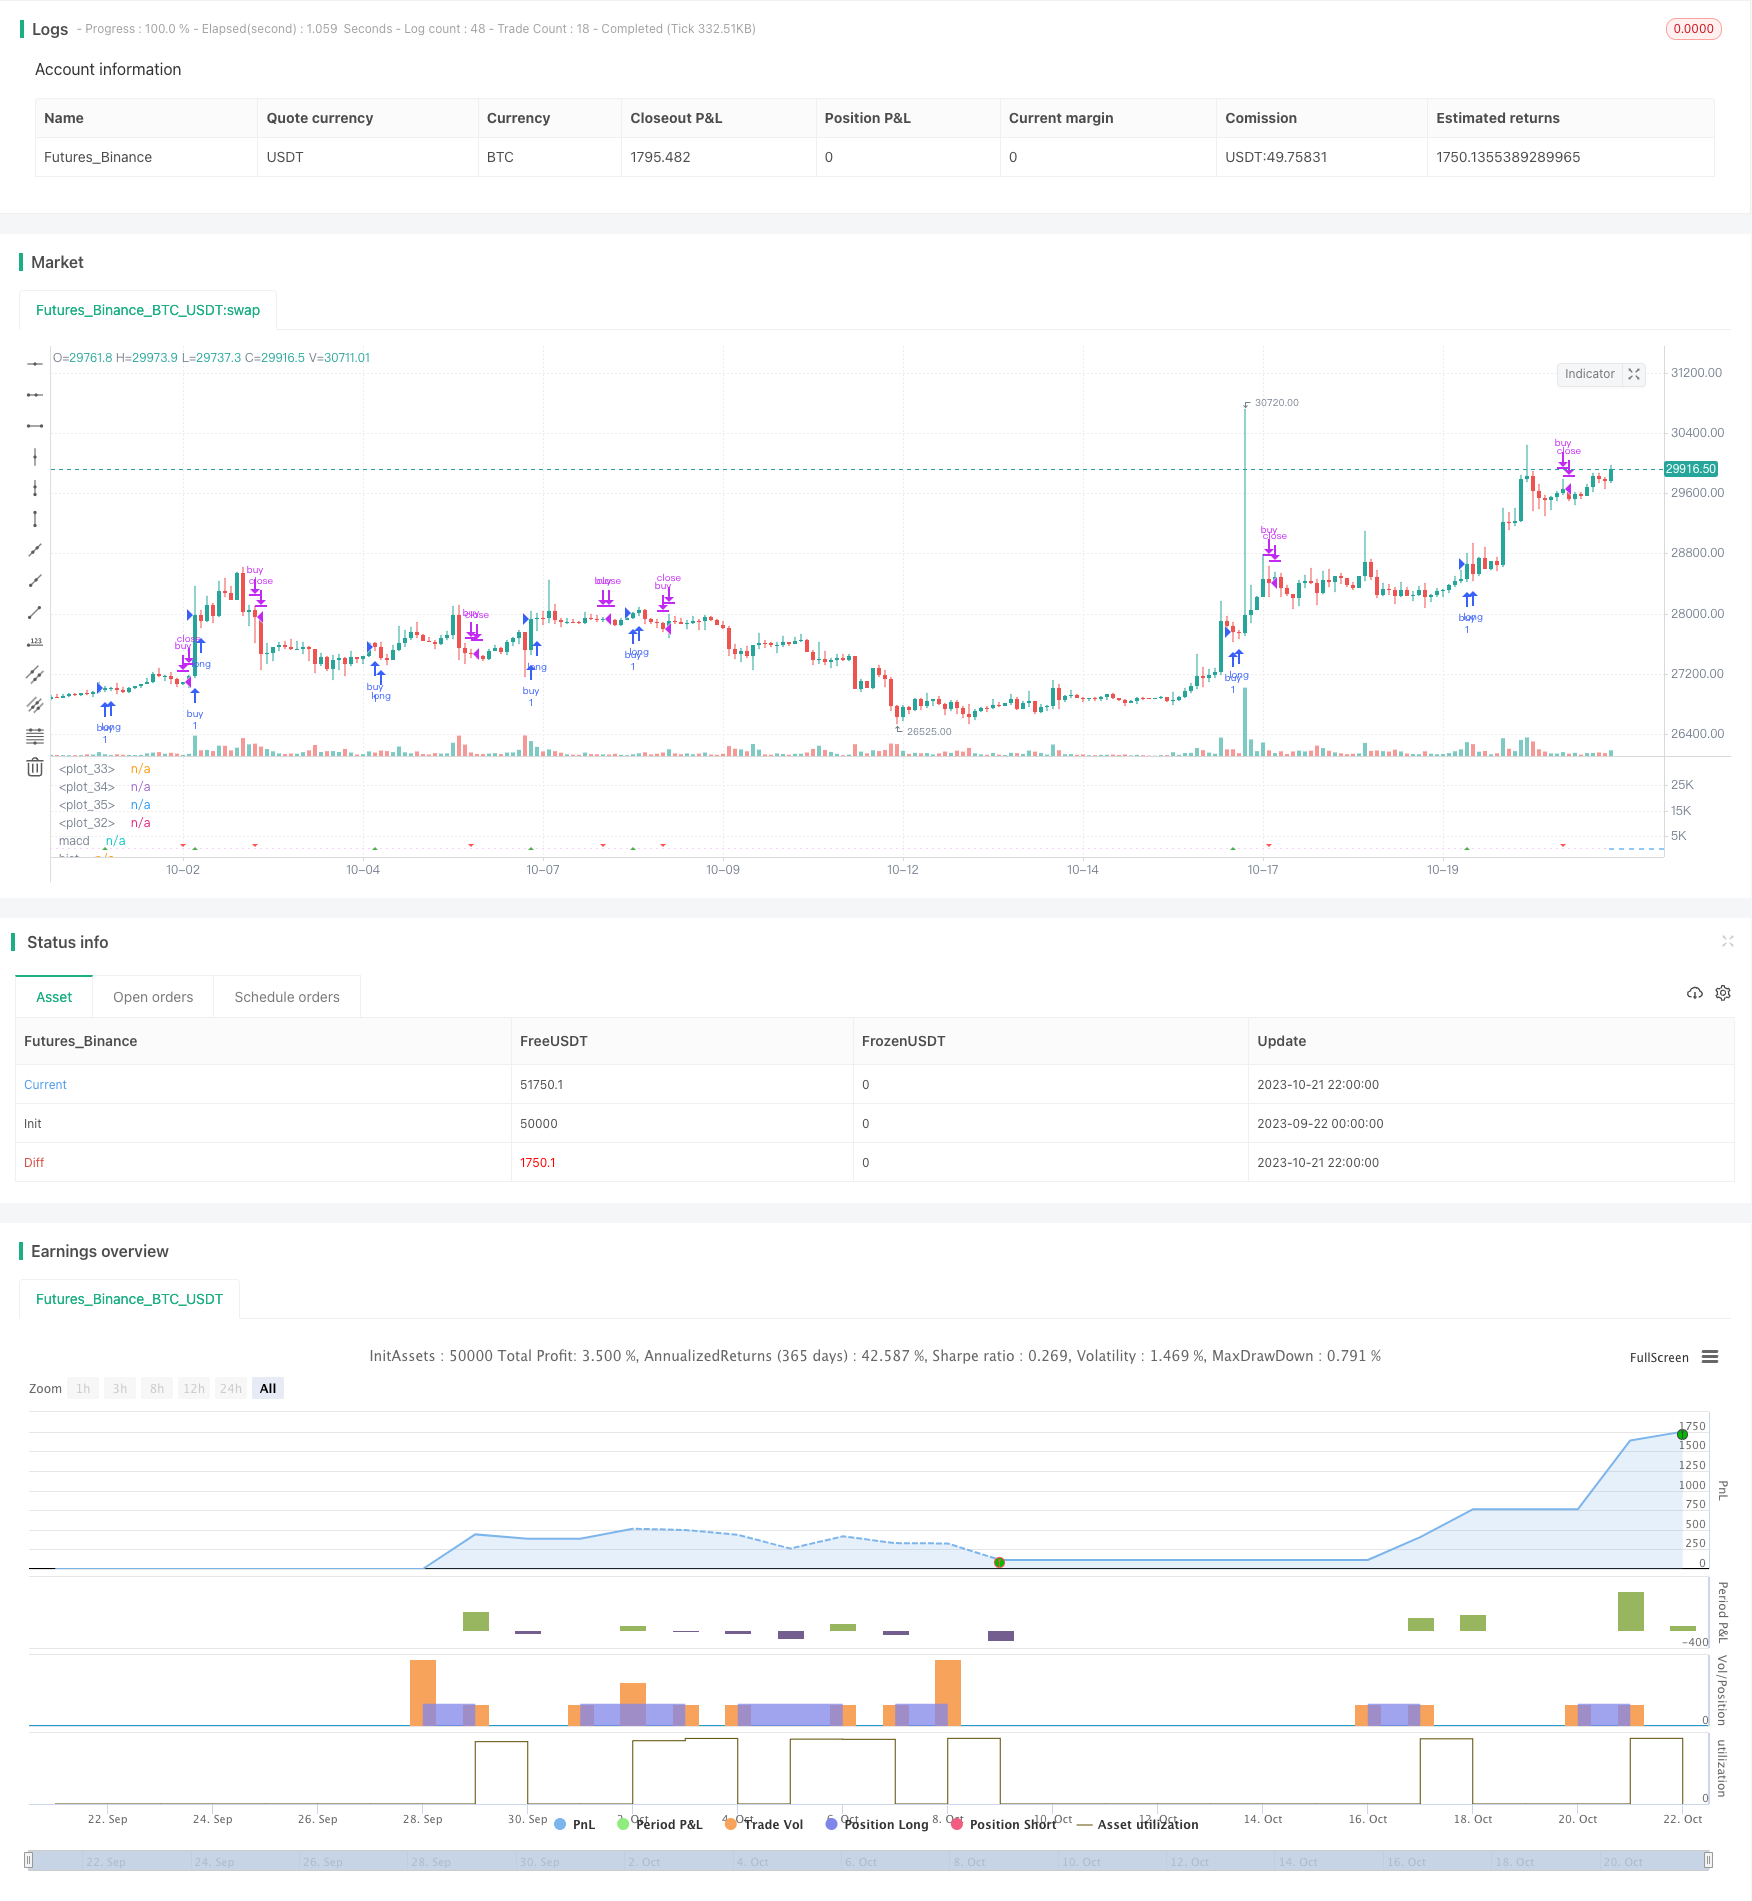
Overview
This strategy combines RSI indicator, MACD indicator and double moving averages to achieve trend tracking and positioning effects in volatility market. It uses RSI indicator to judge overbought and oversold conditions, MACD to determine entry and exit points with fast and slow MA crossover, and double MAs to filter out some noisy trading opportunities during the trend.
Strategy Logic
- Calculate RSI indicator for overbought and oversold
Calculate price change uptrend and downtrend
Compute RSI based on the price change
Determine overbought and oversold levels
- Calculate MACD for crossover
Compute fast MA, slow MA and signal line
Enter long on golden cross and exit on death cross
Plot the crossover situations
- Implement double MA filter
Compute fast and slow moving averages
Only consider trading when fast MA crosses above slow MA
Filter noise and follow the trend
- Combine indicators for entry
Filter entry signal with RSI, MACD and double MA
Improve accuracy and stability of strategy
Advantage Analysis
Combination of multiple indicators improves accuracy
Trend following filters noise and enhances stability
RSI spots potential reversal points
MACD crossover provides simple entry and exit signals
Double MA removes most countertrend trades
Easy to understand with few parameters, good for learning
Risk Analysis
Risk of overfitting with multiple indicators
Double MA sacrifices flexibility and may miss chances
RSI and MACD parameters need careful selection
Pay attention to stop loss based on symbol
Requires periodic re-tuning of parameters
Optimization Directions
Adjust RSI parameters for different symbols
Optimize double MA periods for better tracking
Add stop loss to control single trade loss
Incorporate more indicators to enrich combo
Develop adaptive parameter model for auto-tuning
Summary
This strategy combines RSI, MACD and double MA to identify and track trends, and filters signals through multiple layers. It is very suitable for beginners to learn and improve. The advantage lies in its simplicity and adaptiveness. Fine tuning of parameters can generate decent steady returns. Next steps may include adding more indicators, developing adaptive parameter model to auto optimize for different market environments.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 2017 | Backtest Start Year |
| v_input_2 | true | Backtest Start Month |
| v_input_3 | 2 | Backtest Start Day |
| v_input_4 | 2019 | Backtest Stop Year |
| v_input_5 | 7 | Backtest Stop Month |
| v_input_6 | 30 | Backtest Stop Day |
| v_input_7 | true | Color Background? |
| v_input_8 | 14 | Length |
| v_input_9 | 9 | Fast Length |
| v_input_10 | 72 | Slow Length |
| v_input_11 | 9 | Signal Length |
| v_input_12 | 234 | Control MA |
| v_input_13 | true | Buy on crossover control MA? |
Source Pine Script
/*backtest
start: 2023-09-22 00:00:00
end: 2023-10-22 00:00:00
period: 2h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3

// strategy(title="RSI MACD", precision = 6, pyramiding = 1, default_qty_type = strategy.percent_of_equity, default_qty_value = 99, commission_type = strategy.commission.percent, commission_value = 0.25, initial_capital = 1000)

// Component Code Start
// Example usage:
// if testPeriod()
//   strategy.entry("LE", strategy.long)
testStartYear = input(2017, "Backtest Start Year")
testStartMonth = input(01, "Backtest Start Month")
testStartDay = input(2, "Backtest Start Day")
testPeriodStart = timestamp(testStartYear,testStartMonth,testStartDay,0,0)

testStopYear = input(2019, "Backtest Stop Year")
testStopMonth = input(7, "Backtest Stop Month")
testStopDay = input(30, "Backtest Stop Day")
testPeriodStop = timestamp(testStopYear,testStopMonth,testStopDay,0,0)

// A switch to control background coloring of the test period
testPeriodBackground = input(title="Color Background?", type=bool, defval=true)
testPeriodBackgroundColor = testPeriodBackground and (time >= testPeriodStart) and (time <= testPeriodStop) ? #00FF00 : na
bgcolor(testPeriodBackgroundColor, transp=97)

testPeriod() => true
// Component Code Stop

//standard rsi template
src = ohlc4, len = input(14, minval=1, title="Length")
up = rma(max(change(src), 0), len)
down = rma(-min(change(src), 0), len)
rsi = down == 0 ? 100 : up == 0 ? 0 : 100 - (100 / (1 + up / down))
plot(rsi, color=#87ff1a)
band1 = hline(80)
band = hline(50)
band0 = hline(20)
fill(band1, band0, color=purple, transp=90)

//macd

fast_length = input(title="Fast Length",  defval=9)
slow_length = input(title="Slow Length",  defval=72)
signal_length = input(title="Signal Length",  defval=9)

fast_ma = sma(rsi, fast_length)
slow_ma = sma(rsi, slow_length)
shortma = sma(ohlc4, fast_length)
longma = sma(ohlc4, slow_length)
controlmainput = input(title = "Control MA", defval = 234)
controlma = sma(ohlc4, controlmainput)
macdx = fast_ma - slow_ma
signalx = sma(macdx, signal_length)
hist = macdx - signalx
ma_hist = shortma - controlma
macd = macdx + 50
signal = signalx + 50

plot(macd,"macd", color = fuchsia)
plot(hist,"hist", style = histogram, color = fuchsia)
//plot(ma_hist,"ma hist", style = histogram, color = orange)
plot(signal,"signal", color = white)

//input
control_buy_toggle = input(true, "Buy on crossover control MA?", type = bool)
buy_on_control = control_buy_toggle == true? true : false

//conditions
buy = buy_on_control == true? ma_hist > 0 and shortma > longma and crossover(macd,signal) or crossover(shortma, controlma) : ma_hist > 0 and shortma > longma and crossover(macd,signal)
sell = ma_hist > 0 and shortma > longma and crossunder(macd,signal)
stop = crossunder(shortma, longma) or crossunder(shortma, controlma)

plotshape(buy,"buy", shape.triangleup, location.bottom, green, size = size.tiny)
plotshape(sell,"sell", shape.triangledown, location.bottom, red, size = size.tiny)
plotshape(stop,"stop",shape.circle,location.bottom, white, size = size.tiny)

if testPeriod()
    strategy.entry("buy", true, when = buy, limit = close)
    strategy.close("buy", when = sell)
    strategy.close("buy", when = stop)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-10-23. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/RSI-MACD-Crossover-Double-MA-Tracking-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dual SMA Crossover StrategyPine Script · Trend following · 5m
- Dynamic Dual EMA Crossover Strategy with Adaptive Profit Loss ControlPine Script · Trend following · 1d
- EMA SMA Multi Indicator Comprehensive Trend Following StrategyPine Script · Trend following · 1h
- EMA and RSI Trend Trading StrategyPine Script · Trend following · 1d