Strategy vault / Trend following
Single Moving Average Crossover Bollinger Bands Strategy
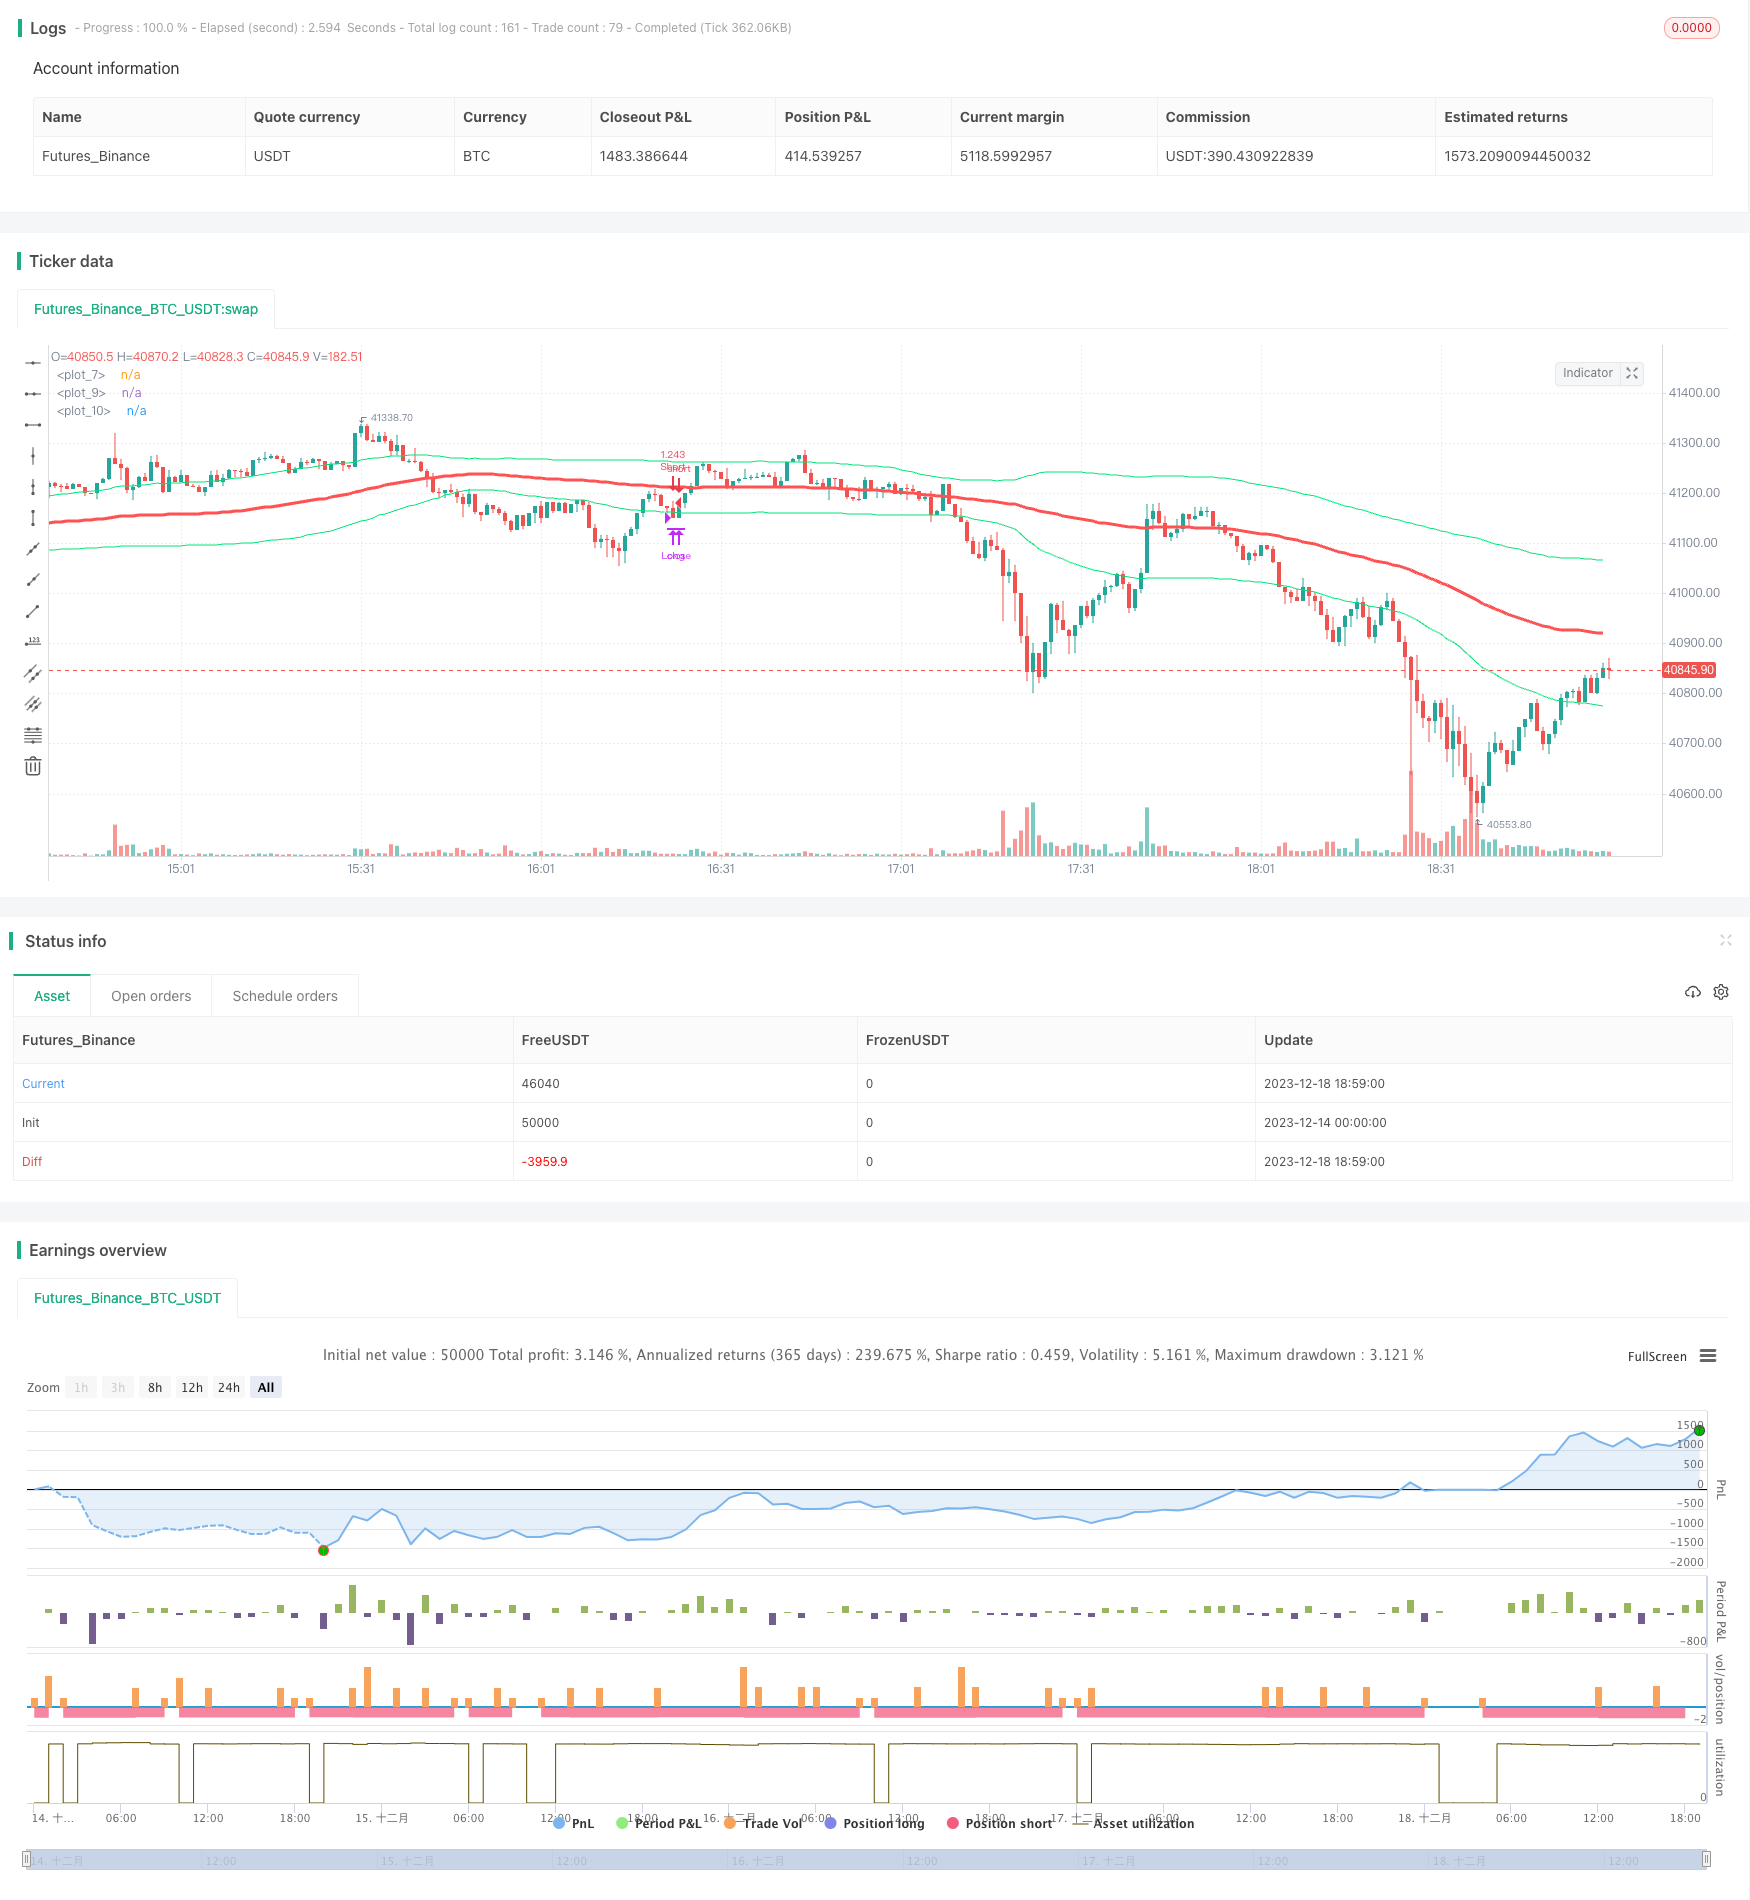
This strategy is based on single moving average and Bollinger Bands indicator. It generates buy and sell signals when price breaks through the upper or lower band of Bollinger Bands. Also it incorporates the…
Overview
This strategy is based on single moving average and Bollinger Bands indicator. It generates buy and sell signals when price breaks through the upper or lower band of Bollinger Bands. Also it incorporates the direction of moving average to determine the trend, only taking long when MA is rising and short when MA is falling.
Strategy Logic
The strategy mainly uses the following indicators for judgment:
- Moving Average (SMA): Simple moving average of CLOSE price, representing the price trend.
- Upper Bollinger Band: Represents the resistance level, breakout indicates a strong momentum.
- Lower Bollinger Band: Represents the support level, breakdown indicates a possible trend reversal.
The specific trading signals are:
- Buy Signal: When close price breaks through the upper band and the MA is rising.
- Sell Signal: When close price breaks through the lower band and the MA is falling.
By combining the trend and breakout, the trading signal becomes more reliable and avoids false breakout.
Advantages
- Simple and clear rules, easy to understand and implement.
- MA judges the general trend to avoid short bull and long bear market.
- Bollinger Bands upper & lower band locates local breakout points accurately.
- Relatively small drawdowns, matches most people's risk preference.
Risks
- Single indicator tends to generate false signals, can be improved by parameter tuning.
- Cannot cope with large market fluctuations, can adjust stop loss accordingly.
- Unable to profit more from mega trends, can consider larger position size.
Improvements
- Optimize MA periods to fit more products.
- Add other filters like MACD to reduce false signals.
- Dynamically adjust stop loss to limit maximum drawdown.
- Introduce money management to stabilize PnL performance.
Conclusion
In general this is a simple but practical strategy suitable for most people. With some tuning and optimizations it can be more robust and adaptive to more market situations. It is a strategy worth recommending.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 90 | s |
| v_input_2 | 0.9 | p |
| v_input_3 | false | Take Profit |
| v_input_4 | false | Stop Loss |
| v_input_5 | false | Trailing Stop Loss |
| v_input_6 | false | Trailing Stop Loss Offset |
Source Pine Script
/*backtest
start: 2023-12-14 00:00:00
end: 2023-12-18 19:00:00
period: 1m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=2
strategy(title="single sma cross", shorttitle="single sma cross",default_qty_type = strategy.percent_of_equity, default_qty_value = 100,overlay=true,currency="USD")
s=input(title="s",defval=90)
p=input(title="p",type=float,defval=.9,step=.1)

sa=sma(close,s)
plot(sa,color=red,linewidth=3)
band=stdev(close,s)*p
plot(band+sa,color=lime,title="")
plot(-band+sa,color=lime,title="")

// ===Strategy Orders============================================= ========
inpTakeProfit = input(defval = 0, title = "Take Profit", minval = 0)
inpStopLoss = input(defval = 0, title = "Stop Loss", minval = 0)
inpTrailStop = input(defval = 0, title = "Trailing Stop Loss", minval = 0)
inpTrailOffset = input(defval = 0, title = "Trailing Stop Loss Offset", minval = 0)
useTakeProfit = inpTakeProfit >= 1 ? inpTakeProfit : na
useStopLoss = inpStopLoss >= 1 ? inpStopLoss : na
useTrailStop = inpTrailStop >= 1 ? inpTrailStop : na
useTrailOffset = inpTrailOffset >= 1 ? inpTrailOffset : na

longCondition = crossover(close,sa+band) and rising(sa,5)
shortCondition = crossunder(close,sa-band) and falling(sa,5)
crossmid = cross(close,sa)


strategy.entry(id = "Long", long=true, when = longCondition)
strategy.close(id = "Long", when = shortCondition)
strategy.entry(id = "Short", long=false, when = shortCondition)
strategy.close(id = "Short", when = longCondition)
strategy.exit("Exit Long", from_entry = "Long", profit = useTakeProfit, loss = useStopLoss, trail_points = useTrailStop, trail_offset = useTrailOffset, when=crossmid)
strategy.exit("Exit Short", from_entry = "Short", profit = useTakeProfit, loss = useStopLoss, trail_points = useTrailStop, trail_offset = useTrailOffset, when=crossmid)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-22. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Single-Moving-Average-Crossover-Bollinger-Bands-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- EMA and RSI Trend Trading StrategyPine Script · Trend following · 1d
- Multi Indicator Trend Following Strategy with Dynamic Risk ManagementPine Script · Trend following · 2h
- Relative Volume Trend Following Trading StrategyPine Script · Trend following · 1d
- Trend Following Strategy Based on EMA and SMA CrossoverPine Script · Trend following · 1h
- Dual Rail Trend Tracking StrategyPine Script · Trend following · 3h