Strategy vault / Trend following
Single Side Entry Strategy Based on Moving Average
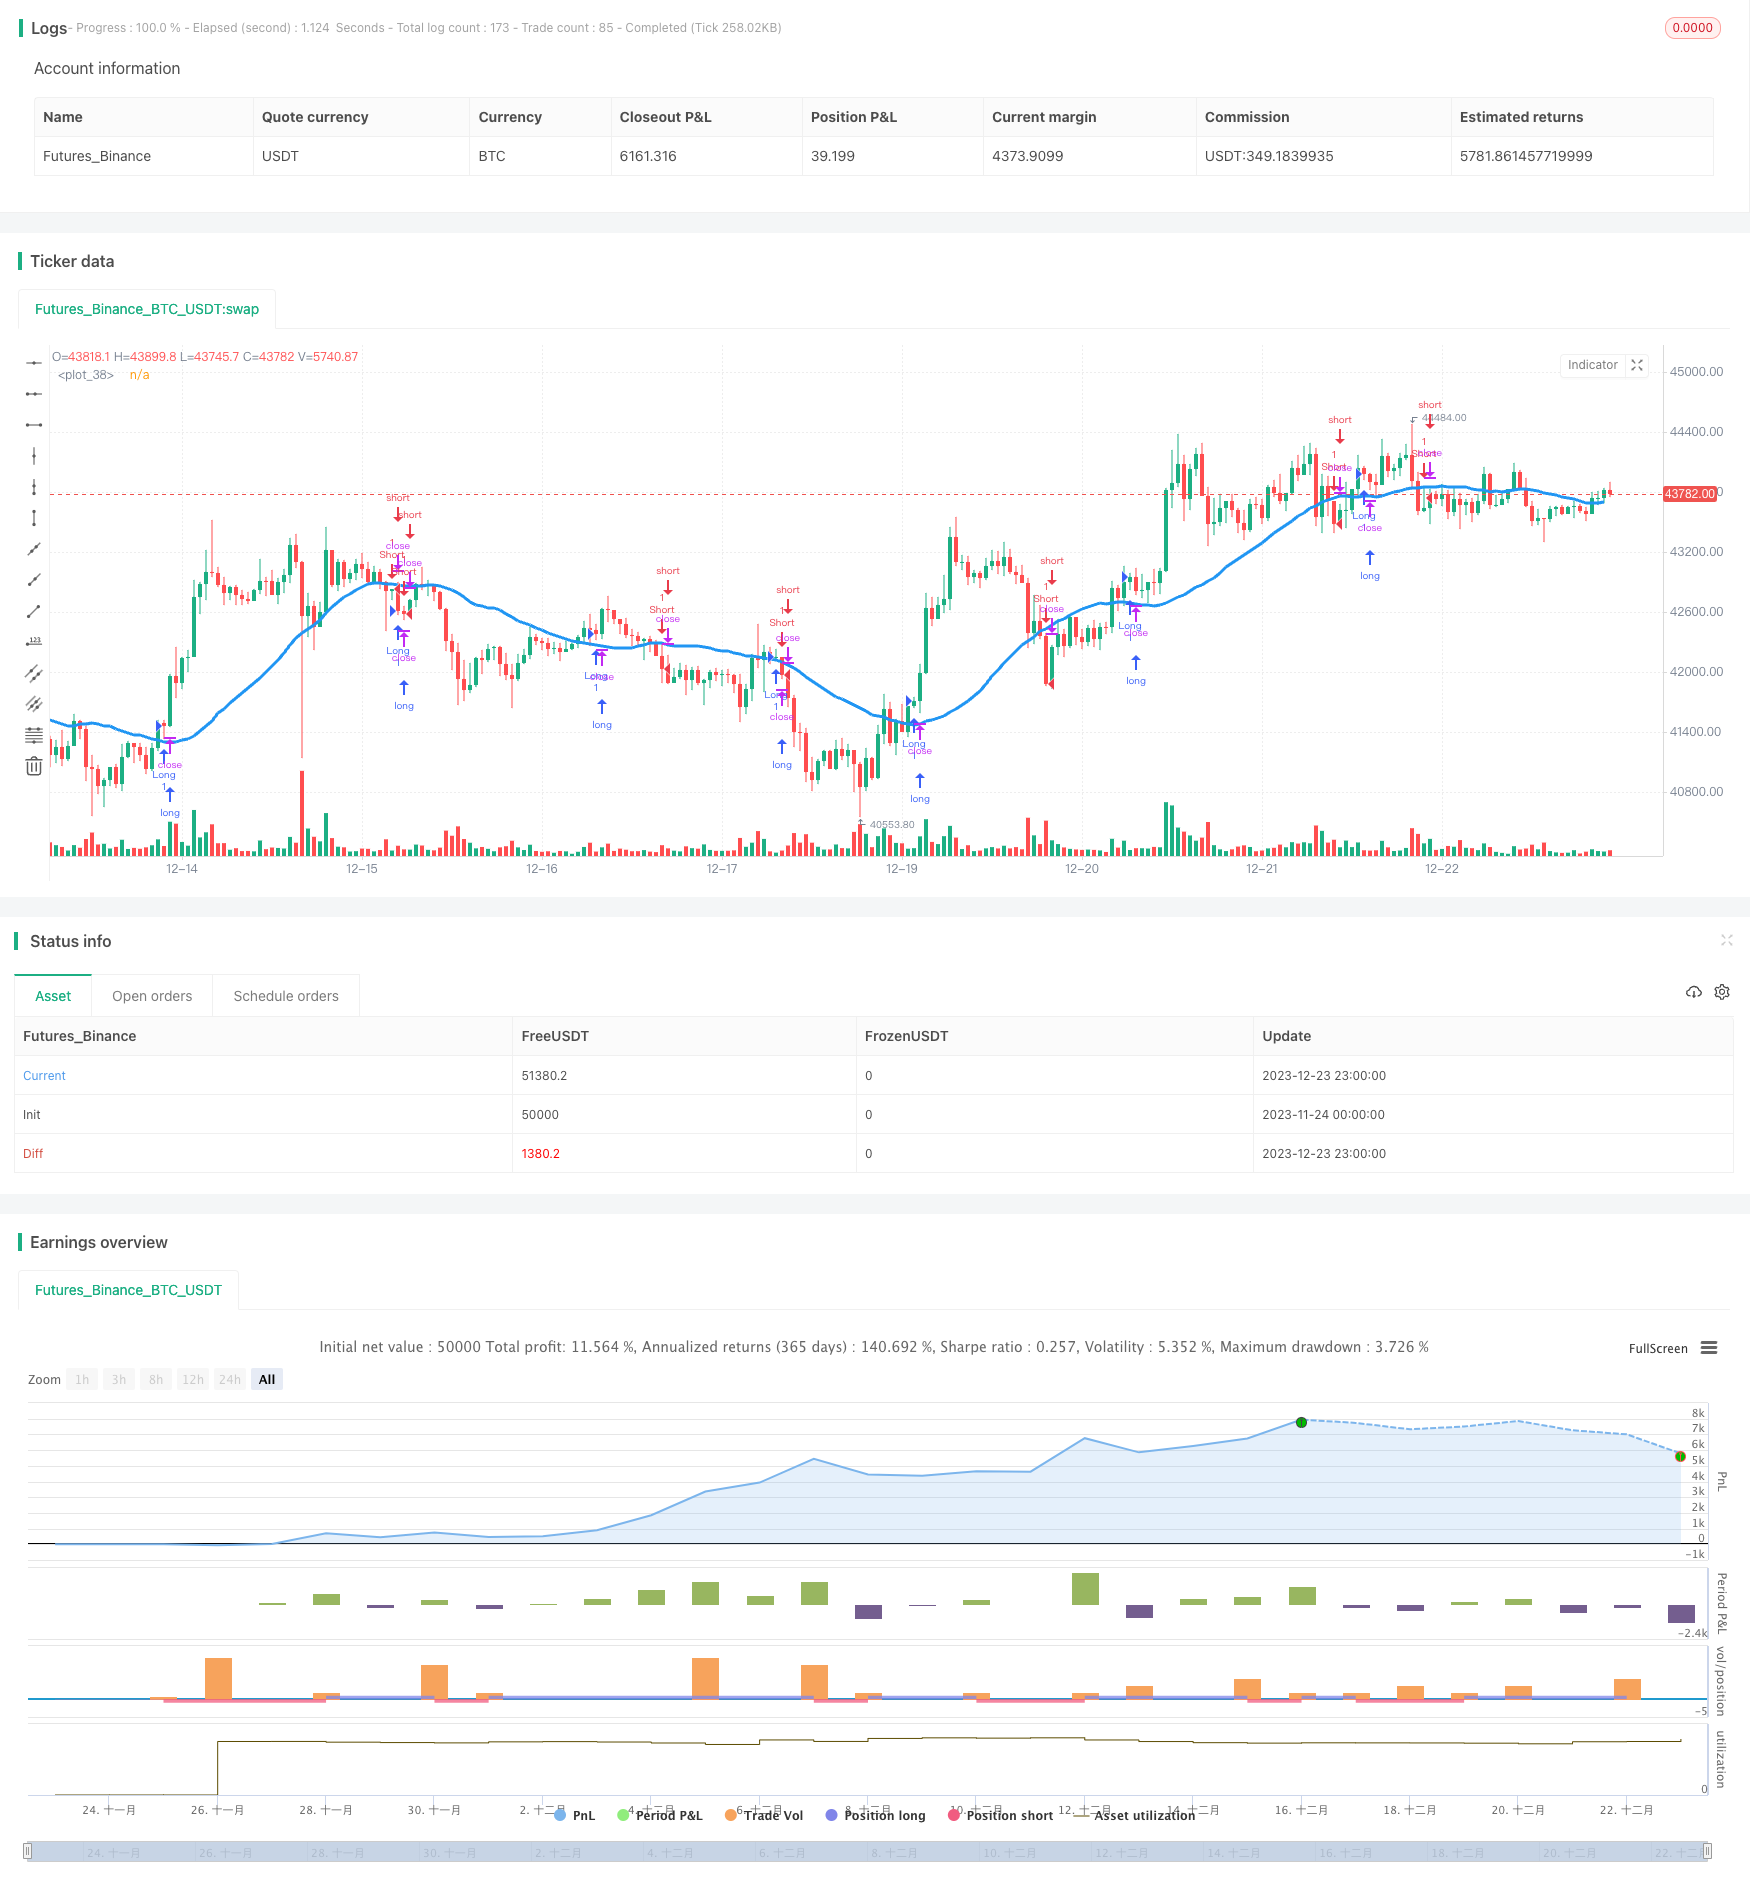
This strategy calculates different types of moving averages to determine the price trend direction and implement single-side entry. It opens long or short positions when the price breaks through the moving average.
Overview
This strategy calculates different types of moving averages to determine the price trend direction and implement single-side entry. It opens long or short positions when the price breaks through the moving average.
Strategy Principle
The strategy allows selecting from 7 different moving average types, including Simple Moving Average (SMA), Exponential Moving Average (EMA), Volume-Weighted Moving Average (VWMA), Double Exponential Moving Average (DEMA), Triple Exponential Moving Average (TEMA), Kaufman's Adaptive Moving Average (KAMA) and Price Channel Middle Line. It judges the price trend direction based on the relationship between the selected moving average and the closing price.
When the closing price breaks through the moving average line upward, it is judged as an uptrend and a long position is opened. When the closing price breaks through the moving average line downward, it is judged as a downtrend and a short position is opened. This can capture turning points in the price trend and achieve single-side entry.
Advantage Analysis
The advantages of this strategy are:
Various types of moving averages can be selected for flexibility to suit different products and cycles.
Single-side entry can effectively control risks.
Entry in the trending direction is easy to profit.
It is easy to understand and implement.
Risk Analysis
There are also some risks with this strategy:
When the price oscillates around the moving average line, there will be multiple false signals and reverse entry positions. Proper stop loss should be set to control risks.
It cannot completely avoid risks caused by rapid up or down price movements. Other indicators should be combined to determine the trend signal.
The analyst needs to select appropriate moving average parameters. Unsuitable parameters can easily lead to lagging of the trading signals.
Optimization Directions
The strategy can be optimized from the following aspects:
Combine with other technical indicators such as MACD, RSI to judge the trend signal and form a trading combination.
Add stop loss logic, such as trailing stop loss or pending order stop loss.
Test and optimize parameters like moving average period, moving average type to find the optimal parameter combination.
Consider using MarketIfTouched order type for entry, to follow the trend.
Summary
The strategy determines the price trend direction based on moving averages, and implements single-side entry. It is simple to use and implement, and can effectively control risks. But there are also risks of false signals and reverse entries. It can be continually improved by combining other signal indicators, optimizing parameters, adding stop loss, to make the strategy more stable and reliable.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | long |
| v_input_2 | true | short |
| v_input_3 | 30 | MA length |
| v_input_4 | true | Type |
| v_input_5_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_6 | true | Antipila |
Source Pine Script
/*backtest
start: 2023-11-24 00:00:00
end: 2023-12-24 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=2
strategy(title = "Noro's MAs Tests v1.1", shorttitle = "MAs tests 1.1", overlay=true, default_qty_type = strategy.percent_of_equity, default_qty_value=100.0, pyramiding=0)

needlong = input(true, "long")
needshort = input(true, "short")
len = input(30, defval = 30, minval = 2, maxval = 1000, title = "MA length")
type = input(1, defval = 1, minval = 1, maxval = 7, title = "Type")
src = input(close, defval = close, title = "Source")
anti = input(true, defval = true, title = "Antipila")

//DEMA
dema = 2 * ema(src, len) - ema(ema(close, len), len)

//TEMA
xPrice = close
xEMA1 = ema(src, len)
xEMA2 = ema(xEMA1, len)
xEMA3 = ema(xEMA2, len)
tema = 3 * xEMA1 - 3 * xEMA2 + xEMA3

//KAMA
xvnoise = abs(src - src[1])
nfastend = 0.20
nslowend = 0.05
nsignal = abs(src - src[len])
nnoise = sum(xvnoise, len)
nefratio = iff(nnoise != 0, nsignal / nnoise, 0)
nsmooth = pow(nefratio * (nfastend - nslowend) + nslowend, 2)
kama = nz(kama[1]) + nsmooth * (src - nz(kama[1]))

//PriceChannel
lasthigh = highest(src, len)
lastlow = lowest(src, len)
center = (lasthigh + lastlow) / 2

ma = type == 1 ? sma(src, len) : type == 2 ? ema(src, len) : type == 3 ? vwma(src, len) : type == 4 ? dema : type == 5 ? tema : type == 6 ? kama : type == 7 ? center : 0

plot(ma, color = blue, linewidth = 3, transp = 0)

trend = anti == false and close > ma ? 1 : anti == false and close < ma ? -1 : low > ma ? 1 : high < ma ? -1 : trend[1]

longCondition = trend == 1 and trend[1] == -1
if (longCondition)
    strategy.entry("Long", strategy.long, needlong == false ? 0 : na)

shortCondition = trend == -1 and trend[1] == 1
if (shortCondition)
    strategy.entry("Short", strategy.short, needshort == false ? 0 : na)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-25. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Single-Side-Entry-Strategy-Based-on-Moving-Average.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dynamic Dual EMA Crossover Strategy with Adaptive Profit Loss ControlPine Script · Trend following · 1d
- EMA SMA Multi Indicator Comprehensive Trend Following StrategyPine Script · Trend following · 1h
- EMA and RSI Trend Trading StrategyPine Script · Trend following · 1d
- Fixed Range Volume Profile And Anchored VWAP Trend Identification Strategy With Dynamic Stop LossPine Script · Trend following · 1h