Super Momentum Strategy
The Super Momentum strategy combines multiple momentum indicators. It buys when multiple momentum indicators are bullish concurrently, and sells when they are bearish concurrently. By integrating multiple momentum…
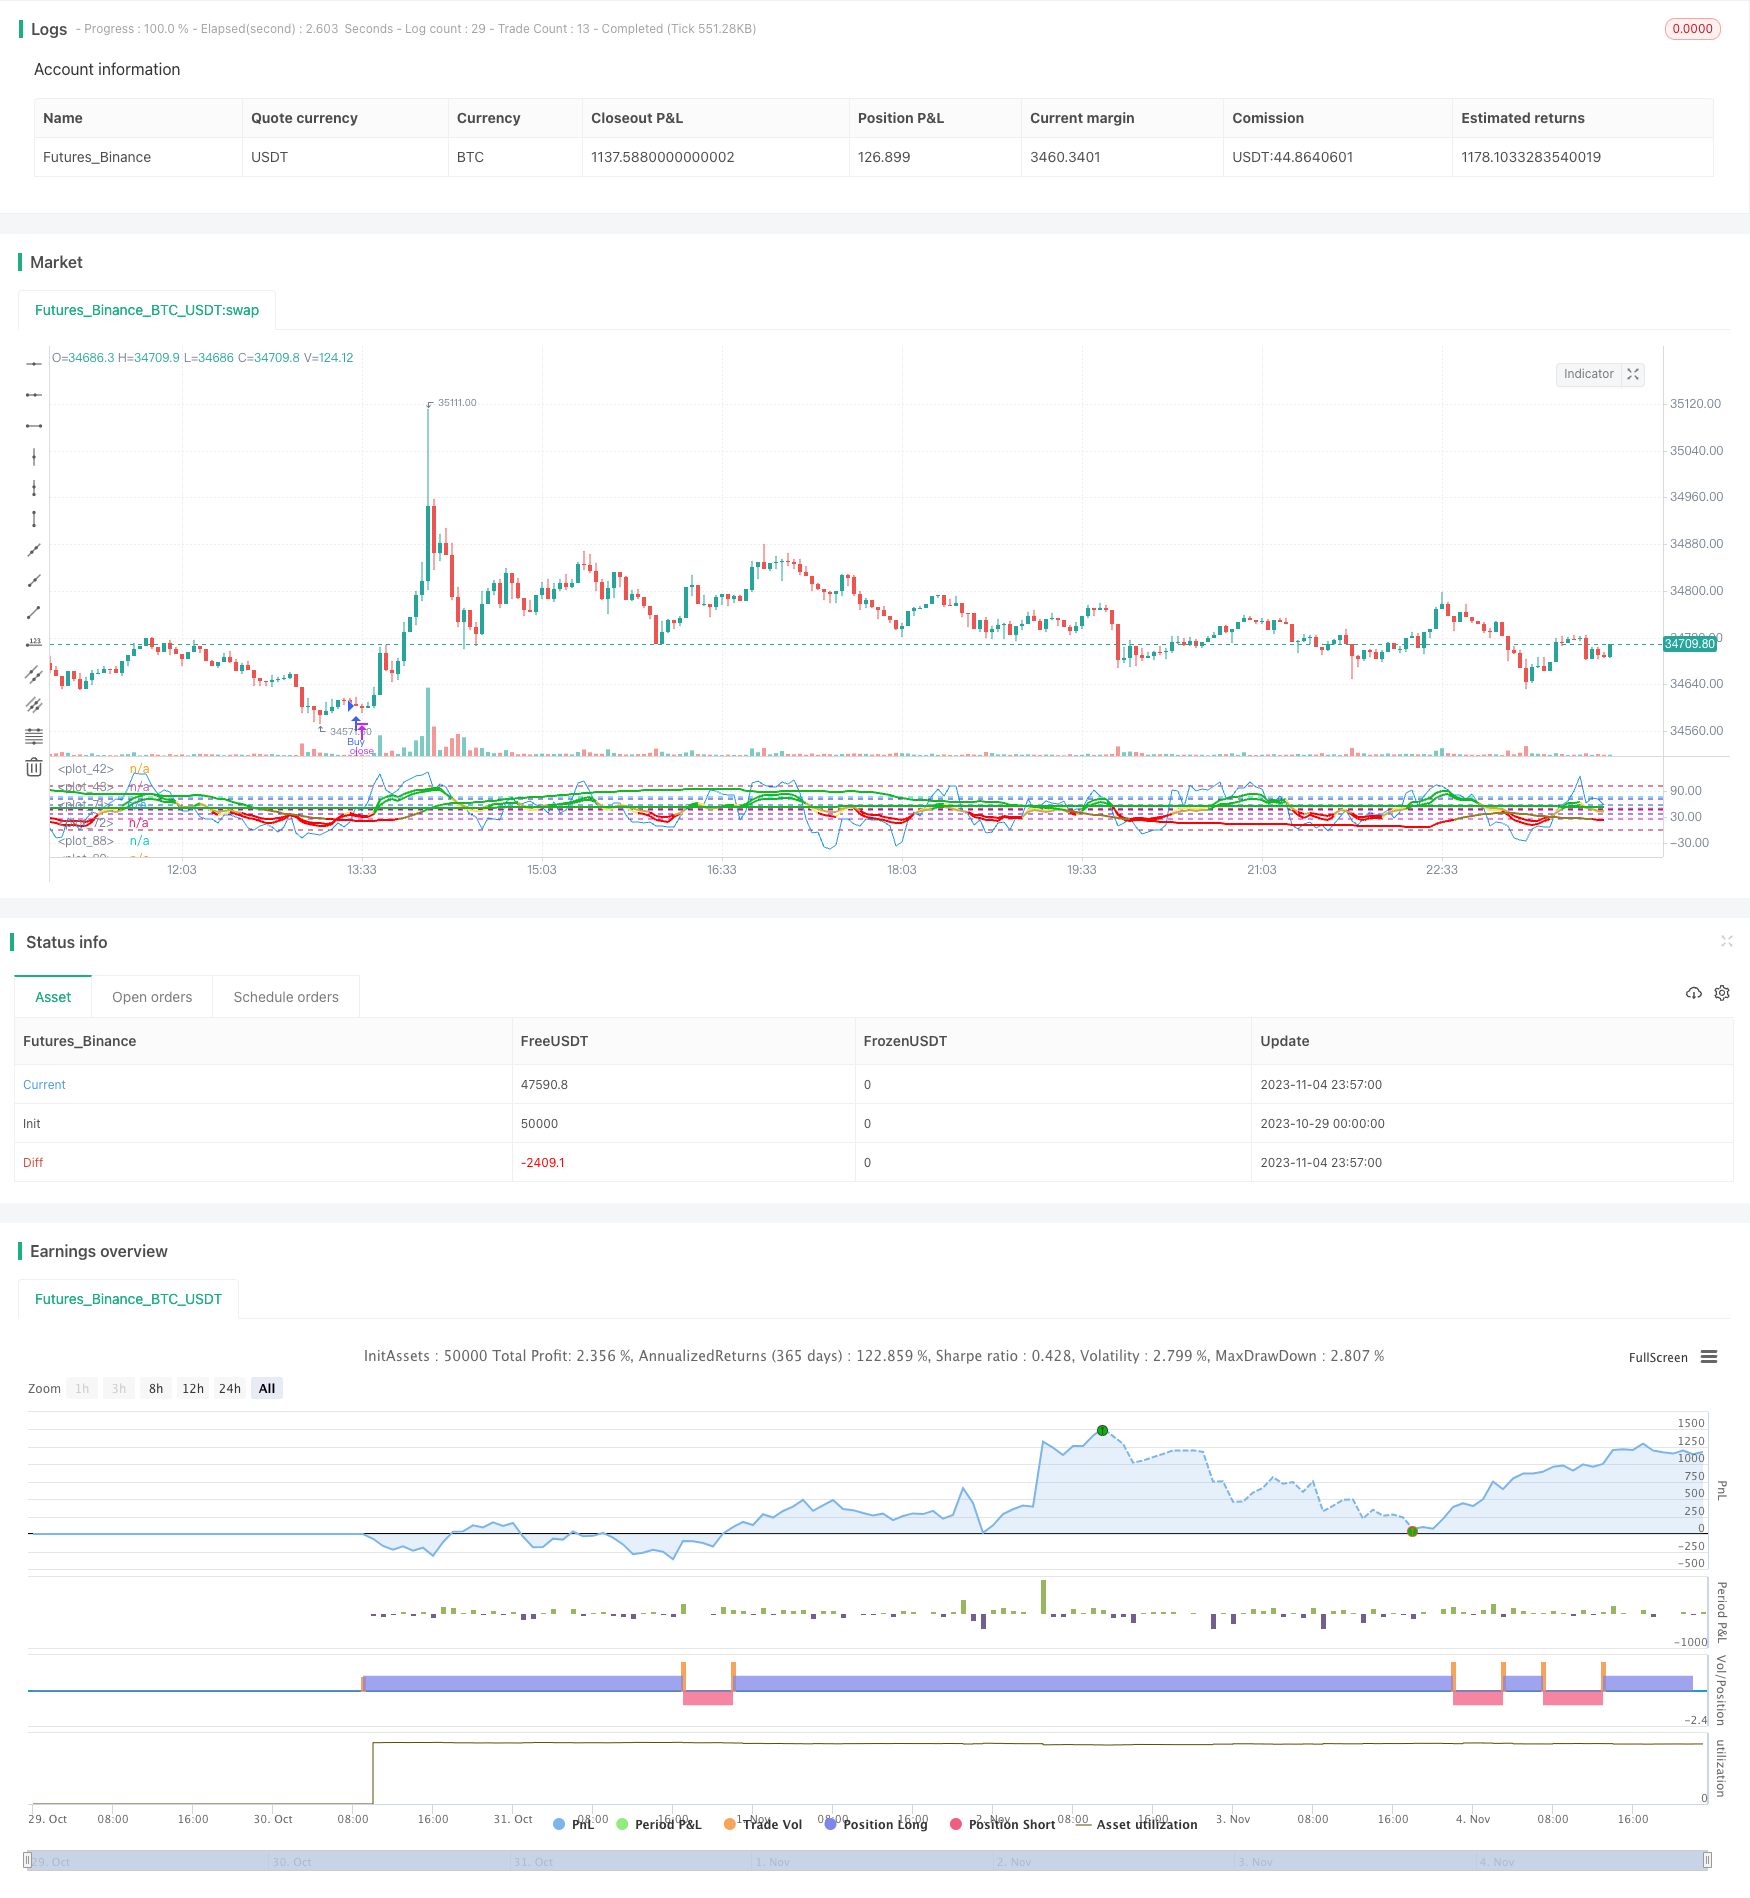
Overview
The Super Momentum strategy combines multiple momentum indicators. It buys when multiple momentum indicators are bullish concurrently, and sells when they are bearish concurrently. By integrating multiple momentum indicators, it aims to capture price trends more accurately and avoid false signals from individual indicators.
Strategy Logic
The strategy uses 4 RMI indicators by Everget and 1 Chande Momentum Oscillator. RMI measures price momentum to gauge bullish and bearish strength. Chande MO calculates price change to identify overbought and oversold conditions.
It goes long when RMI5 crosses above its buy line, RMI4 crosses below its buy line, RMI3 crosses below its buy line, RMI2 crosses below its buy line, RMI1 crosses below its buy line, and Chande MO crosses above its buy line.
It goes short when RMI5 crosses below its sell line, RMI4 crosses above its sell line, RMI3 crosses above its sell line, RMI2 crosses above its sell line, RMI1 crosses above its sell line, and Chande MO crosses below its sell line.
RMI5 is set opposite to other RMI to better identify trends for pyramid trading.
Advantage Analysis
Combining multiple indicators improves trend accuracy and avoids false signals
Indicators across timeframes catch larger trends
Reverse RMI aids in trend identification and pyramiding
Chande MO prevents bad trades in overbought/oversold conditions
Risk Analysis
Complex parameters with multiple indicators need thorough optimization
Concurrent indicator moves may generate false signals
Lower trade frequency with multiple filters
Parameters may not suit different products and market regimes
Optimization Directions
Test and optimize parameters for strategy robustness
Add/remove indicators to evaluate signal quality impact
Introduce filters to avoid false signals in certain markets
Adjust indicator buy/sell lines to find optimal combinations
Consider adding stop loss for risk control
Conclusion
This strategy improves trend judgment by integrating momentum indicators. But parameter optimization is crucial due to complexity. If well-tuned, it can generate quality signals and has an edge in trend following. But traders should watch for risks, find optimal parameters, and incorporate risk controls for steady trading.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 2021 | Backtest Start Year |
| v_input_2 | true | Backtest Start Month |
| v_input_3 | true | Backtest Start Day |
| v_input_4 | 999999 | Backtest Stop Year |
| v_input_5 | 9 | Backtest Stop Month |
| v_input_6 | 26 | Backtest Stop Day |
| v_input_7_close | 0 | Price: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_8 | true | Highlight Overbought/Oversold Breakouts ? |
| v_input_9 | 9 | Alpha Chande Momentum Length |
| v_input_10 | 75 | Chande Sellline |
| v_input_11 | 25 | Chande Buyline |
| v_input_12 | 8 | RMI1 Length |
| v_input_13 | 3 | RMI1 Momentum |
| v_input_14 | 57 | RMI1 Sellline |
| v_input_15 | 37 | RMI1 Buyline |
| v_input_16 | 12 | RMI2 Length |
| v_input_17 | 3 | RMI2 Momentum |
| v_input_18 | 72 | RMI2 Sellline |
| v_input_19 | 37 | RMI2 Buyline |
| v_input_20 | 30 | RMI3 Length |
| v_input_21 | 53 | RMI3 Momentum |
| v_input_22 | 46 | RMI3 Sellline |
| v_input_23 | 24 | RMI3 Buyline |
| v_input_24 | 520 | RMI4 Length |
| v_input_25 | 137 | RMI4 Momentum |
| v_input_26 | false | RMI4 Sellline |
| v_input_27 | 100 | RMI4 Buyline |
| v_input_28 | 520 | RMI5 Length |
| v_input_29 | 137 | RMI5 Momentum |
| v_input_30 | false | RMI5 Buy Above |
| v_input_31 | 47 | RMI5 Sell Below |
Source Pine Script
/*backtest
start: 2023-10-29 00:00:00
end: 2023-11-05 00:00:00
period: 3m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy(title="Super Momentum Strat", shorttitle="SMS", format=format.price, precision=2)

//* Backtesting Period Selector | Component *//
//* https://www.tradingview.com/script/eCC1cvxQ-Backtesting-Period-Selector-Component *//
//* https://www.tradingview.com/u/pbergden/ *//
//* Modifications made *//
testStartYear = input(2021, "Backtest Start Year")
testStartMonth = input(1, "Backtest Start Month")
testStartDay = input(1, "Backtest Start Day")
testPeriodStart = timestamp(testStartYear,testStartMonth,testStartDay,0,0)

testStopYear = input(999999, "Backtest Stop Year")
testStopMonth = input(9, "Backtest Stop Month")
testStopDay = input(26, "Backtest Stop Day")
testPeriodStop = timestamp(testStopYear,testStopMonth,testStopDay,0,0)

testPeriod() => true
/////////////// END - Backtesting Period Selector | Component ///////////////


src = input(close, "Price", type = input.source)
highlightBreakouts = input(title="Highlight Overbought/Oversold Breakouts ?", type=input.bool, defval=true)

CMOlength = input(9, minval=1, title="Alpha Chande Momentum Length")


//CMO
momm = change(src)
f1(m) => m >= 0.0 ? m : 0.0
f2(m) => m >= 0.0 ? 0.0 : -m
m1 = f1(momm)
m2 = f2(momm)
sm1 = sum(m1, CMOlength)
sm2 = sum(m2, CMOlength)
percent(nom, div) => 100 * nom / div
chandeMO = percent(sm1-sm2, sm1+sm2)+50
plot(chandeMO, "Chande MO", color=color.blue)

obLevel = input(75, title="Chande Sellline")
osLevel = input(25, title="Chande Buyline")
hline(obLevel, color=#0bc4d9)
hline(osLevel, color=#0bc4d9)


///
///RMIS
//
// Copyright (c) 2018-present, Alex Orekhov (everget)
// Relative Momentum Index script may be freely distributed under the MIT license.
//
///
///


//RMI1
length1 = input(title="RMI1 Length", type=input.integer, minval=1, defval=8)
momentumLength1 = input(title="RMI1 Momentum ", type=input.integer, minval=1, defval=3)
up1 = rma(max(change(src, momentumLength1), 0), length1)
down1 = rma(-min(change(src, momentumLength1), 0), length1)

rmi1 = down1 == 0 ? 100 : up1 == 0 ? 0 : 100 - (100 / (1 + up1 / down1))

obLevel1 = input(57, title="RMI1 Sellline")
osLevel1 = input(37, title="RMI1 Buyline")

rmiColor1 = rmi1 > obLevel1 ? #0ebb23 : rmi1 < osLevel1 ? #ff0000 : #ffe173
plot(rmi1, title="RMI 1", linewidth=2, color=rmiColor1, transp=0)
hline(obLevel1, color=#0b57d9)
hline(osLevel1, color=#0b57d9)


//RMI2
length2 = input(title="RMI2 Length", type=input.integer, minval=1, defval=12)
momentumLength2 = input(title="RMI2 Momentum ", type=input.integer, minval=1, defval=3)
up2 = rma(max(change(src, momentumLength1), 0), length2)
down2 = rma(-min(change(src, momentumLength1), 0), length2)

rmi2 = down2 == 0 ? 100 : up1 == 0 ? 0 : 100 - (100 / (1 + up2 / down2))

obLevel2 = input(72, title="RMI2 Sellline")
osLevel2 = input(37, title="RMI2 Buyline")

rmiColor2 = rmi1 > obLevel1 ? #0ebb23 : rmi2 < osLevel2 ? #ff0000 : #c9ad47
plot(rmi2, title="RMI 2", linewidth=2, color=rmiColor2, transp=0)
hline(obLevel2, color=#5a0bd9)
hline(osLevel2, color=#5a0bd9)

//RMI3
length3 = input(title="RMI3 Length", type=input.integer, minval=1, defval=30)
momentumLength3 = input(title="RMI3 Momentum ", type=input.integer, minval=1, defval=53)
up3 = rma(max(change(src, momentumLength3), 0), length3)
down3 = rma(-min(change(src, momentumLength3), 0), length3)

rmi3 = down3 == 0 ? 100 : up3 == 0 ? 0 : 100 - (100 / (1 + up3 / down3))

obLevel3 = input(46, title="RMI3 Sellline")
osLevel3 = input(24, title="RMI3 Buyline")

rmiColor3 = rmi3 > obLevel3 ? #0ebb23 : rmi3 < osLevel3 ? #ff0000 : #967d20
plot(rmi3, title="RMI 3", linewidth=2, color=rmiColor3, transp=0)
hline(obLevel3, color=#cf0bd9)
hline(osLevel3, color=#cf0bd9)
//RMI4
length4 = input(title="RMI4 Length", type=input.integer, minval=1, defval=520)
momentumLength4 = input(title="RMI4 Momentum ", type=input.integer, minval=1, defval=137)
up4 = rma(max(change(src, momentumLength4), 0), length4)
down4 = rma(-min(change(src, momentumLength4), 0), length4)

rmi4 = down4 == 0 ? 100 : up4 == 0 ? 0 : 100 - (100 / (1 + up4 / down4))

obLevel4 = input(0, title="RMI4 Sellline")
osLevel4 = input(100, title="RMI4 Buyline")

rmiColor4 = rmi4 > obLevel4 ? #0ebb23 : rmi4 < osLevel4 ? #ff0000 : #7a630b
plot(rmi4, title="RMI 4", linewidth=2, color=rmiColor4, transp=0)
hline(obLevel4, color=#bd1150)
hline(osLevel4, color=#bd1150)


//RMI5
length5 = input(title="RMI5 Length", type=input.integer, minval=1, defval=520)
momentumLength5 = input(title="RMI5 Momentum ", type=input.integer, minval=1, defval=137)
up5 = rma(max(change(src, momentumLength5), 0), length5)
down5 = rma(-min(change(src, momentumLength5), 0), length5)

rmi5 = down5 == 0 ? 100 : up4 == 0 ? 0 : 100 - (100 / (1 + up5 / down5))

buy5 = input(0, title="RMI5 Buy Above")
sell5 = input(47, title="RMI5 Sell Below")

rmiColor5 = rmi5 > buy5 ? #0ebb23 : rmi5 < sell5 ? #ff0000 : #7a630b
plot(rmi5, title="RMI 5", linewidth=2, color=rmiColor5, transp=0)
hline(buy5, color=#bd1150)
hline(sell5, color=#bd1150)
///
///END RMIS
//
//
// Relative Momentum Index script may be freely distributed under the MIT license.
//
///
///

hline(50, color=#C0C0C0, linestyle=hline.style_dashed, title="Zero Line")

//alerts


longcondition1 = crossover(chandeMO, osLevel)
shortcondition1 = crossunder(chandeMO, obLevel)
longcondition2 = rmi5>buy5 and rmi4<osLevel4 and rmi3<osLevel3 and rmi2<osLevel2 and rmi1<osLevel1 and longcondition1
shortcondition2 =  rmi5<sell5 and rmi4>obLevel4 and rmi3>obLevel3 and rmi2>obLevel2 and rmi1>obLevel1 and shortcondition1

if testPeriod()
    if longcondition2
        strategy.entry("Buy", strategy.long)
    if shortcondition2
strategy.entry("Sell", strategy.short)Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-06. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Super-Momentum-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX Momentum Trend StrategyPine Script · Momentum · 10m
- Adaptive Trend Following Strategy Based on Momentum OscillatorPine Script · Momentum · 1d
- Advanced Composite Moving Average and Market Momentum Trend Capture StrategyPine Script · Momentum
- Advanced Multi Indicator Trend Following and Momentum Quantitative Trading StrategyPine Script · Momentum · 1h
- Bollinger Bands Momentum Trend Following Quantitative StrategyPine Script · Momentum · 1d
- Confirmed SMA Crossover Momentum StrategyPine Script · Momentum · 1d