Strategy vault / Trend following
Super Trend Reverse Strategy
The Super Trend reverse strategy is a reversal trading strategy that combines the Super Trend indicator and the RSI indicator. This strategy uses the Super Trend to determine the direction of the market trend, and…
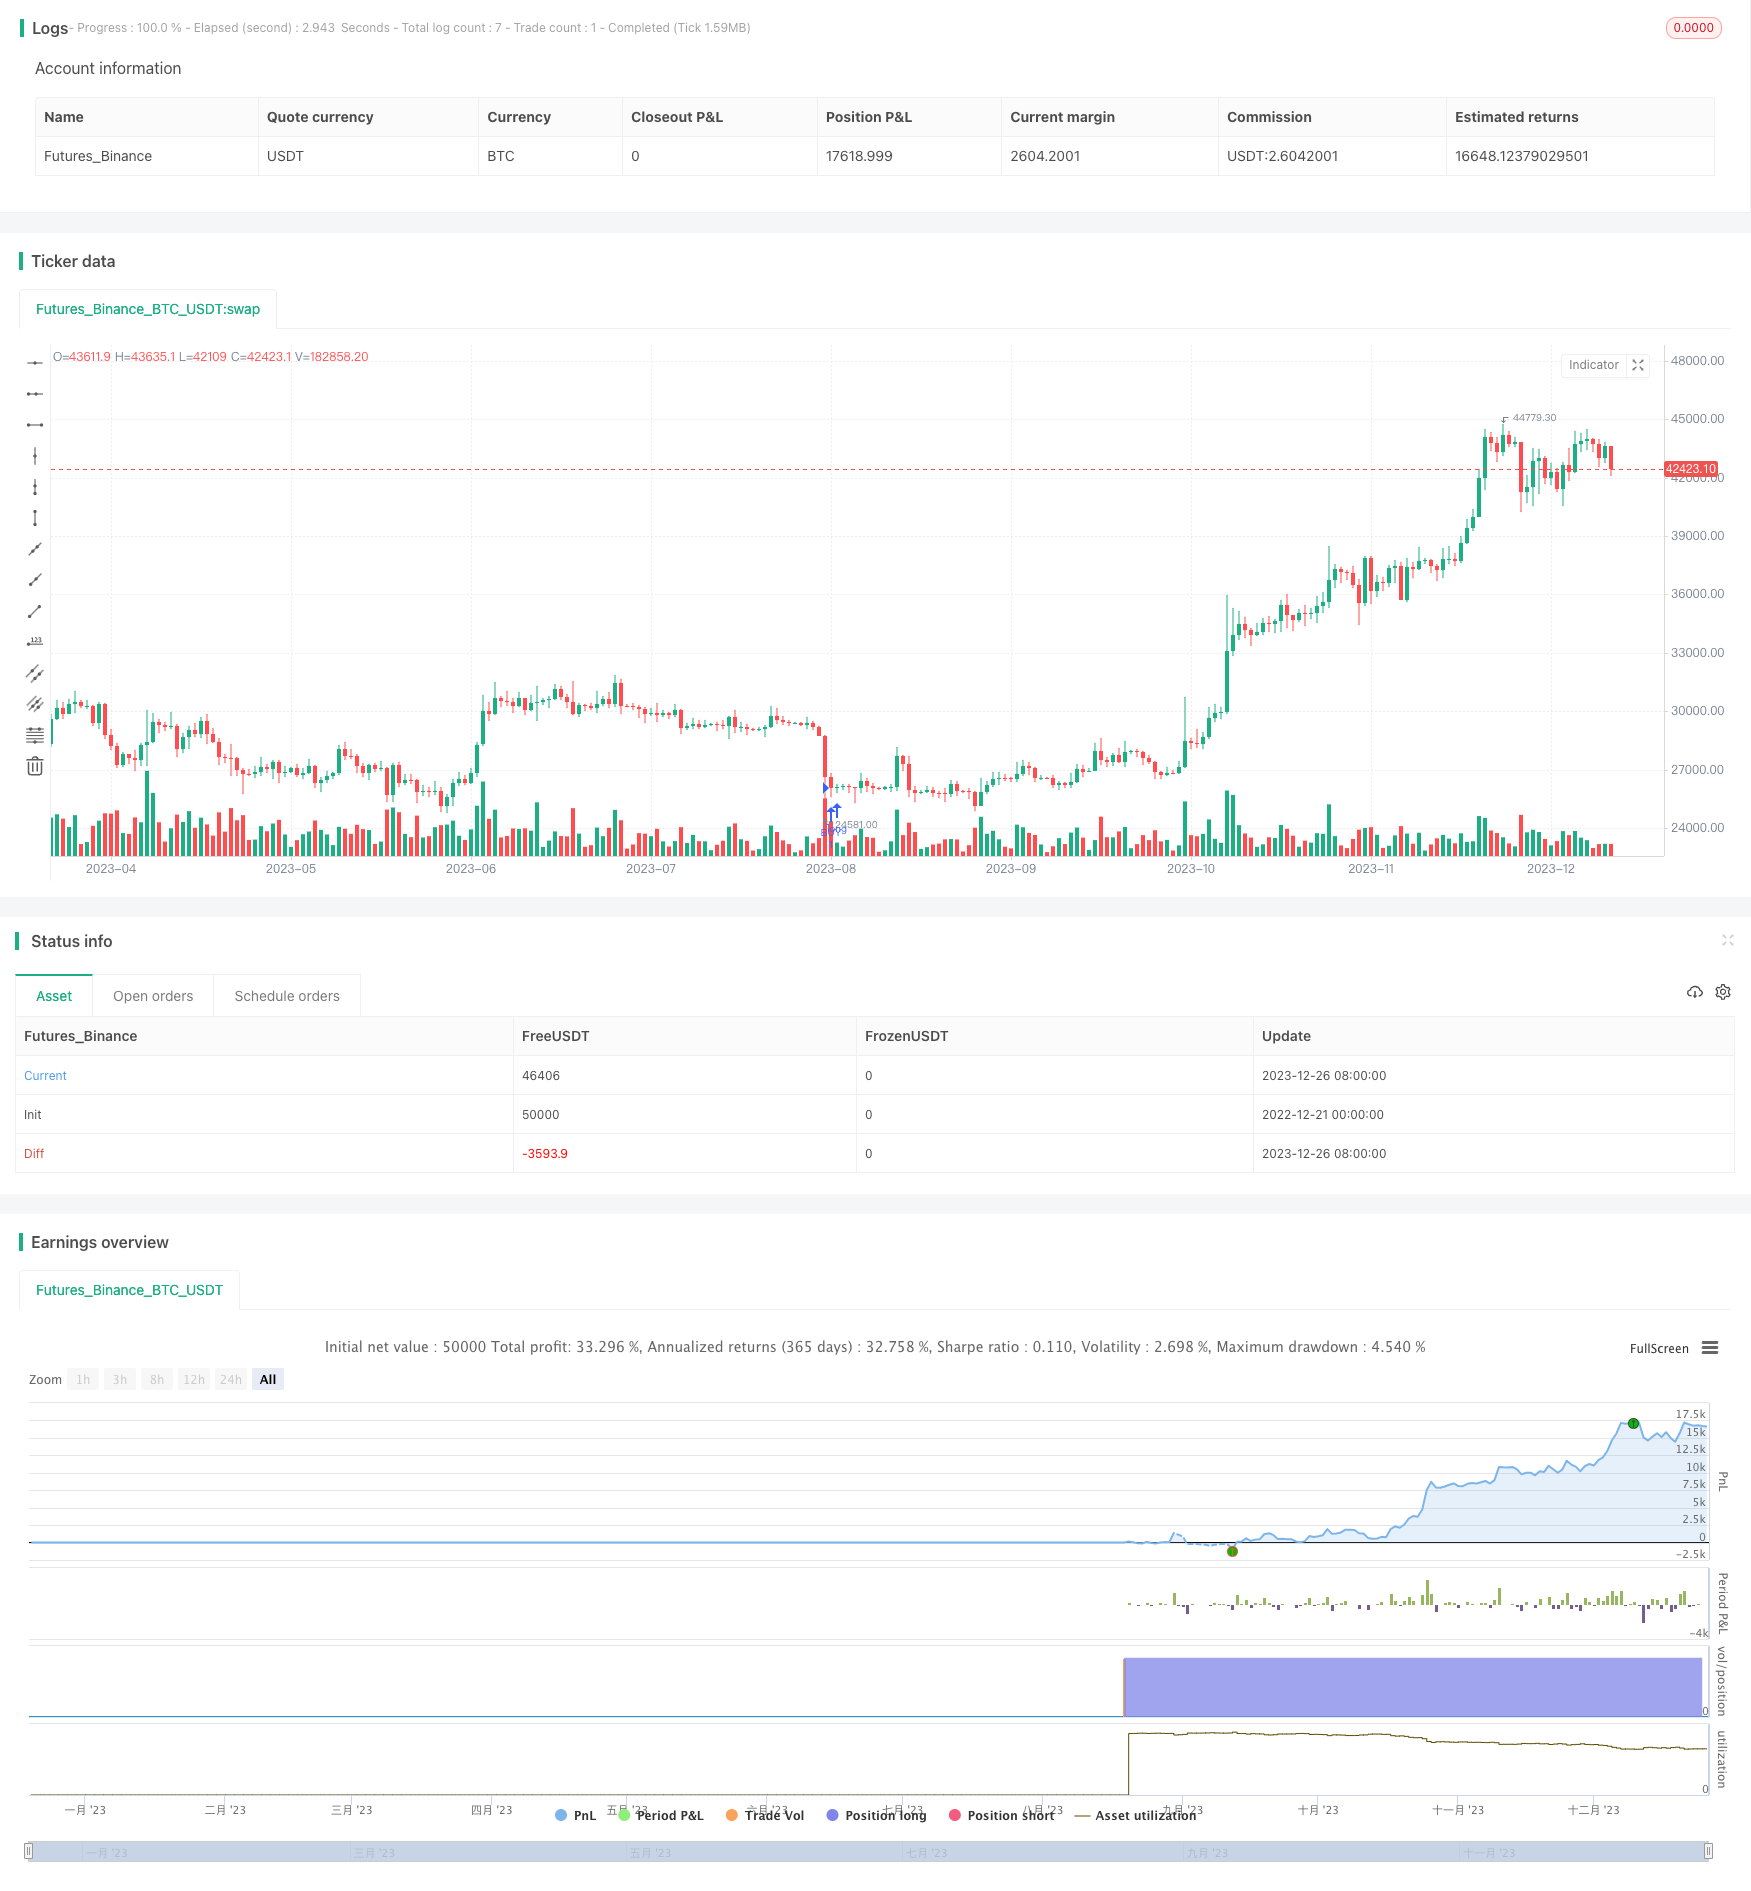
Overview
The Super Trend reverse strategy is a reversal trading strategy that combines the Super Trend indicator and the RSI indicator. This strategy uses the Super Trend to determine the direction of the market trend, and then identifies reversal opportunities in combination with the RSI indicator to make transactions at trend reversal points.
Strategy Principle
The Super Trend reverse strategy consists of two main parts:
Super Trend indicator to judge market trend
The Super Trend indicator calculates the price band based on the current price and the average true range over a certain period to determine the trend direction. When the price breaks through the upper rail, it is bullish; when the price breaks through the lower rail, it is bearish.
RSI indicator to identify reversals
The RSI indicator judges whether it is currently overbought or oversold by comparing the number of up days and down days over a period of time. Combined with the Super Trend indicator, it can detect opportunities for trend reversal.
In this strategy, by certain transformations, we get the processed RSI curve and set threshold lines. When the RSI curve breaks through the corresponding threshold, buy and sell signals are generated.
Advantage Analysis
The Super Trend reverse strategy combines trend and reversal indicators to comprehensively consider the trend strength and overbought/oversold phenomena, so that it can open and close positions at relatively good locations to obtain better strategy returns.
The main advantages are:
- Combining trend and reversal, trading at reversal points
- Controllable drawdown, better risk control
- Large parameter optimization space, adjustable based on market
Risk Analysis
The Super Trend reverse strategy also has some risks, mainly including:
Reversal failure risk
Reversal signals may be false signals and fail to reverse successfully, which may increase losses.
Parameter optimization risk
Improper parameter optimization may cause overfitting of the strategy and inability to adapt to market changes.
Technical indicator lag
All technical indicators have lags, possibly missing the best entry position.
To address these risks, we can further optimize and improve through combining other indicators, adjusting parameter optimization methods, etc.
Optimization Directions
The Super Trend reverse strategy can be optimized in the following dimensions according to market and needs:
- Optimize Super Trend parameters to adapt to different markets
- Optimize or improve RSI reversal trigger logic
- Add stop loss strategy to control single loss
- Combine other indicators to determine reversal reliability
- Add trading volume indicator to avoid false breakouts
Summary
The Super Trend reverse strategy combines the advantages of trend trading and reversal trading, allowing to go with the trend while opening positions at reversal points. By continuously testing and optimizing parameters and appropriately controlling risks, this strategy can obtain stable strategy returns. Its optimization space is also very large, adjustable based on actual market conditions.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 2 | Factor |
| v_input_2 | 14 | RSI Main Period |
| v_input_3 | 5 | RSI Smooth Period |
| v_input_4 | 2018 | yearfrom |
| v_input_5 | 2039 | yearuntil |
| v_input_6 | 6 | monthfrom |
| v_input_7 | 12 | monthuntil |
| v_input_8 | true | dayfrom |
| v_input_9 | 31 | dayuntil |
Source Pine Script
/*backtest
start: 2022-12-21 00:00:00
end: 2023-12-27 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3

strategy(title = "Super-Trend-reverse Strategy", overlay = true)

// Super Trend Strategy
Factor=input(2,type =float, minval=1,maxval = 100)
Pd=10 //input(10,minval=1,maxval = 100)

// ST1

UP=hlc3-(Factor*atr(Pd))

DOWN=hlc3+(Factor*atr(Pd))

// ST1.2

TrendUp=na
TrendUp:=close[1]>TrendUp[1]? max(UP,TrendUp[1]) : UP

TrendDown=na
TrendDown:=close[1]<TrendDown[1]? min(DOWN,TrendDown[1]) : UP


Trend = na
Tsl = na


Trend := close[1] > TrendDown[1] ? 1: close[1] < TrendUp[1]? -1: nz(Trend[1],1)
Tsl := Trend==1 ? TrendUp: TrendDown


/////////////// Functions for Reverse //////////////////////////////

IF(input) => (exp(2*input)-1) / (exp(2*input)+1)

//////////////////////// RSI REVERSE /////////////////////

RSI_main = input(14, title="RSI Main Period")
RSI_smooth = input(5, title="RSI Smooth Period")

//Functions
RVS(input) => (exp(2*input)-1) / (exp(2*input)+1)

//RSI Calculation
raw_RSI=0.1*(rsi(close,RSI_main)-50)
wma_RSI=wma(raw_RSI,RSI_smooth)
RVS_RSI = RVS(wma_RSI)


threshold1 = RVS_RSI < 0.8? 1 : 0
threshold2 = -0.8


RSIbuy = (RVS_RSI<threshold2)
RSIsell = (RVS_RSI > threshold1)


////////////////////// RSI REVERSE ///////////////////////

// Conditions


longCond = na
shortCond = na
longCond :=  RSIbuy and crossover(close, Tsl)
shortCond :=  RSIsell and crossunder(close, Tsl)


yearfrom = input(2018)
yearuntil =input(2039)
monthfrom =input(6)
monthuntil =input(12)
dayfrom=input(1)
dayuntil=input(31)


if (  longCond  and   year >= yearfrom and year <= yearuntil and month>=monthfrom and month <=monthuntil and dayofmonth>=dayfrom and dayofmonth < dayuntil)
    strategy.entry("BUY", strategy.long, stop=close, oca_name="TREND",  comment="BUY")

else
    strategy.cancel(id="BUY")


if ( shortCond and  year >= yearfrom and year <= yearuntil and month>=monthfrom and month <=monthuntil and dayofmonth>=dayfrom and dayofmonth < dayuntil )

    strategy.close("BUY")
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-28. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Super-Trend-Reverse-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive ATR and RSI Trend Following Strategy with Trailing Stop LossPine Script · Trend following · 1h
- Advanced Supertrend Indicator Trading Mechanism Optimization StrategyPine Script · Trend following · 1d
- BB Percentage Index Trend Fading StrategyPine Script · Trend following · 1h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dual Indicator Dynamic Trend Trading Strategy Multi dimensional Technical Analysis System Based on RSI and MACDPine Script · Trend following